Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 167

Are opinions of rating agencies worthwhile?

There’s been a spike in interest in rating agencies recently, due to the recent downgrade in the UK’s rating and the possibility that Australia could follow suit. Yet few people understand what goes into a credit rating and what it’s really worth, if anything. So should investors pay any attention to these agencies, particularly after their poor performance during the financial crisis?

Credit ratings are a mix of qualitative and quantitative factors. The primary driver of a rating is a combination of financial ratios such as debt/EBITDA for corporates or debt/GDP for governments. Analysts overlay a qualitative adjustment to the ratios that can result in a slightly higher or lower outcome than the ratios alone would indicate. The entire process is subjective; what ratios are used, and in what proportion they are weighted. Additionally, the qualitative adjustments are all components that issuers argue about.

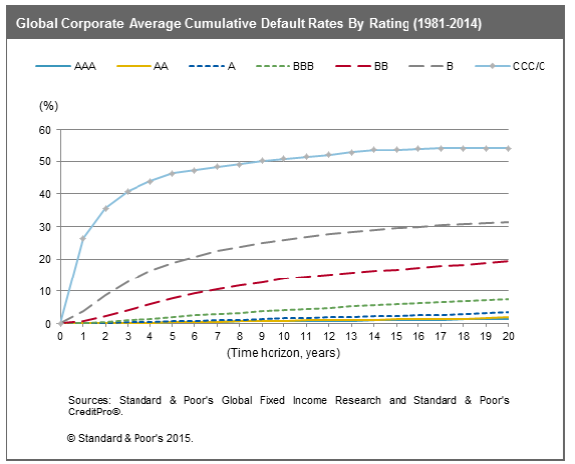
Investors still value agency’s opinions. A lower rating indicates a higher risk of principal and interest not being paid in full. The chart below shows how companies with lower ratings have an exponentially higher probability of defaulting on their debts. As a result, debt issuers with lower ratings must pay a higher interest rate to attract buyers for their debt.
Criticisms of credit agencies

1. Conflicts of interest

Governments, regulators and investors have criticised the big three rating agencies (Standard & Poor’s, Moody’s and Fitch) for charging both issuers and investors for their services. Issuers pay the agencies to prepare a report and provide an opinion on their risk profile. This creates tension as the issuer can threaten not to pay if they don’t like the opinion. Investors pay rating agencies to access detailed reports, though the agencies make the ratings publicly available for free. As a result of this conflict of interest, independent credit research firms such as CreditSights and Egan-Jones have emerged where only investors pay for their analysis.

2. Ratings are not equivalent

One of the biggest misgivings with agency credit ratings is that they apply the same risk rating for different types of debt (e.g. corporate, sovereign, financial institution), meaning they believe that they have equal likelihood of defaulting. As history has shown many times, different types of debt have very different risk profiles. It is reasonable to compare ratings within the same debt type, but erroneous to compare ratings between debt types.

3. Ratings changes are delayed

Investors have long complained that agencies fail to downgrade ratings in a timely fashion. Many prefer credit default swaps as a better measure of the real time probability of default, although these have a tendency to overshoot when negative information comes to light. Rating agencies often give the benefit of the doubt to debt issuers as downgrading a rating is typically a controversial step that the issuer may publicly disagree with.

4. Performance in the financial crisis

Very poor performances during the financial crisis means the big three aren’t trusted anywhere near as much as they used to be. Lehman Brothers had 'A' ratings when it defaulted and many other failing banks were similarly rated. Thousands of ratings and trillions of dollars of debt were downgraded across mortgage-backed securities and collateralised debt obligations from 2007 onwards. In the worst examples, securities went from AAA to defaulting within a year. Investors who failed to do their own due diligence suffered substantial losses and many took legal action as a result.

Merits of ratings for different debt types

1. Corporate debt

Ratings on corporate debt are the bread and butter of rating agencies and it is where they do their best work. Thousands of companies have been publicly rated with Moody’s data set stretching back to 1920. Annual reports from the agencies confirm that lower-rated corporates are far more likely to default than higher-rated ones. On the whole, there are few examples of highly rated corporates defaulting, with Enron and Parmalat arguably the worst in recent decades. Both of these involved financial deception by management. The main criticism of corporate debt ratings is the slowness of downgrades as companies deteriorate. Investors can generally expect corporate credit ratings to be an approximately fair reflection of default risk.

2. Sovereign debt

Rating agencies are almost always too optimistic in regards to their ratings for developed nations. The standout example is Japan, with the big three all seeing it in the “A” category. Most independent analysis of Japan has it unable to repay its debt without printing money. If the average interest rate on its debt was to rise by 3% all government revenues would be consumed by interest payments with nothing left for healthcare, education or defence spending. Many governments in Europe and the US continue to receive high ratings even though they are running substantial budget deficits year after year and have sizeable unfunded pension obligations. Ratings for developing nations tend to be a fairer reflection of their risk of defaulting. Investors should treat sovereign debt ratings with great caution.

3. Financial institutions debt

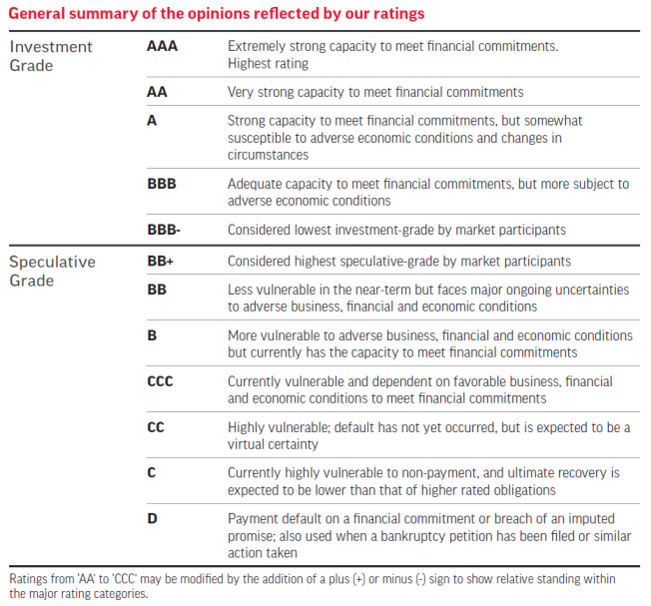
Rating agencies tend to be way too optimistic in rating large banks and somewhat less optimistic in their opinions of smaller banks. For large banks, credit ratings have a substantial impact on their ability to attract institutional funding and to trade with their counterparts. A downgrade below investment grade (below BBB-) is effectively a death knell. AIG and Lehman Brothers were examples of hugely optimistic ratings during 2008. Comparisons are now being made between Lehman Brothers and Deutsche Bank, which could see its funding and trading opportunities rapidly disappear if it suffers further downgrades. Several Italian banks are being talked about as needing government bailouts yet still have credit ratings in the “B” and “BB” categories. Investors should also treat credit ratings of financial institutions with great caution.

4. Securitised debt

Rating agencies were rightly excoriated for their ratings of securitised debt such as mortgage-backed securities and collateralised debt obligations in the lead-up to the financial crisis. As highlighted in the movie The Big Short, rating agencies gave inflated ratings to securitised debt to protect their market share and maximise revenues. However, since the financial crisis, rating agencies have dramatically increased their analysis of securitised debt to the point where the ratings are generally pessimistic. In a reverse of the situation for other types of debt, agencies are now being criticised for failing to upgrade ratings in a timely fashion when securitised transactions perform in line or better than expected. Investors can generally expect securitised debt credit ratings to be an approximately fair reflection of default risk, but need to bear in mind the diversity within securitised debt and the range of complex assumptions required to produce a rating.

Conclusion

Credit ratings play an important part in the functioning of capital markets, but should always be treated as an opinion not a definitive judgement. Investors should conduct their own financial analysis and form their own judgement before investing.
Rochford-chart2 

Source: Standard & Poor's

Jonathan Rochford is Portfolio Manager at Narrow Road Capital and this article expresses the personal views of the author at a point in time. It is for educational purposes and is not a substitute for professional financial advice. Narrow Road Capital advises on and invests in a wide range of securities.

  •   4 August 2016
  • 3
  •      
  •   
3 Comments
Warren Bird
August 04, 2016

Good summary, Jonathan. The other thing I always tell people to keep in mind is that a rating is not a recommendation to invest. It is an assessment - an opinion, as you point out - of the risk of the issuer defaulting. It says nothing about the liquidity of the issue, or whether the return it is being priced to deliver compared to similar risk assets is attractive or not. It also says nothing about the likely correlation of default between this issue and other issues that might be in your portfolio.

I think that ratings are still very important and useful information for corporate issuers and traditional structures like mortgage-backed securities. Where the agencies let themselves down was in rating more complex, leveraged structures like CDO's and the like. In those situations the rating - often AAA - turned out to be based upon assumptions that did not play out, but which weren't sufficiently tested nor made clear. But their processes for rating the default risk of companies and mortgages has stood the test of almost a century of use. And when you look back over 10 or 20 years, you will see that the universe that was rated at a certain level has defaulted at pretty close to the % implied by the rating at the start of the period.

Ashley
August 04, 2016

Why do people still take credit ratings seriously? Recall that Berkshire Hathaway (BH) profited handsomely from Moody’s robo-ratings in the 2000s credit boom (BH was Moody’s largest shareholder). When questioned all Buffett could say was “Investors, government and rating agencies learned exactly nothing from the manufactured-home debacle. Instead, in an eerie rerun of that disaster, the same mistakes were repeated with conventional homes in the 2004-07 period." BH sold their stake in Moody’s after the crash when there was no more river of gold in ratings. Don’t follow credit ratings – follow the Buffett money trail instead.

Warren Bird
August 04, 2016

Ashley, you aren't listening. Credit ratings are an input to decision making about corporate bonds, but not the full story. I wouldn't invest in a corporate bond fund that ignored default risk and credit ratings are an assessment of that. By all means take a different view on a specific risk rating if you wish, but that is something completely different.

In any case, what Buffett does with his concentrated equity portfolio investments is completely irrelevant to the usefulness or otherwise of credit ratings.


Leave a Comment:

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.