Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 84

Currency winners and losers

When the Hawke Government came into power in 1983 one of its first decisions was to float the Australian dollar (AUD), assuming that this action would cause the AUD to fall and improve our international competitiveness. Before 1983, the value of the AUD had been set each day by the Reserve Bank of Australia (RBA) and the Federal Government. Since then, rises in the Australian dollar are often presented in the press as a vote of confidence in Australia as a nation. A falling Australian dollar is viewed as a negative event, raising the cost of online purchases, imported flat screen TVs and skiing holidays in Colorado.

Since 30 June 2014, the AUD has fallen 7% against the USD, as the ‘carry trade’ (borrow cheaply in USD and invest the proceeds in higher yielding AUD securities) quickly unwound and foreign speculators fled back to USD. The AUD was sold off more than almost every other developed and emerging market currency, just like it was in the May-June 2013 ‘QE taper’ scare and also in the 2008-2009 GFC. Whilst this move is negative for a government wanting to buy F-35 Joint Strike Fighter jets, the falling AUD can help investors, as both asset allocation into unhedged international equities and Australian equity portfolios can be designed to benefit from a falling AUD.
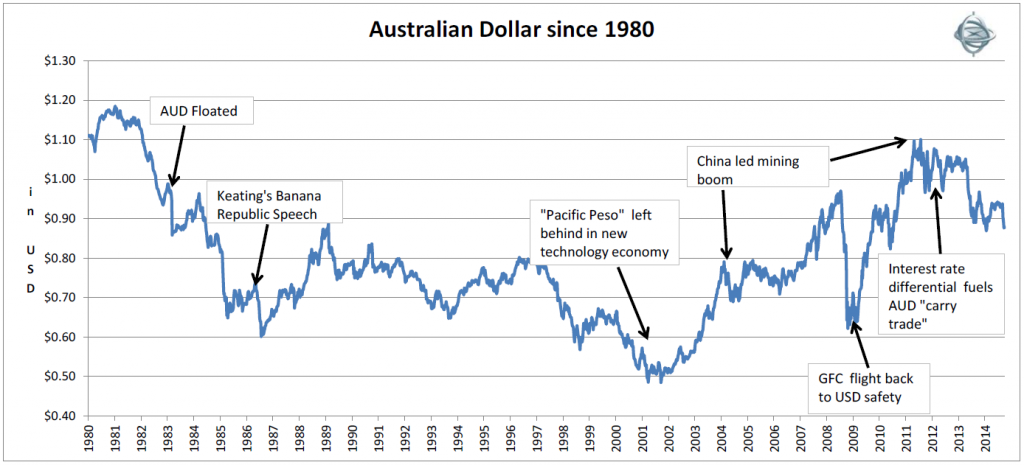
Since floating, the AUD/USD has averaged 76 cents, however as one can see from the above chart the AUD was in a downward trajectory from 1983 to 2002. This was broadly due to Australia’s higher relative inflation rate. The strength in the AUD over the past 10 years has been a result of China’s industrialisation and its associated unprecedented explosion in demand for Australian minerals since China joined the World Trade Organization in 2001. As the impact of this one-off event diminishes, we would expect the AUD to move towards fair value based on purchasing power parity, which we estimate is approximately USD66 cents.

Winners

Broadly speaking the companies that are likely to benefit from a weaker AUD fall into four categories:

  • Companies that manufacture or provide a service in Australia and compete with the now more expensive imports such as steel (BlueScope), fertiliser (Incitec Pivot) or tourism (Crown).
  • When a falling AUD results in inflation, companies like Woolworths and Transurban should see an expanding profit margin. Their product prices from cans of tuna to road tolls will increase with inflation, whilst a proportion of these companies’ costs remain fixed, thus resulting in higher profits.
  • Companies that have production costs in AUD but export products like natural gas (Woodside) and iron ore (Rio Tinto) which are priced in USD. A falling AUD translates into higher AUD revenue from the same USD level of goods sold. For example, every 1c fall in the AUD increases BHP’s profit by USD100 million and Rio by USD57 million.
  • The falling AUD also benefits companies with substantial offshore operations such as CSL and Orica, as their USD- or Euro-denominated earnings when translated back into AUD for Australian investors are now worth more.

Losers

The companies that are typically hurt by a falling AUD are those that buy goods offshore for resale to Australian consumers such as retailers Myer and JB Hi-Fi. Over the last 12 months, the 8% fall in the AUD/Korean Won effectively results in a price increase for that new 140cm Samsung LED TV that some may have their eyes on for the upcoming Cricket World Cup.

Similarly, a falling AUD presents a challenge for companies like Qantas that earn revenue in AUD from domestic consumers, but have significant USD-denominated costs such as aviation gas. Further companies that have significant un-hedged USD borrowings such as Boral will see their interest costs increase, especially when the company does not have USD earnings to service their debt. For example Boral’s US building materials businesses last generated a profit in 2007.

How to position a portfolio

Investors who view the AUD as overvalued on fundamentals can position both Australian equity portfolios and unhedged global equity portfolios to benefit from a falling AUD. Favoured companies might be those with significant offshore earnings and strong franchises (CSL, Orica or Sonic Healthcare), rather than structurally-challenged companies that need a declining AUD to compete with imports (BlueScope Steel or CSR). Additionally, mining and energy holdings such as BHP, Rio Tinto and Woodside will benefit from a rising price per tonne of ore or a barrel of oil sold in AUD terms.


Hugh Dive is Head of Listed Securities at Philo Capital Advisors. These comments are general in nature and readers should seek their own professional advice before making any financial decisions.


  •   16 October 2014
  •      
  •   


Leave a Comment:

RELATED ARTICLES

The Aussie dollar was floated 40 years ago

The currency bet you didn’t know you made

Clime time: Trump's US dollar assault is fuelling CBA's rise

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.