Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 481

Five long-term investing lessons from working with Phil Ruthven

Phil Ruthven’s contribution as one of the nation’s foremost business commentators and forecasters has been acknowledged in this and many other publications. I worked with Phil in the 1980s and 1990s and it was the research techniques and models for business and strategic analysis he pioneered that led me to change careers and move into investment management.

In the interest of investor education and for the long-term investors out there with a Buffett-style investment philosophy, here are a few things Phil taught me that helped make me a better long-term investor.

Lesson 1. Follow the money

One of Phil’s more famous charts illustrates the changing structure of the economy over the past two centuries as we moved from the agricultural age when our primary industries dominated wealth creation through to the industrial age where secondary industries and particularly manufacturing were the major wealth creators. Now into the information or digital age, it is the quaternary (information industries) and quinary industries (service industries) that are winning share of the earnings pie.

Industry Division: Changing Importance
Australia, shares of GDP by industry division, 1800–2050
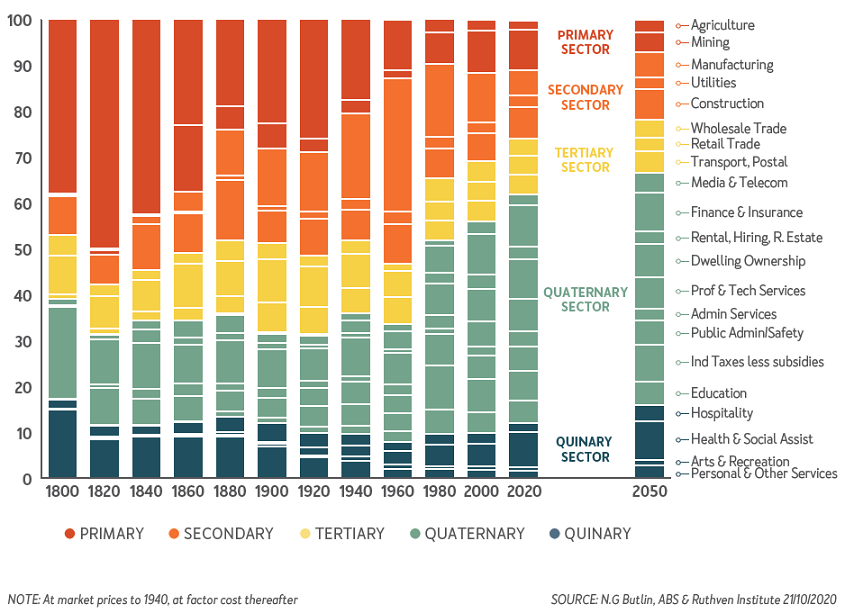
Intuitively, I use this backdrop as an input into portfolio construction where my preference is to skew the portfolio towards companies in industries that are increasing their share of the earnings pie. This is not to say there are not some wonderful Australian and international companies in mature industries that continue to grow and deliver excellent returns by winning market share. There are. But at the portfolio level, my tilt is toward companies well positioned (see lesson 4) in this change.

Lesson 2. Understand a company’s competitive operating environment

Critical to long-term stock outperformance is understanding the industry in which a company operates and its competitive operating environment. We cannot begin to think about the potential size of the opportunity set and threats facing any company without this. To quote the great business strategist, Peter Drucker, the first question to answer is: what business are you in?

This is not as easy as it sounds, and it is made harder by the GICS classification system which often classifies companies according to the markets they serve rather than what business they are in. This often leads to muddled thinking and flawed analysis.

How often have we read that we should invest in internet companies with the usual list of names such as Uber, Amazon, and Netflix. There is no internet industry as such. Uber is in the taxi and ride-sharing industry, Amazon is in the department store industry and Netflix is in the broadcasting industry.

All these companies represent new disruptive technologies in these industries. The IBIS industry database is based on the official Standard Industrial Classification system (SIC) used by statistical agencies the world over to define industries and with a few exceptions is a good place to start when defining and analysing a company’s competitive operating environment. It is also where you can get official statistics on the size of the industry when quantifying the size of the opportunity set and the positioning and market share of industry participants.

Lesson 3. Know the development phase of the industry in which the company operates

Michael Porter, another famous business strategist, stressed the importance of knowing the development phase (i.e. pioneering, growth, maturity, decline) of the industry in which a company resides. While some long-term investors acknowledge its importance when assessing the short, medium, and long-term outlook for earnings, few to my knowledge have come up with a methodology to determine it. Phil did, using the industry’s value added as a share of the value added of the total economy, (i.e. our Gross Domestic Product) and tracking it over time.

Again, I find this a powerful valuation tool when thinking about the longevity and future growth of the earnings stream of any company. The average industry cycle is around 35-40 years with each new cycle characterised by a new disruptive/transformational technology or system. This is the average, but some are much longer, and some much shorter. Think of the motor vehicle manufacturing industry where the basic technology and systems has changed little since the first model-T Ford rolled off the production line over 100 years ago. The motor vehicle industry peaked as share of the economy and business earnings in the late 1960s and after declining relative to the total market for 50 years is now clearly back into a new cycle pioneered by electric vehicles and the likes of Tesla. Compare this to the television broadcasting industry where the cycle length is much shorter with new cycles around colour TV, pay TV and now streaming all in living memory.

Lesson 4. Understand a company’s position within its industry

Years of research by Phil confirmed that there are only two sustainable positions within an industry that can deliver long-term outperformance.

A company must be either a major player with significant cost and scale advantages or a niche player usually focusing on one product group within an industry. Caught-in-the-middle players rarely outperform or survive over the long term. My observation over many years is niche players often have stronger and more sustainable competitive advantages than the industry majors and therefore can be one of the best hunting grounds for companies delivering superior long-term outperformance. This is particularly true where one or two players dominate a niche globally. Australia is blessed with some outstanding niche players across a range of industries. Examples include pharmaceutical manufacturing (CSL in blood products), medical device manufacturing (Cochlear and ResMed) and internet publishing and broadcasting (Carsales, REA, and Seek).

Lesson 5. Learn from history

Applicable in life and investing, Phil was renowned for his long-term charts and time series on the macro business environments and individual industries. Tracking the economy from the macro to the micro often enabled Phil to see linkages and trends well before anyone else. This alone is a very valuable investing tool, but for me even more valuable is using history as an input into weighting risk when valuing a company. It is the risks you can’t measure that can often hurt you the most.

Studying the history of any industry, the key drivers of every cycle and the changing composition and market share of participants is always valuable in weighting risk at both the industry and company level.

Thank you, Phil.


Jennifer Mead worked with Phil Ruthven in the 1980s and 1990s before changing careers and moving into investment management.

Firstlinks’ archive of Phil Ruthven’s contributions can be viewed here.


  •   26 October 2022
  • 11
  •      
  •   
11 Comments
Dr David Arelette PhD
October 26, 2022

Item 2 shows the first and most revealing commercial question in the universe - what business are you in? I use this in Masters degree teaching, which business is a University in? No not education, you buy a ticket (the value depends on your learning and that is shown in your grades) for the next 10 years of progress in your life - the ticket expires soon enough then it's a top up UG, degree, the MBA then the PhD - that was part of my ticket collecting. Knowing what business you are really in makes sense of Five Forces and how to compete in your actual industry.

Jennifer Mead
October 29, 2022

Not understanding the business, the competitive operating environment and Porters five forces is one of the main reasons in my view why so many investors underperform the market over the long term.

David Owen
October 26, 2022

Great guidelines, however, how does the average person gather that information, identify the relevant stocks and then act in a timely, objective and unbiased manner?

Jennifer Mead
October 29, 2022

It is difficult even for professional investors. Probably better to think about your own investment philosophy and risk profile and if it is long term and similar to a Buffett or Terry Smith then possibly find a fund manager with a similar philosopy and most importantly a track record over at least a couple of decades or alternatively go the passive route. See previous comment.

Roderick Russell
October 26, 2022

Every pundit is saying we are going back to the stagflation period of the 1970's. You can inform yourself about the economic conditions from books archived magazines etc. But the investing milieu / social context are important perhaps more important if you rate behavioural finance in your analysis. 

Jennifer Mead
October 29, 2022

Behavioural finance is one of the many disciplines you need to apply to be a successful long term investor. I tend to use this to take some money out of the market when it is significantly overvalued and buy back in when it is trading at or below fair value. Be greedy when others are fearful as Buffett famously once said but history shows you should stay invested in the market no matter which way the economic winds are blowing.

ian
October 27, 2022

2020 shows mining as relatively small % of gdp? is this correct given our iron and commodities generating windfall profits?

Jennifer Mead
October 29, 2022

I sourced the chart from the Ruthven Institute but I agree mining does look a little light on in 2020. Mining as a share of the economy is currently running at 13-14% its highest share in well over a century (and a much higher share of corporate profits) as you say from the higher for longer commodity prices

Michael Sandy
October 28, 2022

Given the identified complexities, am presuming the late Phil Ruthven would not have been averse to passive investing for the average investor?

Jennifer Mead
October 29, 2022

Successful long term investing requires the application of many disciplines across both the quantitative and qualitative and in my view this is why the majority of fund managers do not outperform over the long term. This does present a strong case for passive investing for the average investor.

Kevin
October 29, 2022

Yes,it may have seen Phil that said very important that companies survive,most of them don't.Starting in the late 1980s after the crash for me the growth is phenomenal ,using a bit of leverage. Fast forward to 2000 and AXJOA on 30/6/00 was 15138 ( source Renton,Understanding the stock exchange 4th edition Aug 2004 ),now 81000?. Time in the market and compounding are great.He gives average wages quarterly going back to 1972.The wages for 30/6/00 were $41,000 rounded . For $41K in 2000 that got you 1000 shares each in CBA and NAB,I owned both of them then and still do.See what AXJOA is in 2040 and using the DRP in NAB and CBA should produce between 7 to 8000 shares in each of them. By 2040 the leverage of between $40 - 45K by buying 3x the index or the companies mentioned should outperform the $ cost averaging of super,and the 9% and up for 40 years.Throw in whatever super is worth in 2040 and happy retirement. Simple,but not easy to quote Buffett.I don't like quotes,they can be adjusted and taken out of context for every occasion I'll have to have a look at that Ruthven institute,thanks


Leave a Comment:

RELATED ARTICLES

Why August company reporting season was poor

Winners and losers in sharemarkets, 2017/18

The market paid for change, not comfort

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.