Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 430

Many people misunderstand what life expectancy means

The New York Times headline screamed 'US Life Expectancy Plunged In 2020' on 21 July 2021. The sub-headline continued: “The 18-month drop, the steepest decline since World War II, was fueled by the coronavirus pandemic.” Specifically, life expectancy was reported to have declined from 78.8 years to 77.3 years.
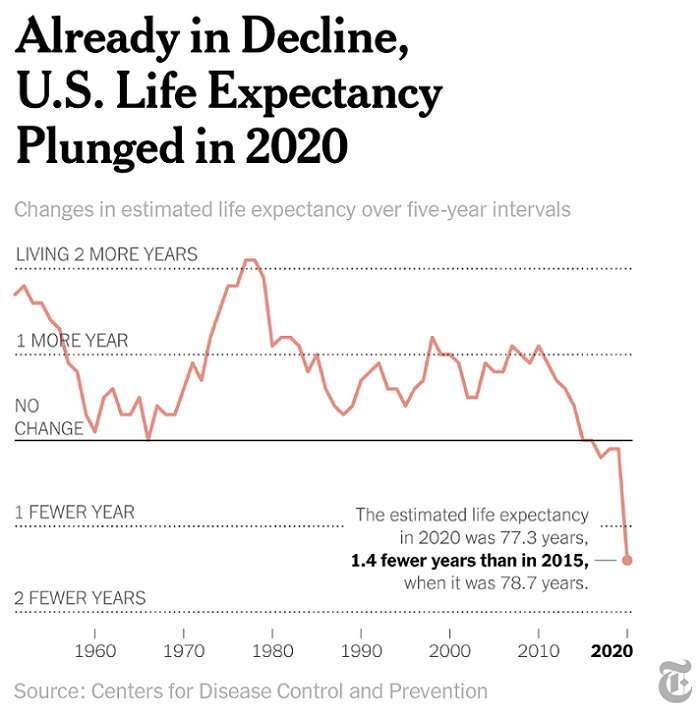
This is such a big deal that The Times (of London) also headlined it: “Life expectancy gets even shorter for Americans.” They added that “Covid-19 was blamed for three quarters of the decline.”

What does the headline even mean?

Really? So all Americans expect to die a year and a half earlier than before (on average, of course)? That’s what the headlines mean, right?

No, not really, but the truth doesn’t make for as dramatic a headline. And if you can get an attention-grabbing headline, who cares if it isn’t accurate?

The true meaning of the statistics was, actually, reported accurately later in the New York Times article:

“If American children born today spent their entire lives under the conditions of 2020, they would live an average of 77.3 years, down from 78.8 in 2019.”

See the difference? If Covid-19 stays around in as virulent a form as in 2020, with no vaccinations or other defences against it, then … yes, future life expectancy will indeed fall.

I went to the actual report from the (US) National Center for Health Statistics (a part of the Centers for Disease Control and Prevention), and it was very clear:

“The period life table does not represent the mortality experience of an actual birth cohort but rather presents what would happen to a hypothetical cohort if it experienced throughout its entire life the mortality conditions of a particular period.”

Which is jargon for what I said in the previous paragraph.

A misunderstanding of life expectancy 

Why does this bother me? Because people misunderstand what life expectancy means. I’d greatly prefer it if it were instead called ‘the average survival age’, trying to avoid the macabre feelings that anything involving death can create. And what’s a ‘cohort’ anyway?

Let me explain.

A cohort is a group of people with a specific characteristic in common. When dealing with longevity, cohorts are usually defined by age and gender. For example, 'all female children born in 1970' or 'all males now aged 55' – that sort of thing.

‘Life expectancy’ means the average expected age to which members of the cohort in question will survive. ‘Expected’? There’s nothing expected about it. It’s a jargon word that means it’s the average of a distribution (perhaps even a very wide distribution) of possibilities.

For example … What does it mean if the life expectancy for people of your gender and year of birth is stated to be 80 years? It means that, if you look at all the people in that cohort (your gender, your year of birth), they will have a wide range of ages to which they will survive, and roughly half are expected to survive to some age short of 80 and roughly half to some age beyond 80.

That’s interesting, because the number is often (wrongly) interpreted as the expected limit of life, as if (in that example) 80 is the maximum age any of that group can be expected to reach. No, it’s not the maximum: it’s the average. There’s a 50/50 chance of outliving it.

It's higher for older people

Now here’s something that is even more often misunderstood. Suppose we subdivide that original group and now include only those who are still alive at age 50. What’s their likely average survival age? Is it still 80? No, it’s bound to be higher than 80. That’s because some of the original group have already passed on, before age 50. They brought the average down. The average for the group of survivors is therefore higher than 80. It might, for example, be 83.

That’s right, the definition of the cohort, the group, has changed. It’s no longer all of those who were born in your year of birth. It’s now limited to those who have survived beyond age 50. That’s a different group, even if the members of the (smaller) ‘survived to 50’ group were also part of the original ‘born in the same year as you’ group.

It’s like starting with ‘all people in the world’ and then changing to ‘all females’: the second group is different from the first one, even though all members of the (smaller) second group are also part of the first group. That’s a subtle distinction that the vast majority of people are unaware of. 

Similarly, those who survive beyond age 60 have an average projected survival age even higher. And so on. The older you are, the higher the average projected survival age.

One final rant on the way this ‘life expectancy’ was calculated. You’d think, since it deals with future survival, that it would reflect the possibility of improvement in health, the sort of trend that we’ve been used to for a couple of centuries. Of course you can never get it right, because it would require a crystal ball. And, to put it mildly, that’s impossible to find.

But what they’ve found isn’t a crystal ball, it’s a rear-view mirror, and indeed it only shows the immediate past.

Which brings us back to the headline.

There are potentially three aspects of it that are capable of misinterpretation.

First, the numbers only apply if Covid-19 (with no vaccination) and all other mortality-related conditions (including, for example, the opioid crisis) prevail forever.

Second, even when adjusted to reflect a probably more-promising future, the numbers don’t reflect the maximum age one can reach. Roughly half of us should outlive the stated expectancies.

And third, they apply only to newborns. The longer we survive, the higher the average age to which we will eventually survive. It's common sense when it’s expressed that way, isn’t it?

There! Even with such a morbid subject, I bring you nothing but good news!


Don Ezra, now happily retired, is the former Co-Chairman of global consulting for Russell Investments worldwide, and the author of “Life Two: how to get to and enjoy what used to be called retirement”. This article is general information and does not consider the circumstances of any investor.


  •   20 October 2021
  • 10
  •      
  •   
10 Comments
Steve
October 20, 2021

Fair points Don, but I could also say some people misunderstand the difference between average and median. One thing that this raises is should financial advisors and the financial industry in general use the life expectancy of that cohort that has reached say age 60 as a guide to how long their funds are expected to last in retirement? You would need to allow for another few years over and above the nominal whole population life expectancy. Most retirement calculators use the latter I believe.

Brnic
October 20, 2021

I wonder how the (very generalised) financial advisor community will react to these statistics? Will they update their deterministic projection calculations to show their clients that they can start spending more because they now need to provide for 1-2 years’ less income?! Are all their clients going to suddenly live a couple of years less…? Mind boggling…

ALLAN
October 21, 2021

"[...] Are all their clients going to suddenly live a couple of years less? Mind boggling..."

It's not "mind boggling" if looked at correctly. Whilst one can suddenly 'die', one cannot suddenly 'live' a couple of years less. QED

Jack
October 20, 2021

If you are lucky, or unlucky enough, to be in the last 5% of your cohort to survive, neither the average nor the median life expectancy is of much use to you. The problem is that you cannot know the future, but you have to assume there is a 5% chance that you might live to age 95 or more. Planning for your savings to expire at your life expectancy is inherently dangerous for 50% of the population! But why worry, there is always the age pension.

Geoff
October 20, 2021

Super calculators which spit out your life expectancy are particularly worrying as it's not immediately clear what it means. What I really want to know is what is the life expectancy of people who are the same age as I am, having survived thus far, not the ones that are already dead. That's useful info, and I still have a 50% chance of outliving it... but is that what I'm getting? Who knows...

Craig KELLET
October 20, 2021

Well, if you go to the ABS life tables - that is exactly what they do - give you the expected (average) life expectancy you have, for a given age and by sex. https://www.abs.gov.au/statistics/people/population/life-tables/2017-2019#data-download

Ramani
October 20, 2021

A boss of mine , an actuary like me, used to say ‘Obfuscation is a tool of every profession’. Demographers and death counting actuaries are no different.

The need to rework the conditional survival age (having survived a few years) explains the apparent inequity of an older human from the cohort enjoying a higher life expectancy. So the trick is to cheat death for a while, and on an average the Reaper will surely look grimmer.

Await an article soon why life insurers assume, for the same cohort, higher survival rates for annuitants but lower ones for the life assurance proponents. Bid and offer pricing really, suitably obfuscated.

Kindred professions are no better. Think of accounting and legal fictions that bamboozle the consumer!

Craig KELLET
October 20, 2021

One of my favourite sayings is "eschew obfuscation".

Sonja
October 23, 2021

As with a lot of statistics, the trend is more important than the actual number. Rising survival rates are associated with improving living conditions: health care, wages, road safety, etc. The opposite applies to falling survival rates and says a lot about living conditions in the US in 2020 and before.

Dan Pimental
October 26, 2021

Most people misunderstand life expectancy data. Life expectancy is the average. In societies with high infant mortality rates many people die in the first few years of life.


Leave a Comment:

RELATED ARTICLES

How not to run out of money in retirement

How long will you live?

Will you run out of money in retirement?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.