Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 590

How this GDP per capita recession compares to history

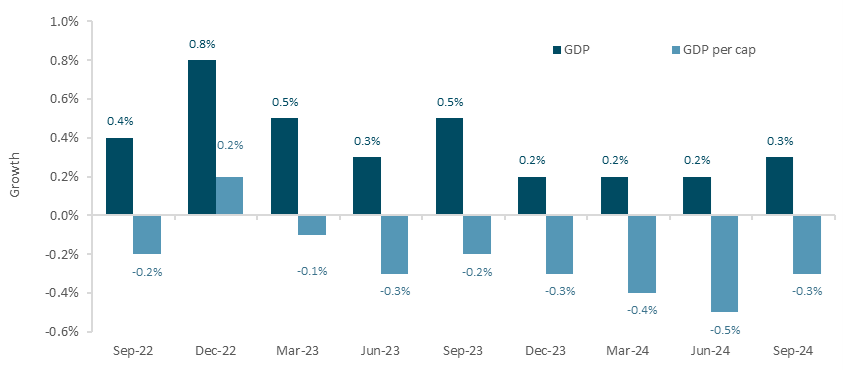
GDP was 0.3% for the September quarter and while headlines highlight that this is 0.1% below expectations, the true story is that this was Australia’s seventh[1] consecutive quarter of negative GDP per capita growth.

This is the longest period of consecutive negative GDP per capita growth since records started in June 1973. Since that time, Australia has only recorded one other period of more than two consecutive negative quarters, and that was four negative quarters from September 1982 to June 1983.

Immigration: continuing the GDP free kick, but for how long?

A major flaw in the GDP measure that especially affects Australia is the free kick provided by population growth, which, in Australia’s case, means immigration.

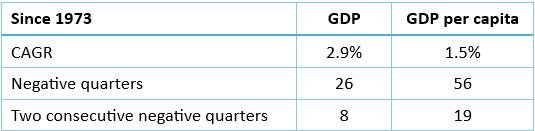
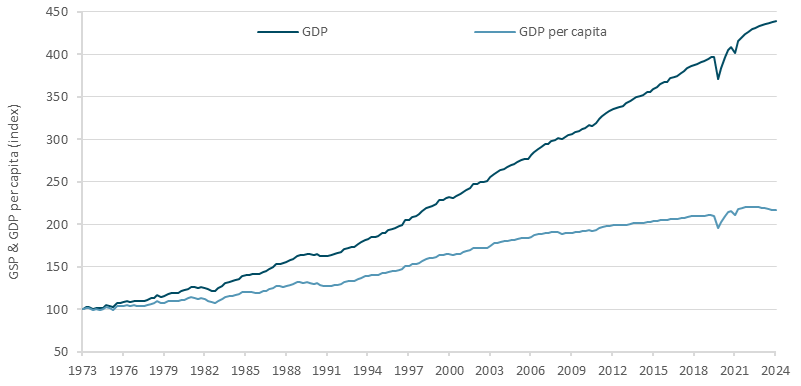
Looking back 50 years to 1973 (when the per-capita series starts), population growth has provided nearly 50% of the GDP growth, with GDP growing at a 2.9% compound average rate, compared to GDP per capita, which has averaged 1.5%.

GDP per capita has had double the negative quarters

Table 1 shows a similar pattern regarding the number of negative quarters and recessions (defined as two consecutive quarters or negative growth). Since September 1973, GDP per capita has registered 56 negative quarters compared to GDP, which recorded only 26. Similarly, GDP has recorded only eight consecutive negative quarters compared to 19 for GDP per capita.

Table 1: Population growth has delivered almost half the total GDP growth
Source: ABS, Venn Brown

Immigration is the magic lever to which governments (of all colours) have become addicted in order to boost GDP (and housing prices). If GDP looks to be slowing, just let a few hundred thousand more people into the country and watch the GDP grow.

There has been some speculation that the growing discontent with the ongoing housing crisis and cost of living pressures might see the end or at least the easing of this policy.

However, no politician wants to be the one that ushers in a GDP-measured recession or, worse still, a meaningful decline in house prices. As such, we don’t see a major change in immigration in the near term.

Figure 1: Population growth is responsible for almost half the total GDP growth
Source: ABS, Venn Brown

While all the talk is on the cost of living and inflationary pressures, it’s worth noting that while the government has been proudly reporting unbroken economic growth, GDP has been negative for eight of the last nine quarters on a per capita basis.

As mentioned above, this is only the second time since June 1973 that there have been more than two consecutive quarters of contraction; the other lasted four quarters from September 1982 to June 1983.

Figure 2: GDP per capita has been negative for just eight of the last nine quarters
Source: ABS, Venn Brown

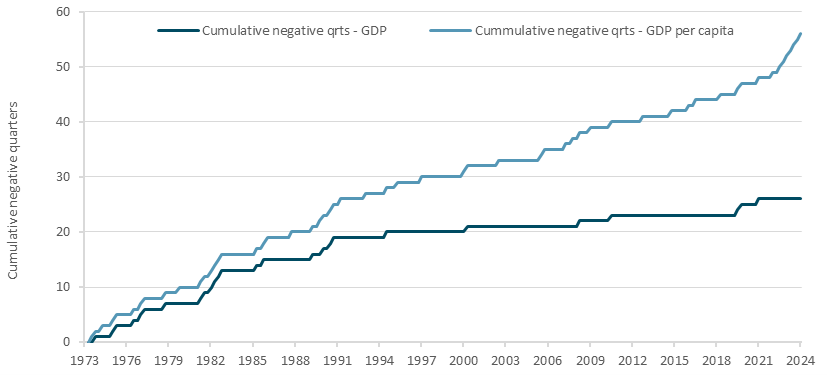
Figure 3 below shows the cumulative number of negative quarters of GDP and GDP per capita, highlighting the separation of the two measures as immigration increased in the early 90s and gained real speed over the last three years.

Figure 3: GDP per capita has been negative for just eight of the last nine quarters
Source: ABS, Venn Brown

The 1990/91 recession was shorter but far more intense

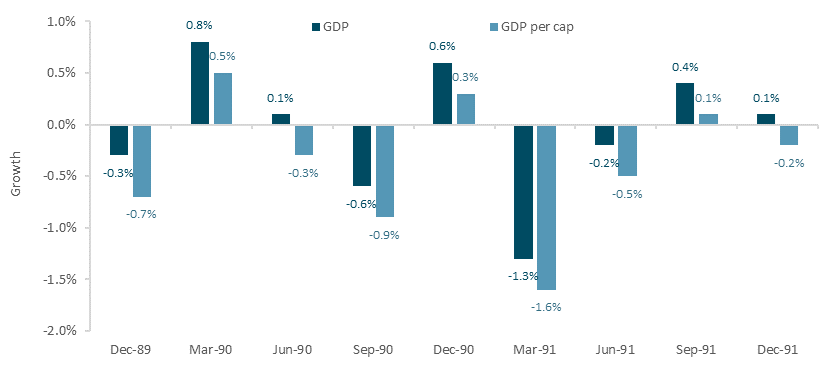
An interesting reference for the current period is the 1990/91 recession (see Figure 4), during which per capita GDP was negative for six of nine quarters, compared to GDP, which was negative for four of the nine.

That’s not to say we’re even close to a similar economic downturn. Back in 1990/91, there were three key differences to our current environment, the most important of which is unemployment:

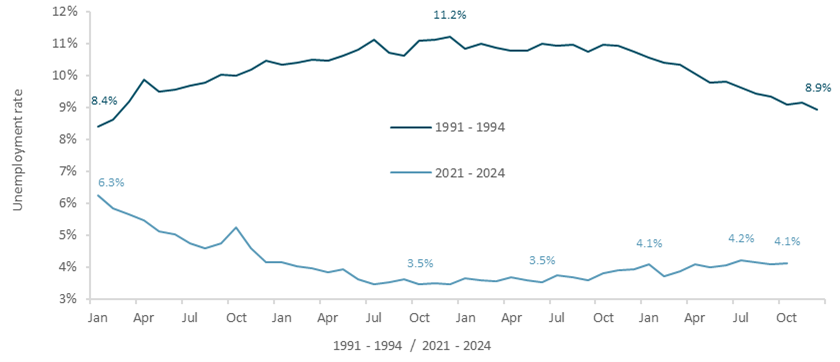
  1. Unemployment: Seasonally adjusted unemployment peaked at 11.2% in December 1992, compared to today’s persistent, near-record low of 4.1% in October (albeit up from 3.5% in October – December 2022). See Figure 5;
  2. Negative GDP: Actual GDP was negative for three quarters, bottoming with a -1.3% contraction in March 1991; and
  3. Magnitude: At the bottom, the magnitude of the negative GDP per capita was double to triple the current levels.

Figure 4: 1990/91 recession had six out of nine negative quarters of per capita GDP
Source: ABS, Venn Brown

Unemployment remains the key factor to watch

While seasonally adjusted unemployment is up 0.7 percentage points from its low of 3.5% in December 2022, it remains near record lows and less than half the rate that resulted from the 1991/1992 recession.

Unemployment and credit defaults remain the key indicators to watch as GDP continues to slow, interest rates remain moderate, and inflation continues to add to cost of living pressures.

Figure 5: Unemployment in 1991 – 1994 was very different to current rates
Source: ABS, Venn Brown


[1] GDP per capita for the March 2023 quarter was revised down from 0% to -0.1% in the September release.


Andrew Wilkinson is the Managing Director of Venn Brown, a special issuer sponsored equity research company.


  •   11 December 2024
  • 6
  •      
  •   
6 Comments
Paul R
December 13, 2024

When housing is 4x bigger than the economy, and there's almost zero real value added in it from an economic point of view, it's hardly surprising that GDP is suffering.

Shrink housing and get investment to flow to the right growth areas. Just don't ask our politicians because they simply don't understand.

Jess
December 15, 2024

Job creation was driven by government spending, so take that out and immigration, and you will have a much clearer story of the real experience in our economy. What's disappointing is how easily the numbers are manipulated.

Trevor
December 15, 2024

Australia suffers from bad government. I understand that’s largely what caused Argentina to go from being a rich country to a poor country.

Now we’ve got an election coming up with one side seemingly believing that a modern economy like Australia can run on intermittent renewable energy and the other side going to the other extreme of nuclear. Both policies aimed at reaching net zero in the name of climate alarmism.

If we end up with a minority labor government in coalition with the greens then we’ll really be up the creek.

I’m not saying the liberals are much good either. They really let us down closing the economy and then running up the debt during covid. And they’re supposed to be the good economic managers.

Jeff Oughton
December 16, 2024

What's Australia's national objectives?
What's the Government's and business promise(s) to Australians?
It's not solely, simply GDP...GDP per capita...flows of income/production.....and population/ employment.....incomes/profits/dividends...after inflation

It's should be about - broader measures of wealth - viz including human capital (education and health), natural capital (mineral resources, renewable resources, ecosystems, water) and social capital (good governance, civic-mindedness).

And without the right objectives & good governance from both government and business, Australian well being fall's well short of its potential.....indeed, in real terms, living and well being may well continue to decline in real terms

Steve
December 16, 2024

Whats the old saying, in a democracy you get the government you deserve. I think there are two simplistic options, either excessive demand is taken out by some people losing their jobs while the rest get a good pay rise (the 70's) or the pain is shared, everyone who wants a job can get one but the pay rises are lower. The second option may be fairer (morally) but it alienates more voters; voters are largely amoral when it comes to home economics. We seem to have lost touch with the reality that to pay our way someone, somewhere needs to make or produce something that someone else will pay for. If we want to import cars, TV's, mobile phones etc (none of which we make here) we need to sell something to produce the cash to pay for the goodies. The devil in the detail is we need to actually be competitive with alternative suppliers of said goods/services which is where productivity enters the conversation. When our productivity declines (ie cost/unit produced goes up) we lose some business and the economy shrinks a bit. Unfortunately the Labor govt don't get this connection and would love to stop selling dirty coal/gas/iron ore/gold/live sheep etc but then won't have the taxes to pay for the luxuries only a first world country can afford like the NDIS etc (or even basic like decent hospitals). So long as most jobs "created" are either direct public servants or indirect service providers paid by the govt we are in for a hard landing one day. Did someone mention Argentina?

JB
December 20, 2024

Why everyone complains but nobody can see the elephant in the room? 26% of Australians work in the government or semi-government sector! Overgrown beurocracy, miriad of rules and regulations otherwise called the red tape has been suffocating Australian small business and depriving enterprenurial individuals of their chance of success and their dreams for decades. Add to that monopolies, duopolies and oligopolies deep rooted in the economic system due to government complicency and corruption. They long destroyed healthy competition being a sole guarantor of rising standards of living. Lack of competition extends to the political arena where no matter who you vote for, they are the guardians of the system that benefits them but not the public. It is time, Australians to wake up and Fight Back for a real change!


Leave a Comment:

RELATED ARTICLES

Ignore the noise, long-term investors will be well rewarded

Central banks need higher inflation targets

Population and ageing nonsense … again

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.