Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 86

Tim Hodgson: how a profession became an industry

Tim Hodgson has probably spent as much time as anyone in the last decade thinking and writing about investing and funds management, and his conclusions are far from flattering. With Roger Urwin, Tim set up the Thinking Ahead Group at Towers Watson in 2002, and this recently morphed into the Thinking Ahead Institute, a not-for-profit ideas forum with external sponsors that has already attracted 20 major institutions managing US$5.6 trillion in assets.

A couple of months ago, I was at the Research Affiliates conference with Tim in Los Angeles where some of the best minds in the industry, including Nobel Laureates, spent two days discussing how little we knew about markets. How do we value stocks? What value do asset consultants add? Why bother with the fees for active management? Tim presented at the Conference and shared these concerns.

I sat down for a chat with him in Sydney last week. He has not worked as a consultant at Towers Watson for many years, and he brings his ideas to his colleagues and their clients by writing research papers and making presentations.

I asked him what happens when one of his opinions, such as the merits of ‘smart beta’ rather than active management, is not in the best interests of a Towers Watson client. “If you do the right thing, it will have relevance,” he replied.

Alpha is a negative sum game

He argues an articulation of beliefs by a client or investor is the first step in the investment process. For example, it is a truism that ‘alpha is a negative sum game’. That is, the sum of all investment decisions is the market, and after fees, the active performance (the alpha) must be negative. But there are many managers both above and below the market benchmark. One belief might be that it is possible to identify the better managers, while another belief might be that outperformance cannot be done consistently over time.

Hodgson falls in the camp that identifying the best managers is very difficult, and we probably spend far too much time searching for outperformance. It’s no use recognising Warren Buffett’s skill now, you need to identify the Warren Buffett of the next 20 years. He advocates moving away from the majority allocation to active managers to perhaps 70% in various types of passive management. The market still needs active managers for efficient price discovery, but it does not need to pay the fees for so many active relative value managers.

Passive does not necessarily mean the usual cap-weighted index investing. Hodgson was an early supporter of what is now known as ‘smart beta’ but which he called ‘beta prime’ in research papers going back a decade. He supports the view that cap weighting leads to larger allocations to the most expensive stocks, and an index which weights by factors other than price can remove this drag. How have his colleagues taken this view? “It’s my job to initiate ideas. It can sometimes take a long time for them to be appreciated.” Such a move across the industry would remove over $100 billion of management fees from the estimated $350 billion paid globally at the moment, not something which many in the industry would enjoy. It will only happen through bottom-up change from asset owners, who control the mandates they offer.

Risk as permanent impairment of goals

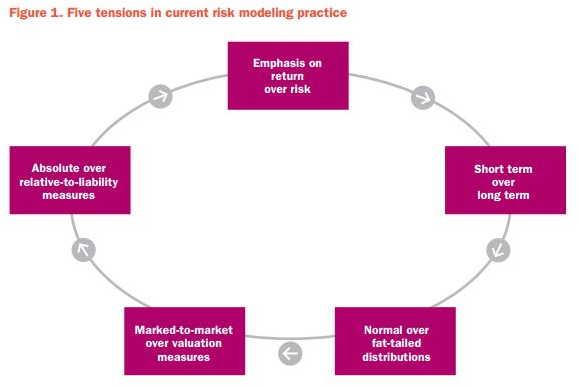
Hodgson defines risk as “a permanent impairment of mission goals or expectations”. He believes risk models struggle in the five ways described in Figure 1. Risk management needs to find a way to overcome these tensions as investors go on a ‘journey plan’ through their lifetime. Funds should be more concerned about impacts that impair long term plans than short term Value at Risk measures or tracking errors.
He supports dynamic or tactical asset allocation, using valuation techniques that measure when markets are expensive or cheap. When I suggested it seems inconsistent to say you cannot pick good active managers but you can pick when markets are cheap, he quoted from F. Scott Fitzgerald in 1936:

“The test of a first rate intelligence is the ability to hold two opposed ideas in the mind at the same time, and still retain the ability to function.”

He drew out the comparison to active versus passive investing in a fascinating way. “‘Is there aggregate added value from market timing’ is a similar question to ‘Is there aggregate added value from active investing’. Probably no to both, but we are dealing with highly complex, adaptive systems, and the answers are not simple. Which is why we always start with our beliefs.”

In other words, investing is not like practicing medicine, where an experienced surgeon can become an expert over time because the human body does not change and he knows what to expect when he goes into it. Markets change depending on the actions of others in a highly adaptive way.

We have morphed from a profession to an industry

The Thinking Ahead Group has long championed the need to focus on the ultimate beneficiary, and Hodgson riles against the self-interest of many finance executives. His colleague, Roger Unwin, has seen investment management morph from a profession to an industry. There used to be more focus on stewardship and long term perspectives.

One of his hopes for the new Institute is that by changing behaviour at the top of the investment pyramid among major asset owners, it will improve retail products and client interactions. He likes the analogy of a Formula 1 car and the research impact on the family sedan. “By having better working partnerships, we hope the investing equivalents of antilock brakes and airbags trickle down from the Institute to the end investor.”

(To read some of Tim’s most recent work on the attitudes of investment managers, see the related Cuffelinks article, “Our industry has a problem”).


  •   31 October 2014
  • 2
  •      
  •   
2 Comments
Paul
November 01, 2014

It's rather ironic that the entire industry is built around a caveat (past performance is not an indication of future returns) and yet this is precisely the pitch (purported) alpha providers use.
Too many reports (analytical and behavioural) such as SPIVA/ Persistence Indices/"Hot hand" fallacies show that over the long term, it's far too hard to consistently pick longer term winners- particularly those that don't "give it back" with a poor performance, yet an entire (sub) industry is built around it. Little wonder the results of the TW survey around who is deemed the major beneficiary of the industry.

Ramani
November 01, 2014

Paul, the irony of trumpeting past performance selectively (only in good years, mind) while hoping that this will be ignored is only bettered by the inveterate use of 'this does not take account of your circumstances, we are not liable, take professional advice' as an omnibus disclaimer.

Everyone you go to in finance spouts it as a primordial mantra. If you take it face value, and can make sense of it, the 'professional' you go to advises you - you guessed it - to seek professional advice. A perpetual loop if ever there was one, and a loopy one, at that.

Have you ever come across 'we are professionals, we are liable for our advice, we will take expert advice where we fall short'? No, me neither. Where are these mystery professionals hiding?

If I had the power, I would subject these worthies to a like experience when they have a medical emergency. "We are not liable, we don't know all about you, take professional advice..." This may not prove effective against the pervasive malady, but at least it will be fun! It will also mitigate our longevity concerns somewhat....


Leave a Comment:

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.