Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 538

Is India the world's best growth story?

There's a strong case to be made for investing in Emerging Markets (EMs). For example, when you adjust the GDP of the E7 (the seven largest EMs), for purchasing power parity (PPP), their output is greater than that of the G7 (the seven largest developed nations). In addition, as these nations are growing at a much faster rate than developed countries, their economic significance is increasing.

Within EMs, India is particularly attractive as an investment destination and as the world’s most populous nation it is simply too large for investors to ignore. Once labelled as one of the 'Fragile Five', India has roared to life through strong leadership and a stable government that has implemented positive economic reforms, improved infrastructure, and stimulated private enterprise.

India’s demographics are also favourable. Its middle class is quickly growing in size, and its population is relatively young – much younger than China’s – which has been boosting consumer spending.

India's favourable economic outlook 

In our view, India’s economic growth prospects are more attractive than many other EM and developed nations, including China’s. The World Bank recently said that India’s economy is showing resilience in a challenging global environment. India has been one of the fastest-growing major economies in FY2022-23, expanding by 7.2% and India’s growth rate was the second highest among G20 countries and almost twice the average for EM economies. The World Bank forecasts India’s GDP growth for FY2023-24 to be 6.3%, with the expected moderation mainly due to challenging external conditions and waning pent-up demand after the passing of the COVID-19 pandemic. However, service sector activity is expected to remain strong with growth of 7.4% and investment growth is also projected to remain robust at 8.9%.

India’s economic resilience has been underpinned by robust domestic demand, strong public infrastructure investment, and a strengthening financial sector. Over the longer term, we believe this may support economic growth in the nation led by Prime Minister Narendra Modi, who has prioritised economic development.

In contrast to India’s strong growth prospects and democratic government, economic growth in China has been much weaker. China is dealing with ongoing economic challenges such as government interference in private and state businesses, high debt levels, and instability in the real estate sector. Structural factors too, such as an aging population, are weighing on economic growth in China. China’s economic growth was forecast by the World Bank this month to slow to 4.4% in 2024, down from a forecast 5.1% in 2023.

Other things favour India too

There are other factors we believe favour investment in India over China and other EMs. The nation’s stock market capitalisation is large and diverse – it is bigger than the UK or the German market (as the table below shows). India’s economy and listed companies have benefited from a stable government over the last decade, and that has encouraged growth in its stock market. India’s government has invested significantly on roads and rail and related infrastructure – that has had a multiplier effect on the economy and listed companies are benefitting from the uptick in spending in these areas.
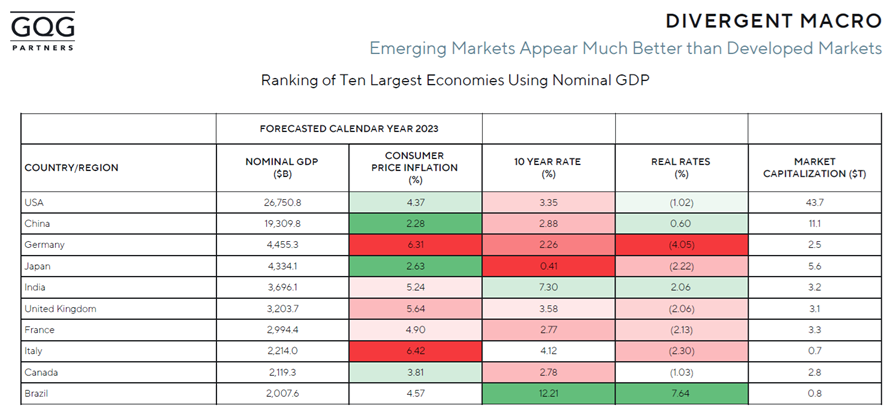

Source: Capital IQ. Estimates for calendar year 2023. Actual results may differ from any projections illustrated above.

Importantly, India’s equity market offers more breadth and diversity than its EM peers; it is significantly less concentrated than Chinese and Latin American equity markets in the largest three sectors, as the table below shows.
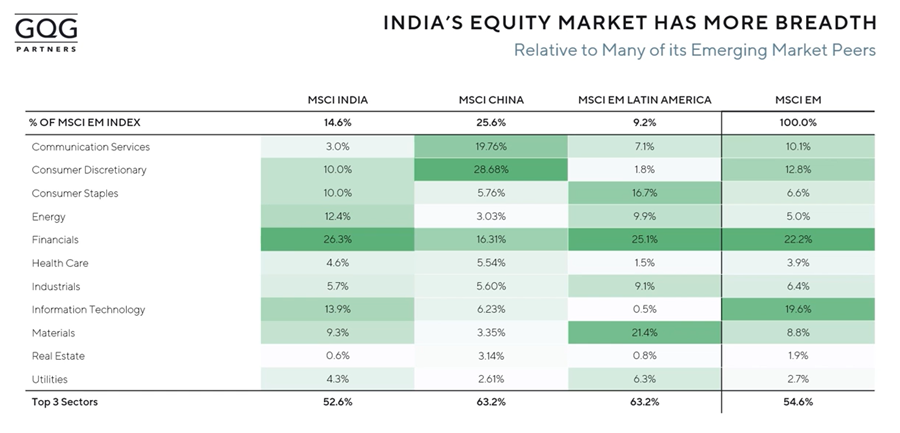

Source: Source: S&P Capital IQ, MSCI. Data as of June 30, 2023. You cannot invest directly in an index. Past performance may not be an indicator of future results.

In addition, India’s stock market arguably offers higher quality investment options than other EMs including China, as its listed companies typically offer a greater return on equity (ROE) than that offered by Chinese companies (as the charts below show). Indian companies offer relatively high ROE as its companies have been relatively capital starved and hence those business that survived and grew tend to be more efficient. We believe active management is, however, needed to identify the most promising investment prospects and help minimise investment risks.
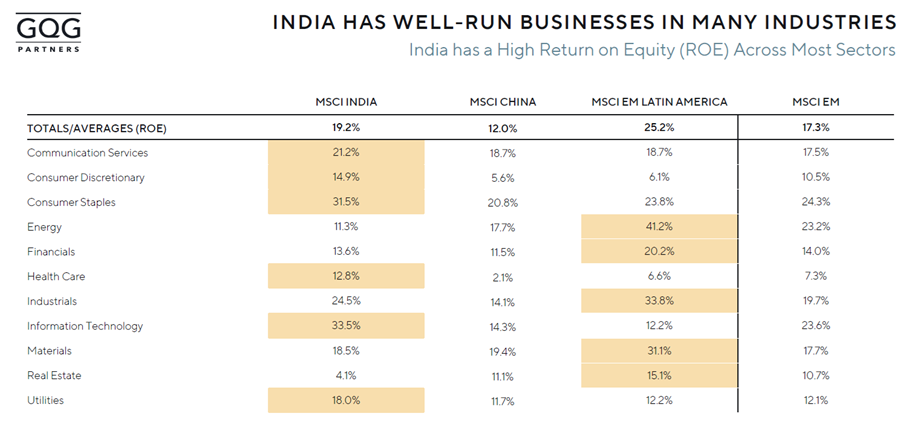

Source: Source: S&P Capital IQ, MSCI. N/A indicates zero sector exposure in that MSCI index. ROE is calculated using the trailing twelve-month period as of June 30, 2023. You cannot invest directly in an index. Past performance may not be an indicator of future results.

There are other positives to investing in India. Structural changes over the past decade have made India more competitive. India has built up its foreign exchange reserves which has given the nation an economic buffer and war chest to handle economic turbulence, such as that resulting from higher interest rates and inflation. Notably, on 14 July 2023, India’s Forex reserves stood at US$609.02 billion, a 15-month high, though they have dipped since then.

Compared to China, India is well placed to grow in these challenging economic times and investors should consider an equity allocation to the world’s most populous nation. 


Rajiv Jain, Chairman and Chief Investment Officer, alongside Brian Kersmanc and Sudarshan Murthy are at the helm of the Investment Management Team serving as Portfolio Managers for the GQG Partners portfolios. This article contains general information only, does not contain any personal advice and does not consider any prospective investor’s objectives, financial situation or needs.


  •   6 December 2023
  • 6
  •      
  •   
6 Comments
Benoit P
December 07, 2023

I used to work in Asia and have never understood the fascination with Chinese stocks. India has had better companies with superior returns on capital for a long time. Even with much higher valuations attached, India should continue to outperform China.

stefy01
December 08, 2023

Perhaps I am naive, but my home is literally full of diverse Chinese made products, but the only Indian products are some jars of curry.
What does India make that the rest of the world wants?

James Gruber
December 09, 2023

IT businesses used in most large corporates around the world: Infosys, Tata, Wipro, HCL (all incredibly successful)


Global coal miner: Adani (incidentally, GQG bought into it earlier this yr after short sellers accused the companu of fraud, and the stock has doubled from the bottom)


Petrochems and others: Reliance Industries Iphones - Tata Group


Oil and gas - ONGC Steel - Tata Steel is top 10 global steel maker


Tea - Tata Global Beverages is one of the biggest makers of tea


Car mirrors/parts - Motherson


Aluminium - Hindalco


Wind turbines - Suzlon Land Rovers - made by Tata Motors


Pharma/generics - Dr Reddy's Labs


Motorbikes - Hero is largest in world


Many others I would have missed.

Tim H
December 09, 2023

Yep, Tata is redesigning the ASX Chess (clearing and settlement) system so every ASX shareholder will soon be relying on Indian technology for their trades.

Guru
December 10, 2023

Jaguar motors is owned by Tata

lyn
December 12, 2023

Hi stefy01, I avoid buying china -made where able, India has good garment manufacturing and better made than most china made garments, I have noticed they make particularly well ( no loose ends of thread hanging) 100% cotton garments which suit our climate and I always hope some of the cotton has been sourced from Australia.


Leave a Comment:

RELATED ARTICLES

The markets to gain most from US rate cuts

10 trends reshaping the future of emerging markets

Five reasons why emerging markets lead tech

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.