Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 458

‘Multidiscipline’: the secret of Bezos' and Buffett’s wild success

In his excellent book, ‘Range. Why Generalists Triumph in a Generalist World’, David Epstein tells the story of the figlie del coro, literally, ‘daughters of the choir’ in Venice in the seventeenth century.

The all-female figlie dominated European music for a century, becoming famous celebrities and inspiring great composers like Vivaldi. Yet they had humble origins, with many beginning their lives as orphans.

So what was the secret behind the figlie’s remarkable musical success?

Versatility.

Unlike many musicians, the figlie didn’t specialize in one instrument. Instead, they learnt to sing and to play every instrument their institution owned. Some of the instruments the figlie learned are so obscure that today they remain completely unknown.

It was this extreme versatility, developed over many years, that gave the figlie a unique power: they could discover the essential concepts that underpinned, not just one instrument, but all instruments. The figlie didn’t master individual musical instruments, they mastered the abstraction of all musical instruments. This allowed them to effortlessly move between musical instruments, relying on useful generalisations, rather than instrument-specific techniques.

The value of versatility

This same ability can also be found in many of the world’s great investors – the ability to abstract away the specifics of a particular domain, leaving only the important underlying principles upon which great investments can be made.

Warren Buffett’s Berkshire Hathaway is a large conglomerate of many different kinds of businesses, from insurers, to rail, to utilities, to industrial manufacturers, retailers and even auto dealers. At the same time, Berkshire has a $US200 billion investment in tech giant Apple.

How is it that one man (or perhaps two, if we include his partner Charlie Munger) can build such an impressive portfolio of seemingly unrelated investments?

The same question could be asked of Jeff Bezos and Amazon. How could Bezos build such a disparate empire across retail, enterprise computing, consumer hardware, video and digital advertising?

Buffett and Bezos both have the unique skill of stripping away detail and get to core principles of successful investing and business building.

But they can only do that because they had years of diverse experiences that allows them to see the common principles that work across multiple domains.

And we see the benefits of multidisciplinary versatility not only in investing. Tennis great, Roger Federer, grew up skiing, wrestling, swimming, skateboarding, basketball, handball, table tennis, badminton and soccer. Federer has cited his diversity in experience and skill development as important drivers of his superior hand-eye coordination.

In a complex, ever-changing world, where domain-specific information is becoming commoditised and readily available, ‘multidisciplinary’ investing has become one of the true sources of an investment edge. Successful investments are often found at the intersection of multidisciplinary insights.

Investors need to not only develop their own multidisciplinary investment process, but also learn to identify managers who have the skills and structures that allow them to harness the power of multidisciplinary investing.

From specific to generalist investing

If investors are to develop the skill of converting domain-specific insights to general economic principles – and unlock successful investments at the intersection of multidisciplinary insights – they need to become ‘versatile’.

In the context of investing, we would define versatility as the ability to successfully employ a wide range of mental models to comfortably traverse along the unique dimensions of a set of multidisciplinary experiences, knowledge, and skills.
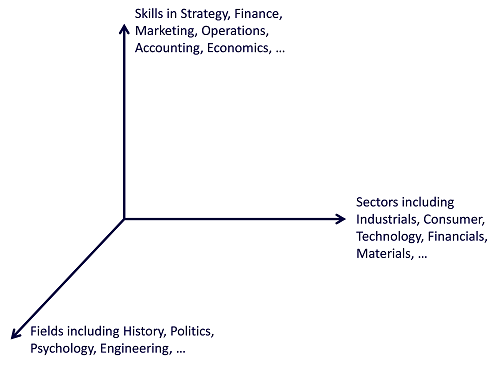
In his famous 1994 address to USC Business School, Charlie Munger shared his views on what he calls ‘Elementary Worldly Wisdom’ as it relates to investing.

“You’ve got to have models in your head. And you’ve got to array your experience – both vicarious and direct – on this latticework of models… And the models have to come from multiple disciplines – because all the wisdom of the world is not to be found in one little academic department.”

Munger goes on to stress the importance of mathematics, probability, accounting, engineering, psychology and building a deep understanding of human nature.

The common factor underpinning massive (unrelated) winners, Costco and Amazon

When investors become versatile across multiple domains, they become skilled at converting domain-specific insights into economic principles common to all domains.

Investing great, Nicholas Sleep, owned a long-term investment in Costco, the big box retailer. At the same time, he owned Amazon, the ecommerce and cloud computing hyperscaler. But his thesis for both investments was essentially the same.

Sleep abstracted away the specifics of the businesses – most of which were totally different – and saw powerful ‘flywheels’ that were gaining momentum and would be very difficult for competitors to overcome.

Sleep saw that both companies, Costco and Amazon, were building scale and sharing the benefits of those scale advantages with customers. This, in turn, drove customer growth and increased loyalty which, in turn, drove more scale.

Sleep’s many years spent developing multidisciplinary experiences and skills enabled him to convert the specifics of Costco and Amazon to the important underlying economics principle of a powerful ‘flywheel’.

Becoming a multidisciplinary fund

Despite the undoubted power of multidisciplinary investing, the investment industry is still largely built on the principle of specialization.

Most investment firms are structured as ‘pods of domain specialists’. An analyst covering banks, for example, has likely covered banks exclusively for the last decade and has little, if any, experience in other domains.

A multidisciplinary-based investment team looks quite different. They are typically characterised by:

  • A team of generalists, rather than a team of specialists
  • A relatively flat team structure that enables ‘cross-pollination’ of ideas and perspectives
  • A team of individuals with diverse prior experiences; and
  • Incentive structures that encourage group success over individual success.

That is exactly what we are seeking to do at .

Montaka’s investment team is structured in a way that seeks to emulate the multidisciplinary success of the investing greats. Each team member is a generalist from day one and covers businesses across multiple domains.

Multiple team members also overlap on the same industry – and even the same business. By bringing together multiple team member perspectives, and drawing on their multidimensional set of prior experiences, we increase the probability that we will uncover the important underlying economic principles that can lead to a substantial investment opportunity.

Unlocking the multidisciplinary magic

For three decades, NASA couldn’t predict solar particle storms. It was an important problem to solve because the radioactive material ejected from the sun can gravely damage astronauts and their equipment in space.

Yet, as Epstein points out in Range, the problem was solved in 2009, just six months after NASA decided to ‘crowdsource’ ideas for solutions from the general public.

A retired engineer from rural New Hampshire used a completely different methodology to rapidly solve a problem that stumped NASA’s smartest mathematicians.

Esptein’s core idea is that the magic happens – the true insights are generated -- at the intersection of multidisciplinary ideas and experiences. That is also true in investing.


Andrew Macken is Chief Investment Officer at Montaka Global Investments, a sponsor of Firstlinks. This article is general information and is based on an understanding of current legislation.

For more articles and papers from Montaka, click here.


  •   18 May 2022
  • 6
  •      
  •   
6 Comments
Graeme
May 18, 2022

Another impressive sounding theoretical article from Montaka. But how does it work in practice? Unfortunately a quick check of the web site https://montaka.com/variable-net/mgaf/ shows their Global Access Fund results. 

Paul B
May 18, 2022

Agree to a point. In the IT industry I encourage organisations to develop "Versatilists" as in my view they need to both broaden and specialise staff skillsets at the same time to stay ahead in an era of rapid change and technological advancement. Would not this also apply to the Wealth Industry?

Scott
May 18, 2022

Berkshires current holding in Apple is $125 Billion not $200 Billion
We all know that people who are great at one thing are usually very good at a number of other disciplines (Buffet is excellent at bridge, he can read and digest large quantities of information every day, he understands people and their motivations, his organisation hires standout people, He and his team place mega bets that have paid off over time).
Finding a fund manager who can outperform the S&P 500 or the Nasdaq long term is very difficult (90% of them can't!).
They usually come unstuck somewhere along the way ie. Platinum, Magellan, ARK, AMP, BT,.....etc....etc

@keith_invests
May 21, 2022

I think you are stretching the concept too far if you are using Buffett as an example of versatility of skills. Berkshire Hathaway may be a conglomerate, but it is far from diversified. It is largely an investor in financial services business & insurance. Berkshire’s purchases off other consumer staple businesses have been far less successful & have been a source of significant losses.

Of far greater accuracy is the idea of circle of competency. For decades Buffett ignored tech stocks despite being friends with Microsoft founder Bill Gates because it fell outside his circle of competency.

Scott
May 21, 2022

Here is a weekly chart of Berkshire (BRK.A) Vs the Nasdaq going back to 1985

https://bigcharts.marketwatch.com/advchart/frames/frames.asp?show=&insttype=&symb=brk.a&x=45&y=11&time=20&startdate=1%2F4%2F1999&enddate=7%2F21%2F2020&freq=2&compidx=NASDAQ&comptemptext=brk.a&comp=brk.a&ma=2&maval=144&uf=0&lf=1&lf2=0&lf3=0&type=2&style=320&size=4&timeFrameToggle=false&compareToToggle=false&indicatorsToggle=false&chartStyleToggle=false&state=15

Berkshire first daylight second (the Don Bradman of investing) runs are on the board!

Denial
May 25, 2022

That's very funny Graeme. Plenty of renters of other peoples money get the same outcome. I've come to conclude that it's all in the deliver not the results unfortunately


Leave a Comment:

RELATED ARTICLES

Does Buffett’s farewell represent peak America?

Does Barrenjoey hold the key to Magellan's fortunes?

Even Warren Buffett lost his edge 20 years ago

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.