Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 545

Passive investors exposed to bubbliest market segment

An intuitive but flawed understanding of passive investing would suggest that, out of 100 active portfolios, an index tracker will come in 50th place. In other words, half the active managers outperform, half underperform, and the benefit of indexing is that you’ll avoid the bottom half and get a roughly average result at very low cost.

2023 shows that’s not quite true, as we can see in the distribution of this year’s returns. In a Monte Carlo simulation, had 100 investors picked 50 equal-weighted stocks at random from the MSCI World Index at the start of the year, a remarkable 92 of those portfolios would have trailed the Index.

In reality, global equity funds did better than just picking stocks at random. Still, the Index managed to beat 73% of active managers—a feat only topped during the build-up to the tech bubble in the 1990s.

What happens next?

That was a clear victory for passive investors in 2023 over us and most of our active peers. But there’s a deeper implication: if you’re buying a passive fund to guarantee an average result, that’s not necessarily what it’ll deliver.

2023 was an outlier on the positive side, but if a passive strategy can deliver a 92nd percentile result, then an 8th percentile result is also possible. That kind of outcome isn’t just theoretical. A passive strategy lagged nearly all simulations as recently as 2009 (3rd percentile) and, before that, in 2000 (2nd percentile).

A passive approach, it turns out, is a distinct portfolio with its own risks and exposures. It moves up and down the performance rankings like any active manager, with one critical difference: how the portfolio is constructed. While we build portfolios based on shares that we believe offer the most attractive value, traditional market capitalisation weighted passive funds allocate strictly according to index weighting, paying no mind to value or risk.

Imagine an investment universe that consists of five equally valuable companies, but one is priced at twice its fair value and the other four are priced at half. While the value-conscious manager would look to avoid the overvalued stock altogether, the passive approach would allocate half its capital there. 

By design, traditional index funds are naturally overexposed to the most overvalued parts of a market. It follows that the environment where a passive approach will rank highest versus peers is one where the most overvalued shares get even more overvalued.

Indeed, the more the valuation gap between overvalued and undervalued stocks widens, the more the passive strategy outperforms, the greater its allocation to the overvalued stocks, the more money it attracts to keep the cycle in motion—and the riskier it becomes.

The converse is also true: the environment where a passive approach will do worst is one where the most overvalued shares sell off hardest (e.g. 2000) or the most overlooked shares recover most strongly (e.g. 2009).

As a barometer of current market conditions, this year’s 92nd percentile performance from the Index is a fascinating tell—one that chimes with our work on aggregate valuation gaps as well as our bottom-up research.

The Magnificent Seven versus the rest

And 2023 isn’t alone. Though 2022 was a break from the recent pattern, US index-tracking strategies have now beaten the combined wisdom of active investors for 8 out of the last 10 years. The scope and length of that remarkable run now eclipses even that of the dotcom boom.

Never before has following the crowd made so much money. Nor, in our estimation, so little sense. But just look at the opportunities the crowd has left for those of us willing to take a different view.

We could wax lyrical about the glaring difference in value between Korean banks priced at 4 times earnings, versus Apple at 28 times, despite diverging fundamentals—Apple is increasingly at risk of bans in China, while Korean banks could double their dividends.

Or how the thick margin of safety at Intel, backed by listed stakes and real saleable assets, compares to the slim margin for error at Nvidia, trading at 13 times next year’s projected revenue. That revenue that could be competed away over time, while Intel’s semiconductor “fabs” in the US are increasingly valuable as the east and the west drift further apart.

We could effuse about the quality of Nintendo’s innovation engine, and marvel at Mr Market’s willingness to extrapolate dominance for the Magnificent Seven while putting little value on Nintendo’s exceptional intellectual property.
But those deep dives would only cover a fraction of the portfolio, which risks diluting the message on how distorted the overall opportunity set has become.

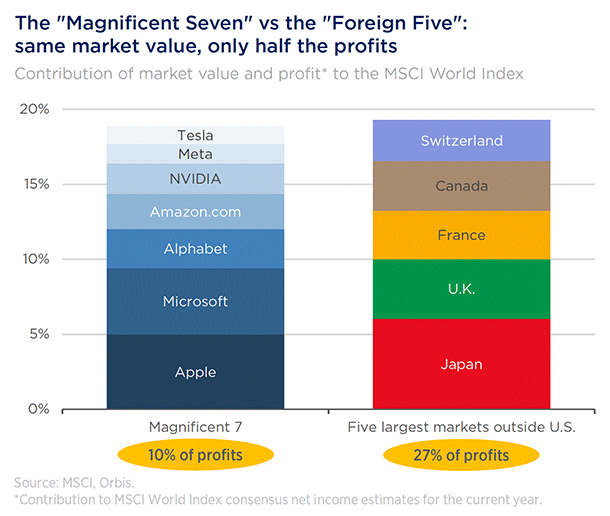
Not since the inception of the first Orbis Funds in 1990 has one country’s benchmark weight punched so far above its share of global GDP (then Japan, now the US). Nor since our sister company Allan Gray’s creation in 1973 have a handful of shares commanded such a large proportion of the market. Today, the Magnificent Seven stocks command as much market value as the “Foreign Five”, the largest developed stockmarkets outside the US by market value, yet the Seven contribute less than half the profits of those stockmarkets.


1 This is the asset-weighted net-of-fee return of all share classes in the Strategy. This return may differ from the return of any individual share class.


This is an extract from Orbis Global Equity’s December Quarterly Commentary.

Eric Marais is an Investment Specialist at Orbis Investments, a sponsor of Firstlinks. This report contains general information only and not personal financial or investment advice. It does not take into account the specific investment objectives, financial situation or individual needs of any particular person.

For more articles and papers from Orbis, please click here.


  •   31 January 2024
  • 5
  •      
  •   
5 Comments
SMSF Trustee
February 01, 2024

So?
We know that we take exposure to 'the market', including stocks that run up 'too fast'. If they fall back, then they fall back. We are in passive funds because we don't believe that it's possible to say when that will happen or how far they'll drop and are willing to accept the volatility.
Because in the long run we believe that stocks will be driven by economic growth and sound management of companies. Volatility - including both the wonderful runup we've experienced and the possible future pull-back - is just noise that we're prepared to live with.
And don't forget - we had that run up in the 'magnificent 7' or whatever people are calling them these days. So what if we give some of that back - we're still enjoying the long term ride.
So please stop trying to imply we're dumb or silly. We do know what we're doing!

James Smith
February 02, 2024

Most overvalued parts of the market comprise of most stable companies that have proven themselves over long term where Index funds invest. Why would you invest in lower grade companies that look cheap on statistical basis but have weak business prospect.

michael
February 04, 2024

Very interesting article, glad I read it.

Going passive is an active choice.

Steve
February 05, 2024

How is the Magnificent 7 that much different to the Nifty Fifty of the late 60s and early 70s?

James
February 06, 2024

Mr Marais' opinions about the superiority of active funds are not consistent with the facts. The Standard & Poors SPIVA report tracks the proportion of active funds that have outperformed the overall market. Over the last 10 years, just 14.4% of active funds have outperformed the US market. Australian active funds performed a little better, with 19.1% of active funds outperforming the overall market.


Leave a Comment:

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.