Our investment philosophy is that we will not forget in our search for returns that the primary risk faced by our clients is losing their capital. Our definition of risk is simple: the permanent loss of capital.
Lessons from history
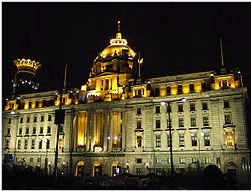
One of the most shocking ways of losing capital is when ownership is taken without proper compensation, either by force or stealth. The majestic buildings on the Huangpu River in Shanghai serve as a good reminder of how quickly and terribly circumstances can change. Number 12, the Bund, was designed by British architects to be ‘the best bank in the world’ in the 1920s. This magnificent building was the headquarters of HSBC in Shanghai before it had to be handed over to the municipal communist government in 1956. Further along the road, the Keswick family lost control of number 27 on two occasions, first to the Japanese and then to the Chinese government in 1954[1].
At this time, Great Britain was one of the most significant investors in China, four times larger than the USA, and had the most to lose from nationalisation. The then British Chamber of Commerce (chaired by J. Keswick in Shanghai - possibly slightly biased!) estimated British investment amounted to £1 billion in Shanghai alone. Another large loser was Shell. According to The Story of Shell in China, the company was the largest foreign operator of filling stations in Shanghai and employed some 2,600 Chinese staff. However, we are told “over the years 1951-53 Shell relinquished most of its depots, residences and service stations in the Republic to the government, together with various quantities of oil and chemicals”. Not only were assets under threat of confiscation but income was reduced by insidious expense inflation after the government linked Chinese wages at British firms to the price of rice, which was in chronically short supply. It was a difficult time for foreign investors and what made matters worse was the absence of recourse in the law courts to claim compensation.
Turning eastwards, the ever-developing skyline of the Pudong is an impressive sight. On a recent trip, we could actually see the futuristic skyscrapers set against a clear blue sky, rather than noxious clouds which have obscured the buildings in previous years. It is easy to get carried away with the sheer scale of the vista. It is intended that way! This special economic zone was the brainchild of the indomitable politician Zhu Rongji who wanted to inspire confidence in domestic and foreign investors after much social disquiet. This worked; the skyline is now one of most photographed in the world and has come to symbolise a bold future with wealth creation aplenty, although not for everyone.
Less impressed by this view are the farmers and families who were encouraged, with scant compensation, to vacate their homes and livelihood to make way for construction. Author Zhaohui Hong calculated these farmers received only one-third of the value of the land with the remainder benefitting the public coffers[2]. A study by the World Bank estimated that local governments expropriated around US$320 billion worth of land from farmers between 1990 and 2010[3]. The common thread is a continued disrespect for ‘property rights’.
It is with this in mind that we are especially vigilant to study the substance rather than just the form of each possible investment in China.
Lessons that apply today
The extremely popular internet giants (Alibaba, Tencent and Baidu) and the legal structures on which they rely are a case in point. These structures are known as variable interest entities (VIE), an American creation, made famous by Enron in 2001. In the case of China they are used to circumvent restrictions on foreign investment in certain key industries, such as steel and media. It is a complicated arrangement as it permits two different parties (the Chinese regulators and foreign investors) to claim ownership of the same operating assets. Each VIE is different but the common feature is that investors can only buy shares in a listed company with no actual ownership of sometimes the most valuable assets, gaining only a promissory note of entitlement. Instead, investors are asked to rely on a legal agreement that entitles the ‘listco’ to a share of the profits from the separate company. Using the prospectus of JD.Com as an example, investors are clearly warned that the government could confiscate income or force interests to be relinquished if it is deemed that regulations, or the interpretation of existing regulations, is changed. It is worth pondering how companies incorporating such risks could be allowed to list in the US but the SEC (Securities and Exchange Commission) cannot ban offerings for being too risky or even potentially illegal, all they can do is require full disclosure of the risks. With such warnings in writing, it would be extremely difficult to protect investors' rights should anything untoward unfold.
These risks have arisen in China not just in the early decades of communist rule, but recently. In 2008, the Agria Corporation lost control of a Chinese subsidiary to a discontented executive. The asset was only retuned to the company when the executive received additional compensation. Another example is the disappearance of Alipay, much to the chagrin of minority investors, Yahoo and Softbank, to a company owned by the founder Jack Ma. More recently, shareholders of RenRen (a social media network) alleged in an open letter that the founders were attempting to “enrich themselves to the detriment of all other shareholders”. In this case governance was tested, animosity lingers and the share price has fallen 75% from its all-time high. One further governance concern is an iniquitous number of votes, attached to different classes of shares, which is common among these companies. In the case of JD.Com, foreign investors need to be completely confident of their alignment with the founder as he controls twenty times more voting power should any disagreement occur. While these arrangements have so far been honoured, they are ripe for abuse and give no guarantee that they will stand the test of time or any political change.
Politics can change quickly
We are particularly nervous about Emerging Market billionaires who become politically connected and advantaged. Political connections can provide tailwinds but we find it very difficult to predict, if and when, such winds may alter course. At present, media in China is mostly closed to foreign competition but should the increasingly powerful Chairman of everything, Xi Jinping, feel threatened, or simply be so inclined, circumstances could quickly change. We remember too well what happened to the share price of Russian company Yukos when its CEO fell out of political favour. He who giveth can taketh away! In addition to politicians, society provides a license to operate which, as in the case with Facebook, can be harmed if it is deemed to be overly intrusive or misused. Despite such apparent risks, Chinese internet companies have proven to be extremely popular. In 2017 they doubled in value and are collectively worth more than US$1 trillion in market capitalisation. Their substance is poor but their form is good with strong operating and share price momentum. For many investors this presents interesting behavioural challenges.
We follow a strict adherence to another tenet: "We will not succumb to irrational exuberance in good times, nor unjustified gloom in bad times."
Chris McGoldrick is a member of the Sustainable Funds Group investment team at Stewart Investors, a semi-autonomous business unit within Colonial First State Global Asset Management, a sponsor of Cuffelinks. This article is for general information and does not consider the circumstances of any individual.
For more articles and papers from CFSGAM, please click here.
[1] M. Keswick, The Thistle and the Jade.
[2] Zhaohui Hong, The Price of China’s Economic Development: Power, Capital and Poverty. p124
[3] China’s Economy – What Everyone Needs to Know. Arthur Kroeber. P36.