Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 401

Risk in retirement: five strategies for finding the right balance

For many, retirement means dream holidays, reading books and spending time with grandchildren.

However, for some Australians, the notion of enjoying their golden years after a lifetime of hard work hit a roadblock last year when COVID-19 struck and hit economies and markets hard. Many businesses were affected and the associated restrictions impacted employers, employees, profit margins and, ultimately, dividends. Retirees have been feeling the pinch, particularly self-funded retirees, and those that utilise investment properties as a source of retirement funding may also feel the effects with rental reductions and an influx of properties on the market.

Against this background, retirees still need to take measured risk to meet their goals, but they may need to plan differently than they would have in the past.

Why do investors need investment risk?

Regardless of retirement status, all investors face investment risk of some kind. Risk refers to the degree of uncertainty or potential financial loss that is inevitable in any investment decision. Typically, as investment risks rise, investors seek higher returns to counteract their own anxieties for taking such risks.

However, retirees usually view the world differently from when they were working, and perhaps the single largest change they experience is how they respond to risk. Typically investors are much more ‘loss averse’ in retirement, that is they fear losses much more than gains feel good.

Nevertheless, it is still necessary to take some degree of investment risk with their superannuation assets. If retirees opt to take little or no investment risk, then their investment outcomes will probably be less than needed to achieve their lifestyle goals.

Investment strategies need to take into account each unique risk profile. This profile includes risk tolerance, risk capacity and risk requirement.

Risk tolerance refers to an investor’s subjective attitude towards taking risk. It’s a measure of how they feel when markets become volatile and uncertain.

However even if people are willing to take the risk, they may in fact not be able to afford it - what they can actually afford is referred to as risk capacity.

And risk requirement is the amount of risk people need to take in order to achieve their desired returns.

A solid retirement strategy balances all three of these risk components.

Strategies designed for retirement

Of course, there is no single investment strategy likely to suit all Australians. Retirees need to take into account of their risk profile, their financial circumstances and objectives, the taxation system and Centrelink benefits.

The spectrum of retirement investment strategies ranges from a ‘business as usual’ approach to a significantly more complex ‘income layering’. The spectrum allows for varying degrees of personalisation, and not all of them address all of the risks investors face in retirement.

The table below compares features of each of the most common approaches used by advisers for retirement strategies and how well each approach deals with the primary risks.
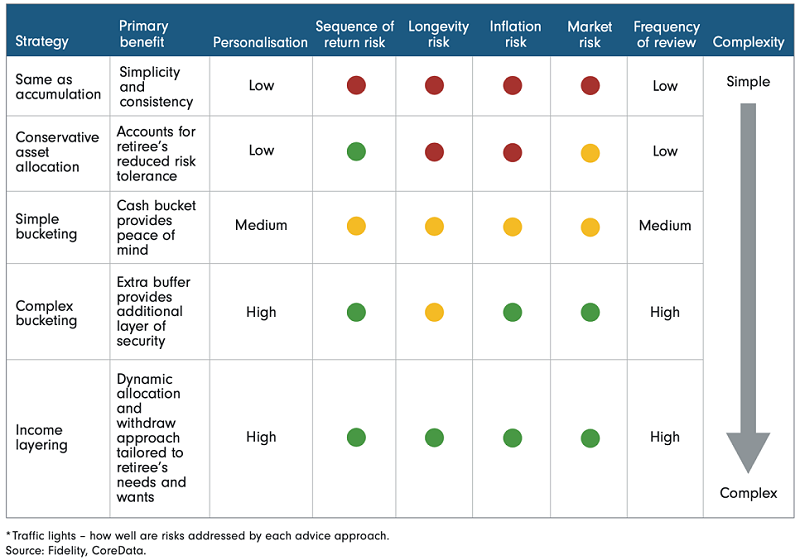
Strategy 1: Same as accumulation phase

This is a ‘business as usual’ approach and involves retirees simply extending the same investment strategy from the accumulation phase into the retirement phase. As the goal in the accumulation phase will usually be to maximise total return on investment, retirees opting for this approach implicitly remain long-term investors with the ability to continue to tolerate market risk.

This strategy potentially overlooks the sequence of return risk and fails to consider most retirees’ reducing risk capacity as they age.

Strategy 2: Transition to a more conservative asset allocation

Many Australians opt to move to a more conservative asset allocation strategy in retirement. Generally, retirees’ portfolios have a large percentage of the total portfolio allocated to low-risk and low-volatility assets such as conservative equities, fixed income and money market securities.

This strategy ultimately helps to manage the sequence of return risk, potentially making it suitable for retirees who value downside protection more than the upside growth. However, if the strategy is overly conservative, the relatively constrained upside potential of the strategy may expose investors to greater inflation risk.

Strategy 3: Simple bucketing

This strategy divides investors’ portfolios into separate components (or buckets) with each bucket serving different objectives.

A simple bucketing approach has only two buckets: a cash bucket and a diversified investment bucket. This approach provides retirees with a short-term cash buffer against market shocks. When combined with a rebalancing discipline this approach can be effective in providing the right amount of risk exposure whilst providing the investor with sufficient liquidity for their short-term needs during periods of market volatility. Investors can better manage both sequencing risk and market risk.

Strategy 4: Complex bucketing

Retirees seeking a more bespoke approach which divides accumulated savings into discrete pools with different objectives. The complex bucketing strategy also helps to manage retirees’ sequencing and inflation risks by segmenting the retirement savings pool into different time horizons.

This approach can be viewed as an asset-liability matching strategy as it seeks to match short-term liabilities (or spending requirements) with cash and short-term bonds, providing investors with confidence that money will be available when needed, even in declining markets.

It also seeks to match investors long-term liabilities (or expected expenses) with relatively long-term assets such as equities, with the aim of providing greater return and ultimately, the resources to meet their expected future spending needs. By not needing to draw on the long-term assets when markets are volatile, the benefits of compounding are able to come through with this type of strategy.

Strategy 5: Income layering

This strategy divides retirees’ portfolios into separate components, based on their spending needs for life. Spending needs can be grouped into four distinct categories: basic living expenses, contingency expenditures, discretionary expenses and legacy (children’s inheritance), as shown below.
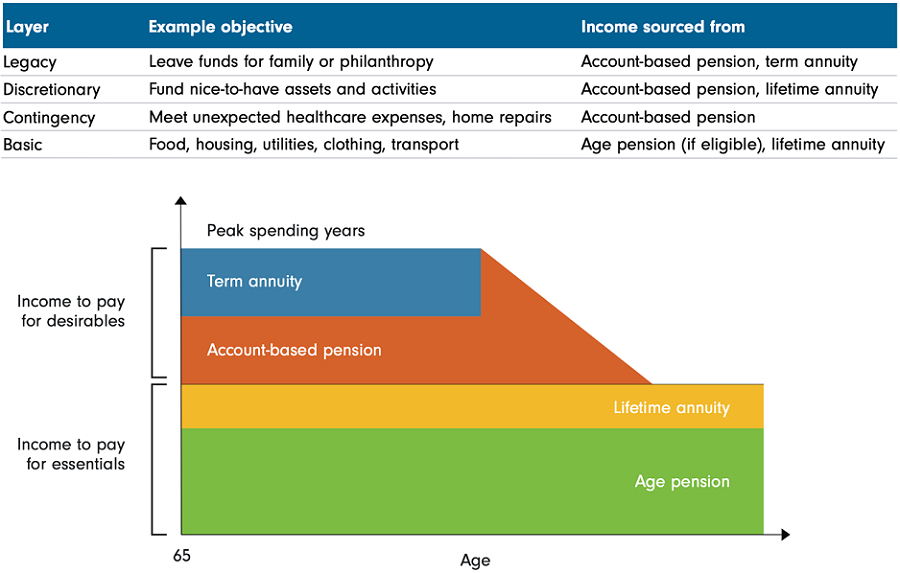
Source: Challenger

This type of strategy matches investors’ income priorities with their spending priorities and separates their needs from their wants, while prioritising income accordingly. Term annuities or bond ladders can be used to provide the shorter-term income needs.

Conclusion

To summarise, a certain level of risk-taking is necessary for retirees to achieve their investment objectives and a solid retirement strategy balances all three components of a retirees’ risk profile, allowing them to sleep soundly at night without needing to worry about their investments.


Richard Dinham is Head of Client Solutions and Retirement at Fidelity International, a sponsor of Firstlinks. This document is issued by FIL Responsible Entity (Australia) Limited ABN 33 148 059 009, AFSL 409340 (‘Fidelity Australia’), a member of the FIL Limited group of companies commonly known as Fidelity International. This document is intended as general information only. You should consider the relevant Product Disclosure Statement available on our website www.fidelity.com.au.

For more articles and papers from Fidelity, please click here.

© 2021 FIL Responsible Entity (Australia) Limited. Fidelity, Fidelity International and the Fidelity International logo and F symbol are trademarks of FIL Limited. FD18634.


  •   31 March 2021
  • 7
  •      
  •   
7 Comments
Jack
March 31, 2021

I wonder how many people can be so disciplined. Really, I'd rather just get on with my retirement and stop worrying about running out of money in 20 years time. As Ralston says, there's always my house to pay for the SKI holiday.

Owen Lewis
March 31, 2021

I read recently a great thought. You don't have to design your car first before you drive it. Why do we ask folk to design their pension then?

For home owners, there is your cash buffer. Don't bother having buckets inside your Super, have it all in the growth fund. If you have a crappy year of returns, shove the min draw-down st back into the same product (losing the tax advantage of course but you had no choice anyway)and use the cash in the house (redraw account) until the "shoved back in" matches the cash borrowed and then pay that off.

Simple as. As you get older and less likely to be able to manage it, you wont need to, as your expenses will have dropped until you need end of life care. At that point you can spend what you haven't lost.

You just need to hedge the odd bad year of returns with your house equity.

Of course, none of that works if you don't own the house. Which means you probably don't have much super anyway and you are on the pension which is the best financial product ever!

We are all going to need someone with a brain and much younger to handle our wealth as we age.

Frank Tuyl
March 31, 2021

Owen,
I think I like your idea! What did you mean by "back into the same product (losing the tax advantage of course but you had no choice anyway)"?
Regards,
Frank

Dane
April 02, 2021

The lifetime annuity for the bottom layer makes sense as its more attractive than a bond ladder strategy plus there is the bonus of mortality credits. Unless your a Challenger BDM, not sure I understand the role of term annuities at the top of the stack.

Paul B
April 03, 2021

Wonderful clear article Richard that has clarified my thinking on the subject and prompted me to think about making a few adjustments. I also like your thoughts Jack and Owen - to each their own.

Steve
April 07, 2021

Commercial annuities of the type offered by Challenger have woeful income (% of assets). This is the key "missing piece of the jigsaw" in retirement planning. If annuities with half decent returns (5-6%) were available many more might use them. Instead we have to view a diversified portfolio of equities etc as a quasi annuity. Clearly the more risk can be pooled the easier to provide "average" returns over time. Given modest returns these days, once you take out advisor fees (I suspect alot of Challengers business comes from advisors) and the profit Challenger makes, and also their forced very conservative investment mix (so they don't run out of money!) leads to a mediocre outcome.

Lisa
April 11, 2021

The article reinforces a basic investment principle, that diversification is a great hedging tactic. Having a combination of short and long term investment grade corporate bonds, an equities portfolio that straddles ETFs, capital notes and individual value stocks, and a cash bucket holding three to five years’ income provides so much flexibility within the structure of an SMSF. Add to this a modest, private non-SMSF mixed portfolio and there is room to move on all counts.


Leave a Comment:

RELATED ARTICLES

How decumulation in retirement differs from accumulation

Dealing with retirement anxiety

The runway to retirement is shorter than expected

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.