Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 409

Single-period measures do not work for great growth companies

The growth versus value dichotomy lies in plain sight, as broad market indices such as the S&P 500 have outperformed the tech-heavy NASDAQ in recent months. These gains are in contrast to movements in calendar 2020 where tech ran strongly ahead. Investors of both persuasions are wondering whether the price of growth companies has largely been captured with value companies yet to fully reflect the 're-opening trade' as vaccinations increase, borders reopen selectively and airline bookings pick up.

We think not. Earlier this month, the Wall Street Journal published the following chart with accompanying commentary, of the quite mind-bending revenue growth numbers produced by the disruption giants in the March 2021 quarter, relative to the same period last year. These numbers show a pattern of growth accelerating coming out of the COVID year.

Remember, this group picked up steam even as COVID hit. A fall in revenue growth could have been expected as the world began the slow climb to recovery.
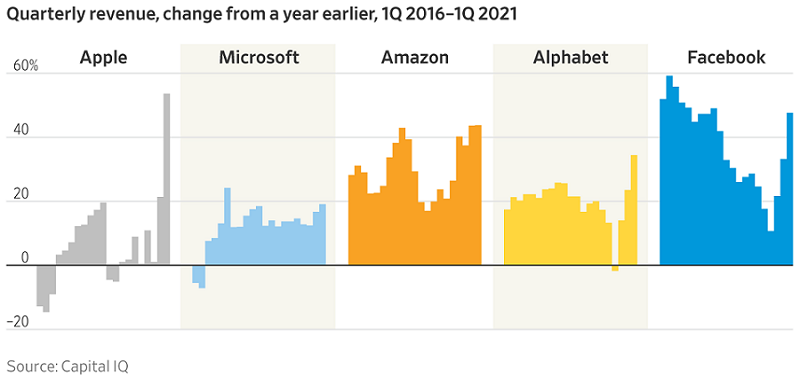
Doing well, even in a pandemic

These companies are recording (for the most part) their strongest quarterly revenue growth in five years. Microsoft chief Satya Nadella, on the most recent earnings conference call, said:

"Over a year into the pandemic, digital adoption curves aren’t slowing down. They’re accelerating, and it’s just the beginning. We are building the cloud for the next decade, expanding our addressable market and innovating across every layer of the tech stack to help our customers be resilient and transform.”

But the share prices of these stocks did not rise following these blow-out numbers - indeed a couple fell. In truth, they mostly rose in the weeks leading up to the results, so perhaps no further lift on the result was to be expected.

Meanwhile, there is no doubt that some of the beaten-down value players are enjoying their period in the sun, as the chart below on growth versus value shows.
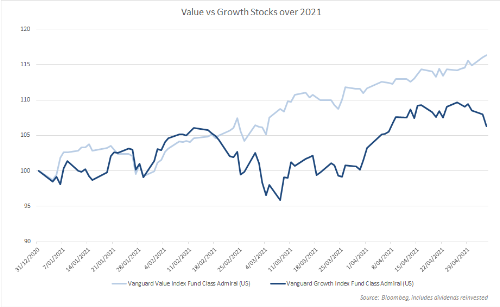
Our caveat is that this value resurgence should be regarded with some circumspection. Take for instance the European car makers. On the one hand, Volkswagen, the largest car producer in the world with production of over 10 million vehicles annually, has fully embraced the electric vehicle, committing to the virtual phase-out of internal combustion engines entirely within a decade. It has been reported that VW's admittedly smaller rival, BMW, has not committed to the electric switch, with the BMW board against it because the margins are lower than for the ICE cars. Frustrated innovative, creative, and smart engineers left BMW, partly founding their own battery electric vehicle startups in China or the United States, it has been widely reported.

Traditional valuation methods do not apply to strong growth stocks

In our view, there are value (lowly-priced) stocks, and there are value companies which have a plan for the future, and they are different. Disney is in the latter group, moving from a model in which it relies on cable companies to sell its programming in favour of a streaming service like Netflix.

Kodak is an example of a value company which failed to adapt, and so never realised its value promise.

The key is a systematic approach to valuation. We apply a multi-year discounted cashflow valuation process, designed to capture shifts in business strategy (positive or negative). We do not use single period measurement tools such as P/E or EV/EBITDA but consider the likely cashflows looking out over a number of years. This allows us to understand the prospects of the giants mentioned in the Wall Street Journal article as well as many other companies that we expect to be household names in the future.

For example, we have held Xilinx, Nvidia and Qualcomm for over three years as our expectation of the companies' valuation has emerged and the share prices rocketed. The earnings power of these companies cannot be assessed using single period measures.

The process is also useful in assessing the valuation of companies which are moving from loss to profit. We hold a small number of these companies because we consider that their growth potential is significant (meaning global). Netflix was only barely profitable when we initially opened the position yet this quarter announced a US$5 billion buyback of stock.

There are some years to go before Netflix reaches our future valuation of the company. Similarly, with the other FAANG companies (Facebook, Amazon, Apple, Google) we see multi-year growth paths for these companies.

It also helps us to screen out companies which have deep-seated problems which are not being properly addressed by management, notwithstanding how good their earnings may be in any given period.


Alex Pollak is Chief Investment Officer and Co-Founder of Loftus Peak. This article is for general information only and does not consider the circumstances of any individual.


  •   26 May 2021
  • 2
  •      
  •   

RELATED ARTICLES

Reece Birtles on selecting stocks for income in retirement

Irrational exuberance in growth versus value

Is FOMO overruling investment basics?

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.