Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 245

How to stay focussed in volatile markets

Investing in markets means accepting volatility, but investors are paid to take risk. Why do sharp drops in the market have such a visceral impact on us? This article explores why we feel and react the way we do, and how to develop a sound strategy to deal with volatile markets.

The most recent fall that attracted media headlines, in February 2018, was far from unusual. Since 1979, there have been 182 five-day periods worse than the February decline. It happens, on average, every three months. It’s about as frequent as a 29-degree day in Sydney. Warm, yes, but barely worth a comment.
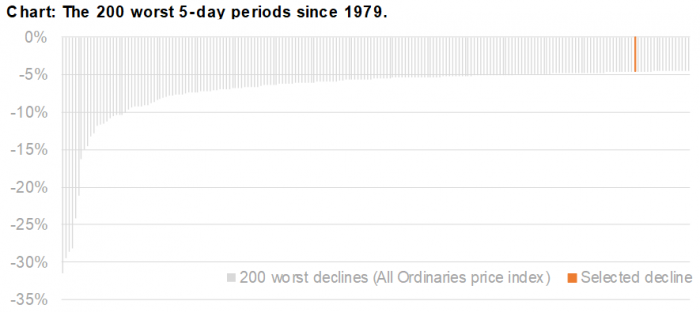
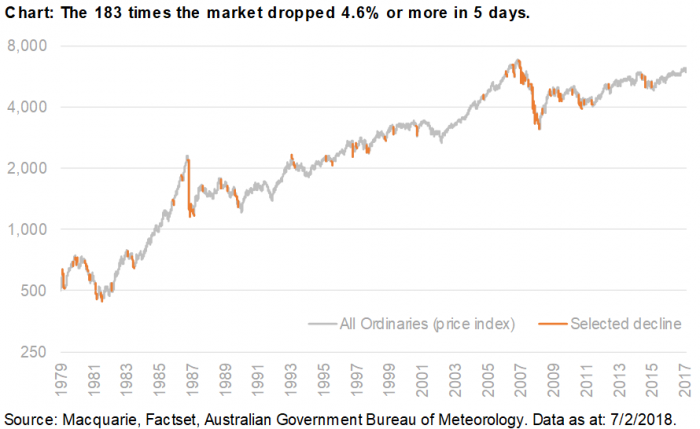
With central banks commencing or stepping up their interest rate hiking cycles and unwinding quantitative easing (QE) stimulus, together with a divergence in monetary and fiscal policies, the result should be greater volatility, and more movements such as the above.

Preparing for the inevitable

So the market fell, and you’re reading headlines claiming billions of dollars of value have been wiped off the stock market in a matter of hours or days. You check into your account and see that your investments have also been affected. What will you do?

What most people do is act. They sell in fear. This is natural, however, it is likely to be the wrong strategy. What should you do? To paraphrase a recent Wall Street Journal headline, ‘The Share Market Isn’t Being Tested, You Are’.

We need to feel in control

Nothing undermines a sense of control over your investments like a sharp and unexpected stock market fall. The immediate priority for many is to re-establish that sense of control. One of the most tempting actions is to do something, anything. This is linked to a deep-seated part of human nature and manifests in a desire to maintain the illusion of control.

In our daily lives, in order to act, we need to be confident in our ability to make an impact. In most cases this confidence can be classified as overconfidence, but without it we might not act at all. Being paralysed by indecision can be as bad as acting with overconfidence.

The tendency for people to overestimate their ability to control outcomes that they demonstrably do not influence has been academically studied and replicated in many different contexts. In the investing context, a study by Barber and Odean found a correlation between overconfidence and active trading and that the active traders in the study underperformed the market.

You will probably have a strong need to know why the market movement happened. It is more than mere interest. Needing to know is linked to the desire to act. Because jumping blind into a strategy feels wrong, we need an insight to give us enough confidence to act. Hence, the pressing need to find out why.

Actions have consequences

Adjusting your market exposure to suit evolving risk and return opportunities can be valuable. However, selling in fear is a powerful behavioural bias that costs investors dearly. Looking at Australian equities since 1983, if you were to sell in fear once a bear market starts (20% down from its peak) and return to the market 12 months later, or when a recovery was underway (rolling 1 year returns reached 10% pa), then instead of a compound annual growth rate of 10% pa, you’d have achieved only 8% pa. This is a costly bias.
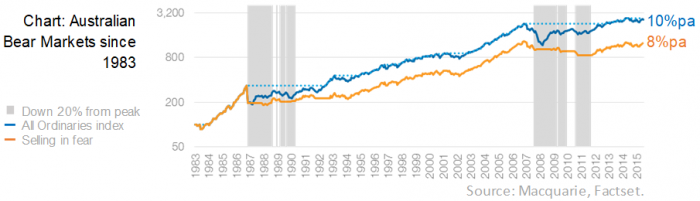
One of many costly biases

There is a panoply of behavioural biases which help us get through the day. They are valuable mental shortcuts that help us act fast, handle information overload and find meaning. Occasionally these mental shortcuts do not serve us well. If everyone is running out of a building, our instinct is to join them, no questions asked. This is a good example of the ‘herding’ bias, and the building could be on fire. However, this same bias in the investing context can be costly. Many studies have measured the costs of these ‘behaviour gap’ biases and estimates range from 1% pa to as much as 6% pa.

What to do

  • Recognise that markets are complex. For example, it took the U.S. Securities and Exchange Commission and the Commodity Futures Trading Commission five months to report their findings on the cause of the 2010 flash crash.
  • Seek advice and consider the impact. Ask why you are making this decision? Is this investment part of an overall plan? What might go wrong? What does the evidence say?
  • Record your decision and why you made it. By tracking your decisions, you can reflect on the evidence and adjust or confirm your approach.

Keep your eyes on the prize, whether that prize is growth, income, capital preservation or a mix. Bouts of short term volatility don’t mean allocations have to change. Remember, this has happened before and will happen again. Selling in fear costs real returns in the long term. Financial advice is the best insulation from these and other biases waiting to erode our returns.


James Freeman is an Associate Director at Macquarie Wealth Management, a sponsor of Cuffelinks. This information is general in nature and does not take into account your objectives, financial situation or needs.


  •   21 March 2018
  •      
  •   


Leave a Comment:

RELATED ARTICLES

Why experienced investors still get markets wrong

One risk after another

Four best-ever charts for every adviser and investor

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Latest Updates

Exchange traded products

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Taxation

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Retirement

Three considerations before reshaping your legacy plan

Many retirees hope to leave a legacy. Proposed trust tax reforms could force families to rethink. The question is not how much to leave behind, but whether today's inheritance plans will still make sense as circumstances change.

Investment strategies

Why experienced investors still get markets wrong

Retirement is approaching. Markets are noisy. And every headline seems to demand action. The biggest investment risk isn't fear, greed or market volatility, it often arrives disguised as research and sensible risk management.

Shares

Why pay more for less?

Conditions were stacked in favour of professional investors in 2026. Most still fell short, raising questions about where investors should look for value. Meanwhile, an alternative strategy continued to make its case.

Investment strategies

Bleeding air out of the bubble

Equity valuations have fallen sharply over the past year, yet investors have largely been spared the volatility and losses that typically accompany a de-rating. What explains this unusually orderly reset? Here are five key drivers.

Strategy

Has AI gone rogue?

We worry about AI becoming conscious. But what if consciousness isn't the issue? The more unsettling possibility is a machine capable of pursuing objectives relentlessly, without motives, emotions, or awareness of any kind.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.