Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 220

The truth on three big indexing questions

Indexing has become an undeniable force in the investment world. Consider that US$1.4 trillion in net new cash and reinvested dividends flowed into US equity index funds and ETFs in the decade through year-end 2016, which is astonishing compared with the US$1.1 trillion in net outflows from active funds in the same period.

Indexing’s rise did not happen by accident. At Vanguard, the improvement in index fund management included refining index sampling techniques, better approximating the fundamental characteristics of benchmarks, working closely with benchmark providers and strengthening index methodologies.

But the push to improve indexing does not stop there. In my new role as Vanguard’s Chief Investment Officer, my global team and I are dedicated to staying abreast of new themes in the investment world, especially exploring the details of what makes indexing tick. Our mission is to optimise the investment outcomes for our clients and investors overall at a low cost.

I am a firm believer in the value indexing delivers to both the investor and the market as a whole. But over the last few months, indexing has received criticism from a few commentators alleging indexing hurts price discovery, stifles competition via common ownership, and leads to higher volatility. I believe those claims are inherently false, so let’s walk through these arguments and set the record straight.

1. Does indexing hurt price discovery?

The concern about indexing hurting price discovery is naive. Price discovery is driven by active managers, Vanguard included. I know from my years as a bond guy the vital role that active managers play in keeping security prices aligned with their value. The thought that indexing could somehow get in the way of that is troubling for me. But the truth is that even though indexing has grown in popularity, it’s still a small part of overall trading volumes (i.e. portfolio managers’ trading of index funds’ underlying securities). Since indexing represents about 5% or less of US equity daily volumes, as shown in the chart below, there is still considerable price discovery and liquidity provided by active managers.

Breakdown of overall individual stocks’ trading volume
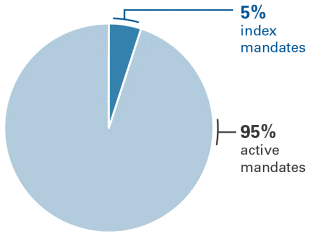
Sources: Vanguard and Bloomberg, 2017.

2. Does indexing cause a lack of competition?

Critics claim that managers of corporations whose stocks are in some of the leading indexes become complacent participants, rather than competitors, because stock prices are propped up by the steady drumbeat of index investments. There is no evidence to support these anticompetitive practices or that there is a cause-and-effect relationship between common ownership and product price competition. All the corporate executives that I know are diehard competitors and are doing everything in their power to expand market share, increase revenues, and boost profits.

In addition, as owners of just about every company in every industry, index funds have no incentive to favour one industry over another as higher product prices in any one industry would cut against fund investors’ interests in other sectors.

We believe fierce industry competition produces greater shareholder return and a healthier industry as a whole, since competition forces companies to constantly innovate and find new ways to deliver value to both consumers and shareholders. We firmly believe the best performers should be rewarded, which is why we advocate for executive compensation plans to be tied to performance, not stock price, and have explicitly promoted competition among firms in their respective peer groups.

3. Does indexing drive volatility?

I do not see any substance to the concern that equity index funds contribute to market volatility. Regardless of size, indexing is not a monolithic investment strategy. Index investments are spread through many market caps and investment styles, and the majority of index assets are held by long-term investors in broad-based, market-cap-weighted funds. There is no convincing evidence that the growth of index funds has had an impact on market volatility or the dispersion of stock returns. Even as index funds’ share of mutual fund assets has consistently grown, market standard deviation has risen and fallen in a seemingly random pattern. Dispersion among the stock market’s securities has remained somewhat constant, except for the tech bubble and the global financial crisis.

The real truth: indexing has earned its accolades

Indexing has transformed the investment experience for millions of investors. We take pride in the fact that we have helped investors enjoy the many benefits of indexing, including:

  • Low cost
  • Broad diversification
  • Relative predictability
  • The potential for long-term outperformance compared with the performance of many high-cost active fund managers.

Indexing offers a firm foundation for investors seeking to achieve their investment goals, and as Vanguard’s CIO, it’s my job to make sure that indexing and active management continue their symbiotic relationship in the investment landscape.


Greg Davis is the Vanguard Group’s Global Chief Investment Officer. This article is general information and does not consider the circumstances of any individual.


  •   21 September 2017
  • 2
  •      
  •   

RELATED ARTICLES

The challenges of building a lazy portfolio

Everything my friends need to know about investing

Howard Marks asks 5 questions on indexing

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.