Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 364

Welcome to Firstlinks Edition 364

  •   1 July 2020
  • 2
  •      
  •   

Weekend market update: the US market moved little on Friday, although the NASDAQ rose to another all-time high, holding well above 10,000. The US was up a solid 4% for the week, while Europe rose 2.8% and Australia 2.6%. All this against a backdrop of rising virus cases, stalled reopenings and the Victorian outbreak locally.

Australian shares had their biggest annual loss (down 11% in price or 7% with dividends) for eight years in FY20 while Wall Street just had its best quarter (up 20%) since 1987. Whatever happens from here, we will look back in a couple of years and say the outcome was obvious. We will either say, "Of course markets rose as governments injected unlimited liquidity, medical science improved treatments and the economy rebounded quickly" or "Of course markets fell as businesses collapsed, millions of jobs were lost forever, the virus was resilient and consumers changed forever." Which side are you on? I'm in the latter camp but forecasting markets is not my strong suit.

Similarly, many people are annoyed they missed the low of 23 March, and are thinking "Just give me another chance to invest at 30% less." But this is more a reaction to knowing the market has risen. If it actually fell heavily again, the majority of people would do nothing as it always looks as if the market will go further. Shares are not like bananas - we usually don't buy more when they are cheaper.

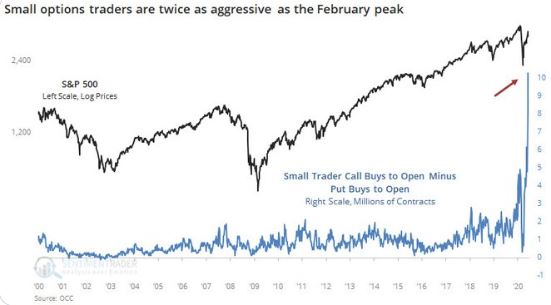
So it's good to read an update from Howard Marks including his views on market psychology. He points to the impact of Fed liquidity and new traders playing the market like a game, noting the volume of 'small trader calls' (where people pay for the right to buy the market at a certain level) is through the roof, as shown below.
Note that there is not much evidence of this speculative type of new activity in Australia, where retail investors are more focussed on traditional quality stocks.

Two COVID-19 milestones this week, reaching over 10 million cases and over half a million deaths, gave the market the wobbles on one day but a 'nothing to see here' the next, so we are none the wiser on the next trend. 

There are few signs that The White House is worried but Donald Trump should be. Consider the response in this interview (watch from 36.45) when asked for his top priorities for a second term:
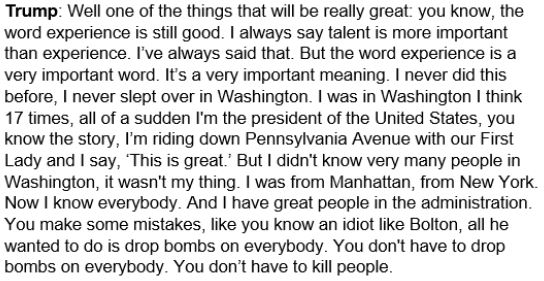
Ask yourself, if you were on the board of a company interviewing a CEO, how would you interpret that set of strategic priorities?

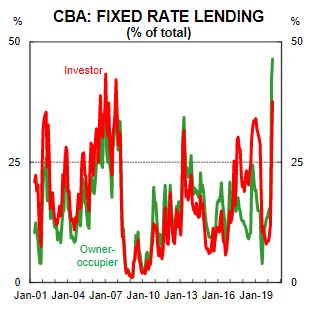
Meanwhile, in Australia, one way borrowers are coping is to switch to fixed rate loans, as shown below in the CBA statistics. The variable rate is at least 0.5% higher than two-year fixed, and owner-occupiers are at the highest level ever for fixed rate borrowing. Well worth considering with rates around 2% to 2.3%, although RBA Deputy Governor Guy Debelle said this week that a rise in the cash rate is "some years away". Good to have a clear central bank forecast.
In this week's edition ...

Another industry veteran, Don Stammer, gives his take on whether 'this time it's different' has much meaning to someone who has seen multiple market cycles. 

Franco Morelli continues his look at SMSFs, this time checking how contributions have changed and the differences between accumulation and pension stages.

Among the most vulnerable in society are older women who have been unable build a super balance due to family circumstances. Erica Hall says the pandemic has made their plight worse.

APRA's attempts to rate large super funds based on their performance was always a tall order, and David Carruthers does the numbers to show the best funds in a strong market often struggle in a downturn. 

Matt Rady reports on research with people near or in retirement and the profound impact COVID-19 is having on retirement plans. The same thing happened in the GFC. People lose faith in their ability to withstand a downturn, especially when generating income requires taking more risk.

Finally, back to practicalities with Julie Steed's explanation of death benefit pensions. Anyone with a family member drawing a super pension should check this.

This week's Sponsor White Paper from Martin Currie looks at opportunities where Emerging Markets (EM) companies are being especially innovative and disruptive. It's a part of the market most investors ignore.


Graham Hand, Managing Editor

Attached here is a full PDF version of this week’s newsletter articles.


  •   1 July 2020
  • 2
  •      
  •   
banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.