In theory, the goals of all investors are founded on the same underlying principle: to maximise returns for the risk that they are willing to bear, or to maximise risk-adjusted returns. In recent years, there have been considerable changes in how professionally managed portfolios are constructed, with many investors implementing larger allocations to alternative assets, a strategy that was pioneered by endowment-type investors.
The best-known example of such an investor is David Swensen, the Chief Investment Officer for Yale University’s endowment assets. An endowment portfolio is usually invested to generate continuous income, such as to fund Yale’s services, using large allocations to alternative asset classes.
Moving beyond typical stock and bond portfolios
Over time, we have seen considerable changes in the make-up of portfolios as investors have moved beyond typical stock and bond portfolios and introduced alternative assets, such as hedge funds, private markets, direct property and infrastructure. It is this allocation to alternatives, however, that still differs materially between investor types, with the allocation typically increasing as the investment pool increases.
This is true as we move from retail to high-net-worth (HNW) investors and then to UHNW and large endowment pools of capital. The driving force behind the often-low allocation towards alternatives appears to be a lack of familiarity, particularly among retail investors, and liquidity constraints. There are also questions of scale and access to investment opportunities.
Endowment funds, however, now have a long track record of investing with high allocations to alternative assets. We have also identified a reduced home country bias within the equity allocation of endowment-type asset allocations, as investors are able to focus on maximising returns, rather than matching liabilities in their domestic currency.
Maximising return for a given level of risk
Crestone’s asset allocation process begins with the formulation of five-year forward-looking expectations of return and risk for each asset class, as well as the expected correlations between those asset classes. Quantitative analysis then helps drive the efficient frontier, which is the subset of all possible portfolios, which maximise return for a given level of risk. It is at this stage that we traditionally impose constraints on the types of portfolios that we want to look at. For example, we impose:
- a minimum cash holding to provide some operational liquidity
- a minimum domestic equity holding since most investors have liabilities denominated in Australian dollars, and
- a maximum weight to alternatives to avoid building overly illiquid portfolios.
Asset allocations can then be developed according to the investor’s risk tolerance.
The efficient frontier maximises return for a given level of risk
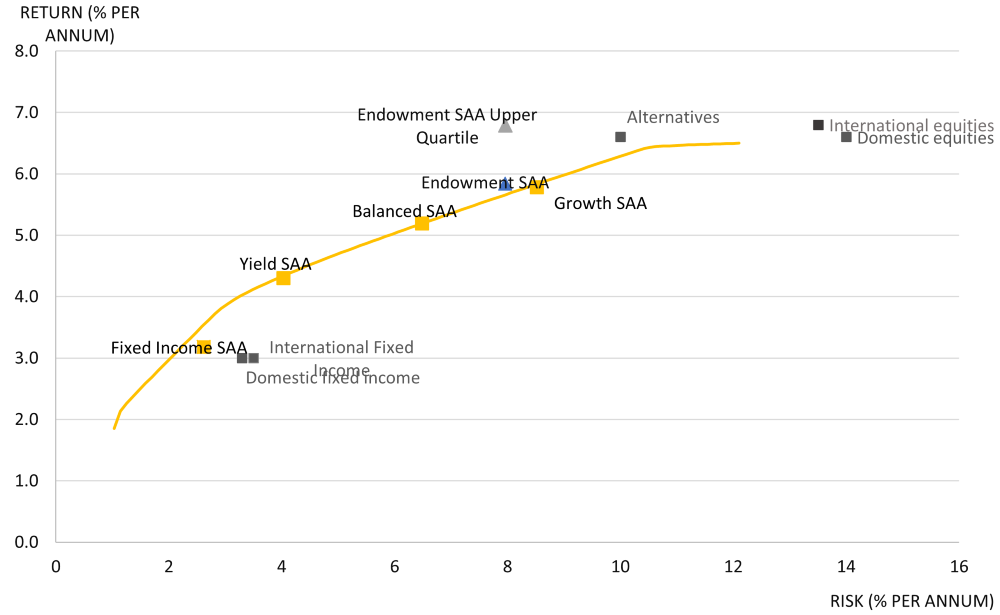
Source: Crestone Wealth Management. Data as at October 2020. SAA is Strategic Asset Allocation.
What happens as we ease constraints?
As we ease those constraints, the model pushes for an increased weight in alternative assets at the expense of other asset classes, and a reduced weight in domestic equities via an increased weight in international markets.
In the case of a growth investor, where the typical cap on alternatives is 20%, the portfolio’s allocation to alternatives might move towards 40-50%. This is an uncomfortable level for most investors in what is a comparatively illiquid asset class.
However, some investors, typically those who are unconstrained and have a large pool of capital to deploy, are both willing and able to bear that additional illiquidity and are, therefore, able to construct more efficient portfolios. An increased allocation to alternative assets has a number of advantages at the portfolio level. The imperfect correlation with traditional assets helps to reduce portfolio volatility and the higher expected return helps increase overall portfolio return, thereby improving the expected risk-adjusted returns of the portfolio.
For Australian investors, the second major shift we see as we move towards an unconstrained allocation is a greater holding in international equity markets relative to the domestic market. This is a function of a reduced need for liability matching within the portfolio, facilitating a larger weight to a greater variety of exposures (and therefore return drivers) that are available offshore but not in Australia.
It also allows for a greater allocation to emerging markets, which are expected to be a key return driver in today’s low growth environment. However, the correlation of domestic equities with international equities, particularly on an unhedged basis, means that domestic equities will generally hold a greater weight in a portfolio than a simple market cap weight would suggest.
The case for alternatives
Various studies have found that increased allocations to alternatives, as pioneered by some of the large US endowment funds such as Yale, have delivered superior risk-adjusted returns. Our research finds the typical alternatives allocation ranges from 44%-72%, while Frontier research shows that US endowment funds greater than USD1 billion in size have outperformed traditional portfolios by 1-2% per annum on average across various time periods.
The reason behind this outperformance is multi-faceted.
The most obvious improvement in the risk-return outcome stems from the low correlation between alternatives and other assets in the portfolio, which reduces overall portfolio volatility (traditionally used as a measure of risk). There is also a return benefit to be gained from holding less liquid investments, the so called illiquidity premium, which is essentially the return amount in addition to that provided by a liquid equivalent.
For example, part of the outperformance of private over listed equities would be attributed to the fact that private equity is less liquid than the listed equivalent. From a practical standpoint it is also true that alternative markets tend to be less efficient than traditional markets, meaning that there are more opportunities, and greater reward, available to savvy investors.
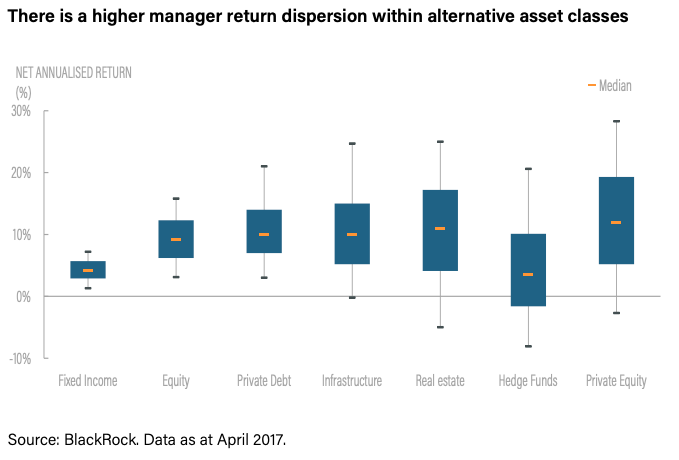
The potential for outperformance in alternatives is far greater than in traditional asset classes, making it much more important (and rewarding) to be able to identify and access the best managers. BlackRock research shows that manager return dispersion within alternative asset classes is three to five times higher than for traditional asset classes, making the rewards for being able to identify (and access) the top-performing alternatives managers much greater than for traditional asset classes.
Is an endowment style right for you?
For investors who have the scale, long-term investment horizon and lack of liquidity requirements, it makes sense to implement an asset allocation that can take advantage of a lack of constraints.
However, the ability to identify high quality managers and strategies within the alternatives space is of key importance. Therefore, while adjusting public equity exposures may be relatively straightforward, when implementing an increased weight to alternatives, a more patient approach is required. This experience mirrors that of some of the largest investors, with the Future Fund a good local example. Here, the alternatives allocation currently sits at around 45% but this has progressively been built out over the last 12 years, with just a 10% allocation back in 2008.
Although asset allocation methodologies are generally consistent across investor types, as investors seek to maximise risk-adjusted returns, the optimum asset allocation will vary according to the investor’s specific requirements.
By observing how some of the largest investors in the world build their portfolios and by studying the performance outcomes, we find both evidence of these asset allocation skews and that the resulting portfolios have delivered superior performance outcomes when compared to more traditional asset allocations. This suggests that those investors who are able to adopt an endowment-style of investing would benefit from doing so.
Rob Holder is Asset Allocation Specialist at Crestone Wealth Management. This article is general information and does not consider the circumstances of any investor.