Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 562

What poker can teach us about investing

It’s 2014 at the end of Super Bowl XLIX with 26 seconds left. The Seattle Seahawks were down by four points against the New England Patriots. The Seahawks were on the Patriot’s one-yard line just outside the end zone and it was only the second down1. It was a golden opportunity for the Seahawks to snatch a victory.

Seahawks coach Pete Carroll called a timeout and told his quarterback to pass the ball instead of making a running play. The quarterback passed. But the Patriots intercepted the ball, and the Seahawks lost a game that they looked like they were about to win.

Coach Carroll was crucified by fans for the passing decision. Many see it as the worst call in Super Bowl history, perhaps all of NFL history!

But was it a bad decision?

Former World Series of Poker Champion and cognitive behaviour expert, Annie Duke, thinks not. In her book ‘Thinking in Bets: Making Smarter Decisions When You Don’t Have All the Facts’, Duke highlights that, based on 15 years of NFL data, the probability of a short pass interception is below 2%.

The Seahawks were much more likely to score a touchdown or make an incomplete pass that would have barely used any clock time (and doesn’t count as a down).

If a touchdown results, you’re a genius who won the game doing what the opposition didn’t expect you to do. While an unsuccessful running play loses precious time off the clock and only allows time for one more play.

Just because the low probability event happened (an interception), it doesn’t make it a bad decision by the coach. Duke sums it up nicely:

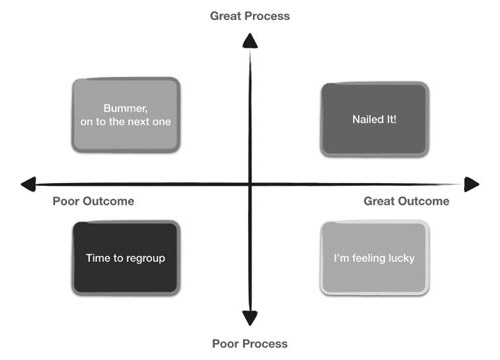
“What makes a decision great is not that it has a great outcome. A great decision is the result of a good process, and that process must include an attempt to accurately represent our own state of knowledge.”

The takeaway: in games where there is chance, and the probabilities aren’t certain (i.e. 100%), you can’t judge a decision by a result.

So-called ‘resulting’ is what poker players call the tendency to judge a decision based on its outcome rather than its quality. Investors need to avoid ‘resulting’ at all costs.
Two decades of trusting our process

At Ophir, we are highly focused on the ‘process’ principle at the portfolio level.

As long-time readers will know, we (Andrew Mitchell and Steven Ng) started out as Australian small-cap investors around 15-20 years ago. Then, as our most successful ‘Aussie’ investments increasingly became global as they expanded overseas, we launched into global small caps some six years ago.

Through that time, the ideal company in which we invest has not changed. It is typically A$500 million to $10 billion in market cap, growing revenue and profits above the market (so generally 10%+ per annum), taking market share, and growing into a big end market wherever that is in the world.

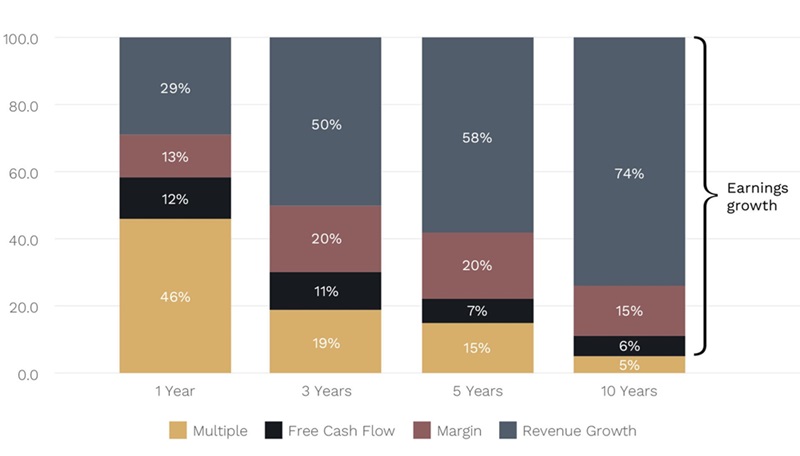
We strongly believe, and the evidence backs it up, that earnings drive company share prices in the long term. You can see this in the chart below where revenue growth, changes in margins and free cash flow all add up to earnings growth, which dominates as the driver of share market returns over time. And providing you don’t overpay for that above-average earnings growth, you give yourself a great chance of generating attractive investment returns and beating the market averages.

Key drivers stock performance – S&P 500 (1990-2009)
Source: Morgan Stanley Research

We also believe that one of the best indicators of above-average earnings growth over the longer term is strong earnings growth today that is beating market expectations.

If you were a fly on the wall in our investment team meetings, you would hear us focussed on how confident we are that our portfolio companies are likely to beat the market’s expectations for revenue and profit growth at their next result.

This, however, doesn’t guarantee you good investment returns in your portfolio in the short term. Changes in valuation multiples (yellow bar above), both at a stock and portfolio level, can swamp the fundamentals of revenue and earnings growth.

This was particularly the case in late 2021 to mid-2022 in our funds, and in particular our Global Funds, where despite still overwhelmingly getting the earnings right, valuation multiples decreased to a degree not seen since the GFC for the entire cohort of small-cap growth-orientated businesses globally, which is of course the pond that we fish in.

Why we’re happy with this process … despite

But we are also focussed on the ‘process’ principle for individual holdings, as the example of Altium shows.

Altium (ASX:ALU) is an Australian stock we held last year in the Ophir High Conviction Fund (ASX:OPH). It makes the most widely used software for the design and manufacturing of printed circuit boards.

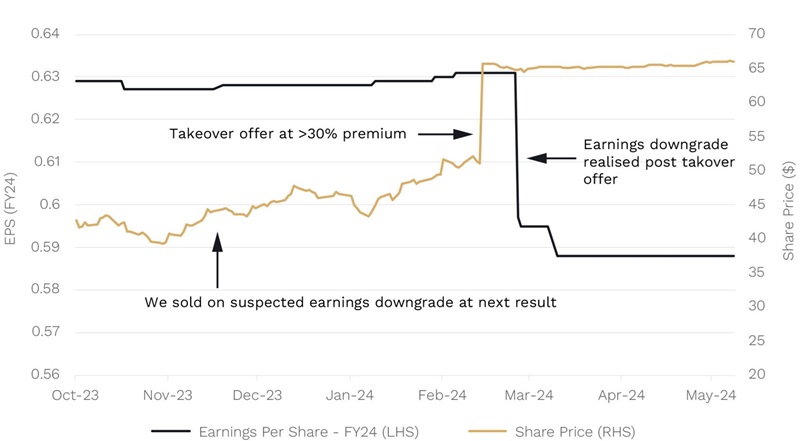
But towards the end of 2023, one of our analysts warned us there was going to be an earnings hole at the first half 2024 result due in February 2024.

If we are highly confident an earnings miss is looming at an upcoming result, we will either down-weight the position or sell to zero. In this case the instruction was clear: get out entirely!

Just weeks later, in mid-February, Japanese chipmaker Renesas Electronics lobbed a takeover bid for Altium at $68.50 – a circa 34% premium to the closing price of the company’s shares the day before, valuing the business at A$9.1 billion in an all-cash deal.

Our analyst was livid and there was definitely a few swear words in the office! We had lost the chance at significant outperformance by selling the stock early.

Were we (Andrew and Steven) upset at the lost performance opportunity? No!

The reason is simple: The analyst did all the correct work, as part of our process and made the right call with the information they had at the time.

We will never hold onto a company because a takeover offer might be lobbed – the probability is usually just far too small and uncertain.

Low and behold, in late February when Altium came out with its result, it reported a big miss to earnings, that, but for the takeover offer, would normally have seen the stock fall upwards of -30%.

Altium (ALU) share price and earnings
Source: Bloomberg

Our analyst made the right call based on the percentages – a recommendation to sell Altium based on a likely upcoming earnings miss – and this isn’t invalidated due to a small-probability left-field takeover offer effectively rendering the earnings miss meaningless.


1 For non-NFL fans, in American Football you get four attempts to move the ball at least 10 yards up the field. The first of these tries is “first down”, the next “second down” and so on. Once they make it 10 yards or further the downs reset and it’s back to first down.


Andrew Mitchell and Steven Ng are co-founders and Senior Portfolio Managers at Ophir Asset Management, a sponsor of Firstlinks. This article is general information and does not consider the circumstances of any investor.

Read more articles and papers from Ophir here.


  •   29 May 2024
  • 6
  •      
  •   
6 Comments
Rafael F
May 30, 2024

Resulting is rife, and it's not only in the share market and in sports. Some very rich people played 1000 to 1 odds and won, while some not so rich played much better odds and lost. But that's not what people assume. The key is to play when the odds are stacked in your favour, not run out of money when you lose, and keep repeating the process until you eventually win and win big.

Andrew Mitchell
May 31, 2024

Good points Rafael! Always be careful calling someone a genius when they win and the odds are stacked against them or an idiot when they lose but the odds were in their favour.

Jordan M
May 31, 2024

Thanks Andrew. Do you take the odds of a takeover into account when analysing a stock? Seems a lot of M&A is happening, but how you assess the probabilities is the question...

Andrew Mitchell
June 03, 2024

Outside of a few special situations generally not. The types of businesses we tend to invest in (growth at a reasonable price) don't tend to get bid for that much. We'd rather focus where our skill set is in identifying companies where growth trajectory is mispriced.

Steve
May 31, 2024

It is possible to shift the odds in your favour. Example roulette. Roughly 50/50 chance of red or black (the green number "0" gives the house an edge). Payout is 1 to 1. Some people simply double up if they lose and keep doing until the red or black they are betting on "inevitably" comes up. $1, $2, $4, $8 etc. When you win you recover all your accumulated losses and have the initial sum bet as a profit. Reset and repeat. Why doesn't this work in the real world? Casinos have table limits which prevents never ending doubling. Of course the bigger the initial bet, the larger each subsequent bet. Casinos also ban people who win too often! But it shows that if you can place enough bets on something with a predictable outcome (ie always a 100% payout when you do eventually win in the above example) then you can reduce the risk of losing.

Andrew Mitchell
June 03, 2024

Interesting Steve - been a looong time since I've played roulette. Law of large numbers sees betting against the house a tough proposition at scale!


Leave a Comment:

RELATED ARTICLES

Why strong returns matter as much as generosity

The catalyst for a LICs rebound

What super funds and their fund managers now think

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.