Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 379

When defensive assets become indefensible, turn to tech

The appeal of owning traditional defensive assets of any type is currently less than in almost any other period in history. In fact, in this extremely low rate environment, we are seeing just how unattractive traditional defensive assets can become. 

But despite the serious headwinds facing defensive assets, investors started moving billions into these safe havens well before COVID-19 struck, as many feared equity markets were toppy and it was late in the economic cycle. This may have proven a saviour for some investors in March 2020.

A redefinition of what is defensive

In the flight to safety, many investors took their medicine even though the cash rate was at an historic low, term deposits above 1% were rare and incomes from investment grade bonds had plummeted. The riskier high yield bonds broadly tracked the share market which calls into question their raison d'être as they do not have the desired defensive qualities in a downturn.

With income generation previously a major drawcard for a defensive allocation, many investors have realised they can no longer rely on an income of 5-7% a year and are having to rethink their future. Or at least change their investment strategy.

It is time for investors to broaden their approach to defensive investing and take a closer look at defensive sectors, rather than just the asset class.

To look only at defensive asset classes is a narrow view of the investment universe. This fails to take into consideration one critical factor that impacts the success or failure of the underlying companies, and that is the sector in which they operate.

For those more sophisticated investors who already take a sector approach to portfolio construction, it may also be time to look outside the usual suspects of consumer staples, healthcare and utilities, where demand for these goods and services are relatively inelastic and as a result they perform relatively well in a downturn.

Technology has joined the defensive club

During this pandemic and early days of the economic recession, we are seeing a surprising new entrant to the defensive sector grouping. Technology shares have been behaving a lot like defensive shares such as food and utilities.

The S&P/ASX 200 is down 12.6% since February 2020, while the S&P ASX All Technology Index, a broad index of technology companies, is up 30%. Over the same period, the S&P500 is up nearly 8%, while the NASDAQ, the home of many technology companies, is up over 25%. This is not a fluke. See the chart below for a comparison between the NASDAQ, S&P 500, and DJIA.

DJIA v S&P 500 v NASDAQ
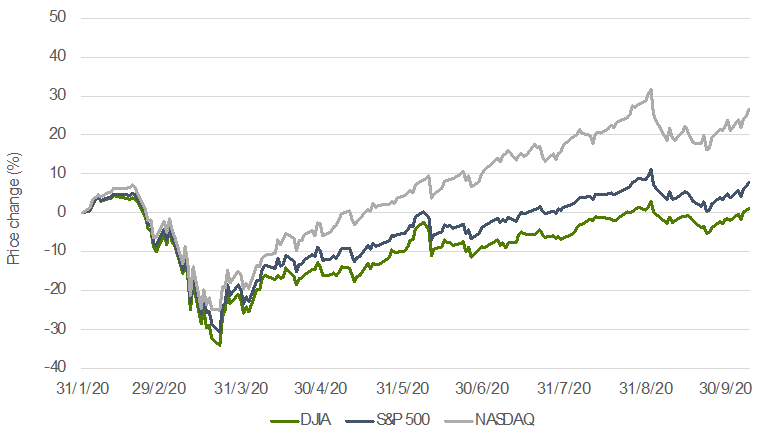
Source: S&P Global

Technology is holding its own and providing investors with a defensive position in this time of great uncertainty, with the NASDAQ fuelled by the strong revenues and forecast growth rates of many of its technology companies.

The reasons are plain to see, not least because technology has been the lifeline for individuals and businesses during lockdown. In the US, a recent Fortune 500 CEO poll found that 75% of companies plan to increase spending on technology.

So while the NASDAQ suffered a fall in September due to investors reducing their valuations for companies such as Apple and Tesla, and further exacerbated by the number of equity derivates involving both retail investors and SoftBank, the index has stabilised (and recovered) recently. Their traditionally higher valuations can be attributed to drivers such as high margins, growth rates and their ability to be agile in adapting to consumer and businesses changes caused by COVID-19.

History has proven that technology thrives on shocks. These are events that are, by and large, unexpected and bring out changes in real economic growth, inflation and unemployment.

There has been no greater shock in a generation than COVID-19. This is a shock that will have lasting effects and technology will exacerbate the impact on certain sectors and force changes that allow businesses to survive. COVID-19 has accelerated innovation in sectors including ecommerce, cloud computing, gaming, streaming and remote communication such as videoconferencing.

Technology is a deflationary force

Investments in technology by companies are made to reduce costs, increase profits and improve efficiencies. It is difficult to imagine that any business will reject technology that enables them to produce more product, more quickly and ultimately make larger profits.

Investors are already shifting away from the today’s sunset industries and hedging with investments in technology. As a resource economy, it has been difficult to avoid investing in large mining companies but the shape of our economy is changing. Some commentators have suggested that COVID-19 has hastened the slow passing of the oil age and is driving an increasing focus on sustainability generally. Technology drives this sustainability.

Investors taking stock of tech opportunities

Investors will undoubtedly be taking stock and assessing their investment portfolio as the world waits and watches to see what happens next in these strange times. With tech shares currently trading at high multiples, we can expect investors will look across the spectrum of tech investment opportunities. Venture capital funds are sought after as investors seek exposure to early stage tech businesses in what is ultimately a long-term game plan.

Technology has never been more important. This holds true in daily lives, in business and in the global economic recovery. When times are tough, corporates slash procurement costs, automate procedures and optimise back-office efficiencies. Technology delivers on all of these fronts. In better times, we can expect to see high growth tech businesses continuing to innovate and bring new products to consumers and business.

With a greater focus on defensive sectors rather than poor-performing defensive asset classes, investors may just be able to have their cake and eat it. A strategy that is both high growth yet defensive, supporting economic recovery and creating an economy of the future.


Benjamin Chong is a partner at venture capital firm Right Click Capital, investors in high-growth technology startups. This article is general information and does not consider the circumstances of any investor.


  •   14 October 2020
  • 5
  •      
  •   
5 Comments
Alex
October 14, 2020

Never thought I'd see the day when growth stocks with P/E north of 30 were called defensive. May they grow forever, or until they are themselves disrupted. TikTok anyone?

Brett
October 14, 2020

It's one thing to explain the benefits of a sector, like Tech. To claim this sector is a defensive by handpicking one example to make your point is concerning. Tech in 2000 underperformed; tech underperformed the initial recovery from the GFC - it all depends on the circumstances (a pandemic forcing people to stay home is obviously tech friendly).

Tech investments, to use your examples Apple and Telsa, sell products that are non-essential. Therefore, at some point in the future the earnings of these companies will likely act in a non-defensive manner. Utilities and healthcare are essential items that have provided relatively more stable earnings profiles.

I'm not discounting your ability to pick great investments within the sector. I disagree with your claim that the entire sector is a defensive asset.

Brendan
October 15, 2020

Couldn’t agree more. Well said.
The article read more like a sales brochure than analysis.
Be good at what you do, but don’t pretend you’re something you’re not.

Vince
October 14, 2020

Technology is the future and the future is here. The dot com bust in 2000 happened in my view, because tech wasn’t yet mature. Just look around and you can see technology is entrenched in just about everything we do. However, there will be winners and losers. That’s just natural.

Trevor
October 17, 2020

This honestly reads like a VC sales pitch and is a poorly thought out thesis about defensiveness being intrinsic, whereas it is so more likely incidental. Tech is not intrinsically defensive, it was incidentally defensive because of the particular circumstances created by this very particular crisis. The pandemic itself was tech friendly, retail investor mania has fuelled their price growth called and cheap money and MMT has been highly supportive of the sector. If you are relying on money printing, low rates, retail mania and everyone locked up at home for a stock to be defensive, than good luck in the next crisis, which will have its own flavour. Let's see how these stocks fare in a crisis induced by taking the foot off the monetary pedal or indeed anything that hits momentum.


Leave a Comment:

RELATED ARTICLES

The most important investment decision you’ll ever make

Clime time: Asset allocation decisions for SMSFs

The 60/40 Portfolio – saying bye to old friends and welcoming new ones

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.