Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 381

Why caution is needed in Aussie small companies

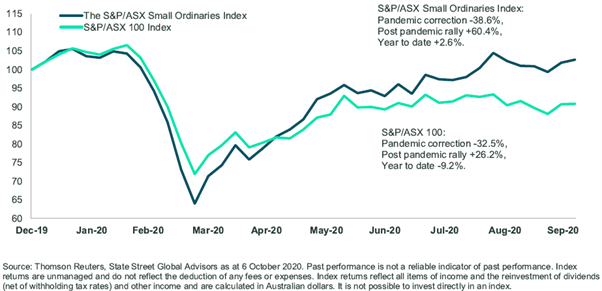
Small capitalised companies have had a great run since the market bottomed in late March. The S&P/ASX Small Ordinaries Index is up 60% since 24 March 2020, but by contrast, the larger capitalised companies as represented by the S&P/ASX100 index are only up 26.2% (as at 6 October 2020).

The significant outperformance of smaller companies has ignited renewed interest in this sector of the market. Figure 1 shows the two indexes since December 2019.

Figure 1. A wild ride in equities and even wilder ride in smaller companies
Greater returns but with more volatility

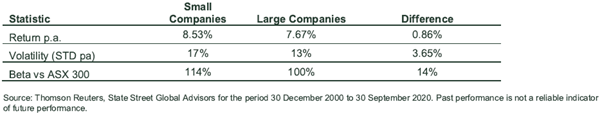
Over the last 20 years, smaller companies have outperformed larger companies by almost 0.86% per annum but this outperformance has not been without risk. On average, the volatility associated with small companies is 17% compared to larger companies with 13%.

This is also evident in the beta (a measure of volatility in terms of the overall market, which has a beta of 1 or 100%) of the small company index averaging 114%, as shown below.

Figure 2. Longer term return and risk characteristics from Australian small and large companies
Smaller companies have had a great run in the last six months but a look at the long term puts that outperformance into some context.

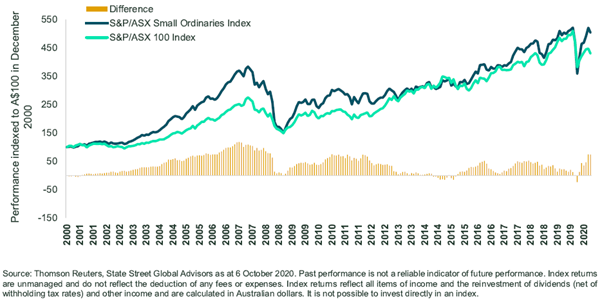
Figure 3 illustrates the journey for the last 20 years. Smaller companies have had periods of significant outperformance, which are historically followed by periods of underperformance. Depending on when you invest, your experience could be quite varied.

Figure 3. Periods of outperformance have historically been followed by periods of underperformance
Valuations are rich in absolute and relative terms

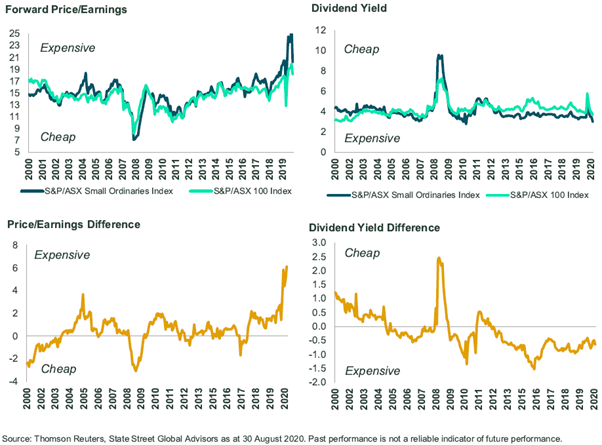
On average, over a longer period of time, we find the smaller capitalised companies tend to trade at a slightly higher price to earnings (P/E) multiple and generate slightly lower yields. But this tends to be volatile, as during risk-on periods they can trade at much higher multiples, whereas during risk-off periods, they can trade at below average multiples.

It is entirely possible that the economy will recover and many company earnings will return to pre-pandemic levels, but if they don't, then the small company sector of the market is more at risk of disappointment. From a relative yield perspective, the smaller companies are not as expensive as is implied by earnings multiples.

Figure 4. Smaller company valuations
Watch out for overly optimistic earnings

For smaller companies compared with larger companies, the investment community is usually overly optimistic on earnings. In the last 20 years expected growth for the next 12 months has averaged +21.1% and yet on average this group of companies has only delivered +13.2%. By contrast, the expected growth for larger companies is expected to be lower at only +9.4% and has only delivered +6.8%. It's a much smaller earnings disappointment compared to smaller companies. In both cases, analysts’ expectations have been overly optimistic but in the case of smaller companies, this optimism is exaggerated.

As investment managers that focus on quality, value, improving outlook and lower volatility, we tend to invest in less volatile companies that have not been priced for excessive growth. That does not mean we will not invest in smaller companies if they are expected to provide the right mix of return for risk.

Indeed, as Figure 5 below highlights, we currently own many companies outside the top 50 but within the top 200, but our active weight in these companies changes.

Figure 5. State Street Australian Equity Fund – Active weight to different sized companies since inception^
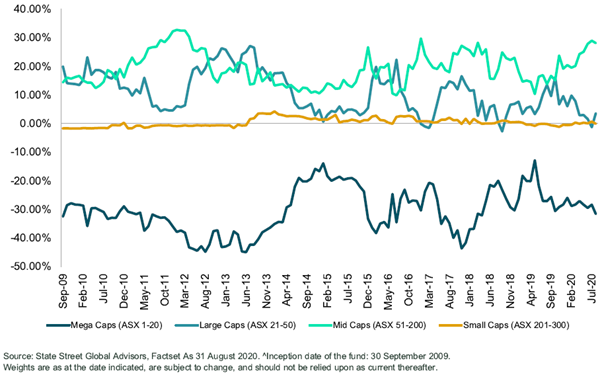
 

Currently, valuations are stretched for the market and are especially stretched to the smaller end of the index. Most of this has happened in the last six months as investors have been willing to price a strong recovery in earnings.


Bruce Apted is the Head of Portfolio Management – Australia Active Quantitative Equities, at State Street Global Advisors. This general information has been prepared without taking into account your individual objectives, financial situation or needs and you should consider whether it is appropriate for you. 


  •   28 October 2020
  • 1
  •      
  •   

RELATED ARTICLES

Has passive investing killed small caps?

Why the ASX is losing Its best companies

Australian shares struggle as 2020s reach halfway point

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.