Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 453

Age pension is increasing: what you need to know

Australia’s age pension rose in March reflecting rising inflation and the growing cost of living pressures. This represents a pay rise of just over 2% and is the biggest increase in the payment in almost a decade.

Single pensioners will be $20.10 better off per fortnight, and couples up to $30.20 per fortnight (where both members of the couple are eligible).

Indexation also means that some people who were previously ineligible for a pension may become eligible as the cut-off amounts of assets and income are also increased.

But older Australians receiving aged care need to know that an increase in the pension also means an increase in their Basic Daily Fee. This means they’ll only see $4 of the $20 pension increase.

In this article, we’ll walk through the changes step by step and what they mean for you.

Payments

The maximum rate of age pension payment for singles increased by $20.10 per fortnight from $967.50 to $987.60. The maximum rate for couples increased by $15.10 each from $729.30 per fortnight for each eligible member to $744.40.

A couple where both members are eligible to receive the maximum payment can receive $1,488.80 per fortnight or $38,708.80 per year combined.
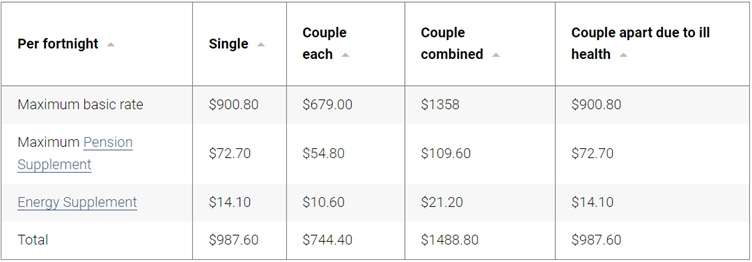
Source: Services Australia

The assets and income level before pensions are disqualified under the means tests have also increased.

Assets

For homeowners who are single, the asset test cut-off increased from $593,000 to $599,750. For couples it increased from $891,500 to $901,500.

For couples who are separated by illness, as is the case when one or both move into aged care, the cut-off increased from $1,050,000 to $1,063,500.

*It’s important to remember that the value of your home is not included in these assets.

Income

For singles, the amount of income you can earn before the age pension ceases has increased from $2,115 per fortnight to $2,155.20. For couples, the cut-off has increased from $3,237.20 per fortnight to $3,297.60.

*It’s important to remember that income earned under the work bonus (up to $7,800 per year) is not included. Income from investments is based on deemed income, rather than the actual income earned.

In announcing the changes Minister Anne Ruston said, “This is putting money in the pockets of all Australians who rely on our social security system and, in particular, older Australians.”

But older Australians receiving aged care, whether that’s a Home Care Package or residential aged care, need to know that an increase in the pension also means an increase in their Basic Daily Fee.

The Basic Daily Fee you pay towards your cost of aged care is set based on a percentage of the Age Pension. In a Home Care Package, the maximum Basic Daily Fee is set at 17.5% of the basic Age Pension (and applies to people on a Level 4 Package) it was $11.02 per day and has increased to $11.26 per day from 20 March.

In a Home Care Package, the Basic Daily Fee is based on the level of your package:

  • Level 1 was $9.88 per day increasing to $10.08
  • Level 2 was $10.44 per day increasing to $10.66
  • Level 3 was $10.74 per day increasing to $10.97
  • Level 4 was $11.02 per day increasing to $11.26

So, if the fortnightly pension increases by $20.10, up to $3.36 will be needed to meet the increased cost of a home care package.

In residential aged care, the Basic Daily Fee is set at 85% of the basic Age Pension, it was $53.56 per day, increasing to $54.69.

This means that the Basic Daily Fee increase is $15.82 a fortnight, so of the extra $20.10 in Age pension, people living in aged care will only have $4.28 per fortnight to cover increases in their cost of living.

While the Basic Daily Fee does cover some of the cost of living in aged care such as meals, utilities and insurances, many aged care residents need to pay extra or additional service fees to cover alcohol, food, entertainment, and personal services. Personal expenses such as clothing, medications, health care, other insurances, transport, and communication costs remain the responsibility of the resident.

A $4 per fortnight increase in the Age Pension for people living in aged care is definitely a pay cut, not a pay rise.


Rachel Lane is the Principal of Aged Care Gurus where she oversees a national network of adviser dedicated to providing quality advice on retirement living and aged care. She is also the co-author of a number of books with Noel Whittaker including the best-seller 'Aged Care, Who Cares?' and their most recent book 'Downsizing Made Simple'. To find an adviser or buy a book visit www.agedcaregurus.com.au.


  •   6 April 2022
  • 2
  •      
  •   

RELATED ARTICLES

12 tips for ‘aged care season’

Biggest change in the Aged Care Interest Rate since the GFC

Recent age pension changes impact non pensioners too

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.