Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 108

Feeling lucky? Another stock market spike in China

So far this year we have seen good returns from all asset classes (except cash), in Australia and globally. Shares are fully priced or over-priced but they are still doing better than their long term averages. Likewise with listed and unlisted real estate. Bonds are horribly over-priced but they too have generated above average real returns.

In a world where everything is doing well for investors something is bound to go wrong. It is impossible to over-weight (or under-weight) everything in portfolios so it calls for tough decisions. How long can the great 2012-15 QE rally last?

Here is a close look at the incredible spike in the prices of Chinese stocks in the last year, linked back to the perennial culprits – banks and the credit cycle.
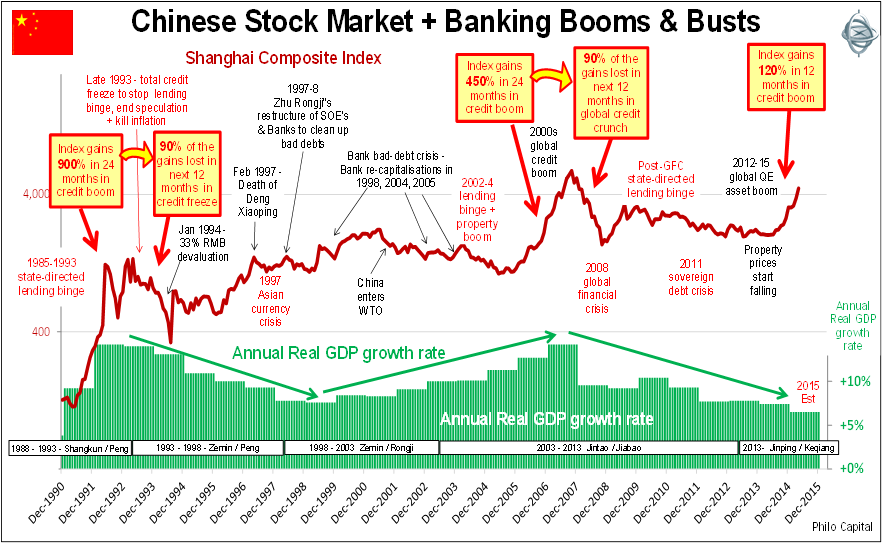
The Shanghai index has shot up 120% in the past 12 months after five years of falls. Less well known is that this is a rather mild spike compared to past episodes.

There have been two great stock market spikes in post-1949 China. Both were fuelled by credit binges and both promptly crashed when credit dried up. In 1991-1993 the index gained 900% in 24 months but then lost 90% of the gains in the next 12 months. In 2006-2007 the index gained 450% in 24 months, but also promptly lost 90% of the gains in the next 12 months.

There was an orgy of bad lending in the 1985-1993 credit binge by the big Chinese state-owned banks. To end the party the government had to impose a total freeze on lending in late 1993. That crunched asset prices, employment, the economy and the banking system, and it took the next 12 years to clean up the mountain of bad debts in the banks.

As soon as it did, the next great credit/property/stock market bubble took off in 2006-2007, fuelled by cheap credit and geared-up local and global investors chasing the ‘China growth’ story. The boom ended in a crash in 2008 when credit froze as the global banking system seized up.

In the ensuing global financial crisis, the Chinese government embarked on a massive spending and credit spree to support the economy. The bubble re-appeared firstly in housing and then moved on to shares last year when housing prices started to fall. Driving the current boom are cashed-up first-time local punters, many using margin debt, and the spike is now being chased by foreigners eager to get in on the action.

The current stock market rally is quite modest by comparison to past bubbles and pricing levels are still not stretched – for example price/earnings ratios and dividend yields are not outlandish. The market may run up a lot further from here but banks are hiding another mountain of bad debts built up in the post-GFC lending binge, and so this boom will probably end the same way as previous episodes.


Ashley Owen is Joint CEO of Philo Capital Advisers and a director and adviser to the Third Link Growth Fund. This article is educational only. It is not personal financial advice and does not consider the circumstances of any individual.


  •   8 May 2015
  • 2
  •      
  •   
2 Comments
Jerome Lander
May 08, 2015

There are a lot of Chinese stock promotors who will be making a fortune from this "government-blessed" equity rally and indeed "feeling luck"! The market is still treated like a casino by Chinese locals and short term speculation is running hot currently in the expectation of strong short term gains. It is a not a good market for long term index investors (what is these days!).

Australia's own Bronte Capital (global long/short manager) is well known for exposing examples of fraudulent Chinese stocks previously. It is absolutely imperative to understand who and what you are investing in there.

Chris
May 14, 2015

Absolutely Jerome, I could not agree more !

I have very close Chinese friends and some of them treat the stockmarket as a casino, speculating in companies they know nothing about, and if it goes up, they think it is because "they are lucky (as though they played a game well)" (they just don't know how ironic that statement is - it was blind luck)

There was also an interview in the April 2015 edition of AFR Smart Investor re: a firm that had uncovered some shocking Chinese fraud.

The joke is that the SEC could have done something against NYSE listed Chinese stocks when they found that some of them had been less than truthful, but didn't. Getting real information out of China is extremely difficult because most of the companies are SOEs and therefore, anything that the Party believes is a "State Secret" will not be released (including real financial data).

How on earth you are supposed to make an accurate investment decision in that environment is beyond me. As a long-term investor, the best that I can hope for is an ETF that covers Chinese stocks and as a part of an overall strategy (I use iShares IAA and IEM), because I sure wouldn't individually pick them nor put all my Asian exposure onto China.


Leave a Comment:

RELATED ARTICLES

Are Chinese investors still on training wheels?

Why China’s property market matters

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.