Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 482

5 charts that should give investors hope amidst market turmoil

It’s understandable if investors are a bit shell-shocked.

Central banks around the world are hiking rates in an attempt to slow spending and lower stubbornly persistent inflation. The turmoil's impact on asset valuations has been stomach churning for investors. Nothing has been spared – from equity markets, bonds, property, FX, to crypto.

Investors are probably wondering when the turbulence will end.

Some perspective may provide solace

Given that, we take a step back and look at five key charts that help provide some perspective and context on the current environment for investors.

The good news is the charts provide some hope that we could be reaching some form of an inflection point in the outlook for the economy (particularly surging inflation) and for listed company valuations.

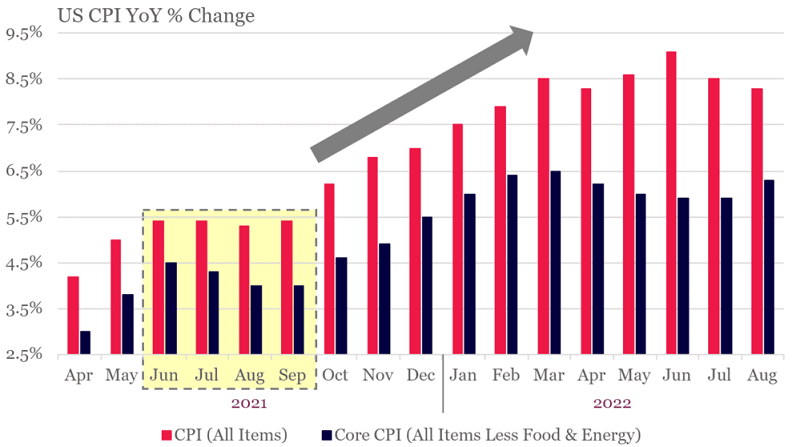
1. Inflation growth may start to moderate from October 2022
Source: Bloomberg, Montaka Global

As mentioned, the root cause of the current market dislocation is the relentless march toward higher inflation.

When might we see inflation moderate and a subsequent ‘pause’ by central banks in their aggressive interest rate increases? Interestingly, this moment may be mere months away.

If we look at the Consumer Price Index (CPI) this time last year in the chart above, we see a relatively flat path of inflation through September, then a sharp acceleration in the following months starting October.

Since inflation is typically viewed as the rate of change over a 12-month period, this substantial uptick starting in October 2021 means that the year-on-year growth of inflation in October 2022 is going to become increasingly challenged.

Said another way, this simple mathematical reality may lead to a more benign CPI print when the October number is reported on November 10, and potentially for several months subsequently.

This date is certainly worth marking in the calendar. It may be a turning point in how aggressive central banks, particularly the US Federal Reserve, will be in raising interest rates and could pave a path to more rational price discovery in markets.

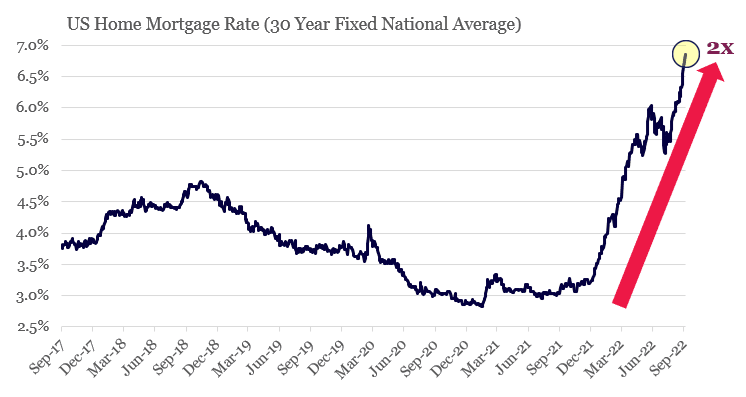
2. US mortgage rates have more than doubled in 2022
Source: Bankrate.com, Montaka Global

The strength of the consumer is often sighted as a key driver of inflation. Indeed, despite sharp interest rate hikes by central banks, they don’t seem to be putting a dent in consumers’ voracious spending habits.

However, laying beneath the surface of a ‘strong consumer’, is the potential for sharp belt tightening around household budgets. This year alone, mortgage costs have doubled, which means a family that was considering a $500,000 home last year, can only afford a $250,000 home today.

On average, mortgage payments – usually the largest single expense for a family – are around 30% of household income. If a family was required to refinance their home today, it would cost them double what it would have cost just 12 months ago. A family that was previously paying 30% of their household income towards their mortgage could see it rise to as much as 60% as mortgage rates have doubled. A family making $100,000 per year would see their post-mortgage cash flow drop from $70,000 to $40,000.

They very likely will cut back on discretionary expenditures, like travel, holidays eating out; and potentially also cut back on some non-discretionary items, like doctors’ visits and school fees. All of this is highly contractionary and would cause inflation to fall as consumers lower the amount of spending in the economy.

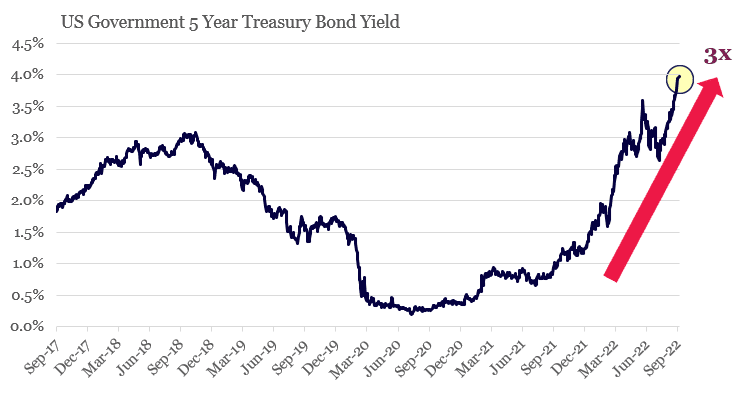
3. Cost of funds for the US Government has tripled in 2022
Source: Bloomberg, Montaka Global

Obviously not every household is going to have the misfortune of being in the situation described above, at least not in the immediate term.

However, one of the largest agents in the economy, the US government, is not so fortunate. Over the coming 12 months, the US government will need to refinance US$4 trillion of its US$31 trillion outstanding debt. That will result in an incremental increase in interest expense each year of around US$150 billion above what was budgeted for last year.

Over time, the entire US debt would need to be refinanced at higher interest rates which would present the US economy with a crippling US$1 trillion incremental annual headwind if rates remain where they are today.

These funds may come out of public services, infrastructure spending, schools, social programs or increased taxation. All of which would send a major deflationary force through the economy, offsetting inflation, but likely resulting in a recession as well.

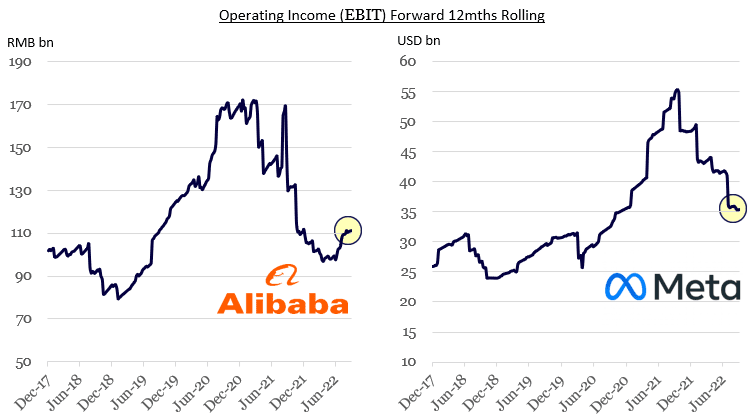
4. Earnings streams temporarily depressed
Source: Bloomberg, Montaka Global

Some of the most exceptional companies in the world are experiencing cyclical headwinds tied to macroeconomic conditions and changing business environments. They may also be embarking on major investment cycles that are depressing earnings.

These factors are expected to be temporary.

Examples include Alibaba, which is affected by the hard COVID lock-down policies in China, and Meta, which is investing heavily in Artificial Intelligence (AI) and navigating an evolving digital advertising landscape (Apple’s iOS changes).

It seems the market has dismissed the new opportunities these companies are building for the future. What are headwinds today will become tailwinds tomorrow. The price for substantial incremental cash flow generation has actually never been cheaper.

5. Depressed earnings attracting depressed multiples
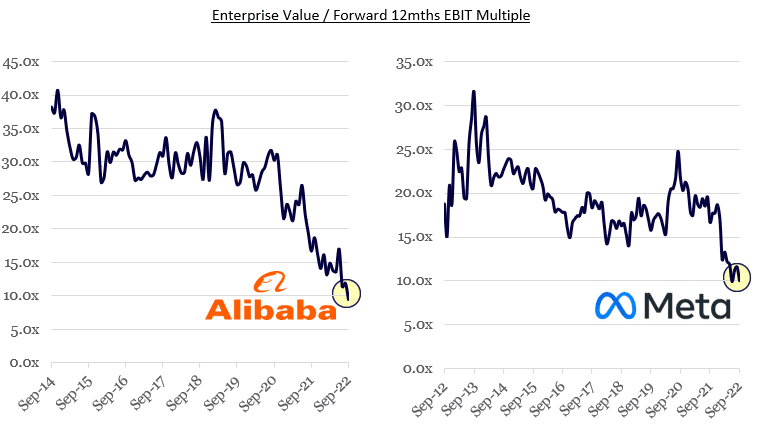
Source: Bloomberg, Montaka Global

Higher interest rates have compressed valuation multiples. But in the case of both Alibaba and Meta, the current environment is creating an outsized impact on them. Their valuation multiples are at post-IPO lows for both companies and imply the market believes the temporary depression in earnings is a permanent situation.

This has created a double whammy for these wonderful businesses: they are being priced on a depressed valuation multiple and depressed earnings expectations.

As multiples normalize and earnings decompress, valuations will likely hit an inflection point followed by a sharp re-rating in stock prices. This creates an extremely rare opportunity for an investor in today’s market.

Looking for opportunities

We believe the inflation-focused environment is creating some phenomenal opportunities in markets. As this major headwind recedes, as we believe it will, valuation multiples are likely to re-rate and reward the patient investor. In fact, Montaka Global has been using this opportunity to increase several portfolio holdings that appear to be significantly oversold.


Amit Nath is a Senior Research Analyst at Montaka Global Investments, a sponsor of Firstlinks. This article is general information and is based on an understanding of current legislation. Montaka owns shares in Alibaba and Meta Platforms.

For more articles and papers from Montaka, click here.


  •   2 November 2022
  • 5
  •      
  •   
5 Comments
Peter Voight
November 02, 2022

Agree on inflation. Not so much on Meta and Alibaba. Meta is making a huge bet on the metaverse - if it scaled that back and bought back shares, the stock would fly. But seems all in on the bet. Alibaba has the problem that China just isn't business friendly. The stock might get a bump when the country opens up but beyond that not so sure.

stefy01
November 04, 2022

Facebook is dying.
They have lost many millions of customers worldwide due to their heavy handed covid compliance policies over the last two years. These people have gone elsewhere and are not coming back.
There is very little I agree with in this article.

Dan
November 05, 2022

Point 3 refers to the US govts crippling debt funding cost. This interest is paid to the owner of the bonds (The Fed), who in turn pay dividends to treasury. These entire interest bill, less the cost of running the Fed, comes straight back to the govt. How is this crippling?

Dudley
November 05, 2022

~80% of USA Federal Government 'Debt Held by the Public':
https://fiscaldata.treasury.gov/datasets/debt-to-the-penny/debt-to-the-penny

Rob
November 05, 2022

Dan- You mistakenly assume the FED owns 100% of the US govt debt. The FED only owns approx.29% of the $31Trillion US Govt Debt, bought after the GFC and after Covid, to inject liquidity into the market/keep rates low/support asset values = Quantitative Easing or simply produce money from nothing. These were emergency measures ( buy US treasury Bonds and pay with money created out of thin air (i.e. not created by business/economic activity)).So with Fed sponsored interest rates rises, to fight inflation resulting from the Fed and US Govt over-- stimulatory emergency measures, the US Govt /Treasury budget deficit, must fund radically increased interest payments to non - US Govt owners of US Treasury Bonds (Japan and China the 2 largest, plus pension funds, insurance companies etc). The FED's plan is to reverse QE = Quantitative Tightening (QT) by letting expiring US Treasury Bonds it owns be repaid by the US Treasury or by selling UD Treasury Bonds in the open market, to withdraw market liquidity and support rate hikes to kill inflation. The market is assuming this process will not last too much longer and longer term inflation will be beaten. Said the Zen master " We will see"


Leave a Comment:

RELATED ARTICLES

War can’t be good, can it?

Where to from here after this year’s big tech rally?

The pros and cons of short-term versus long-term investing

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.