Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 335

APRA's executive remuneration changes are unwelcome

Australian Prudential Regulation Authority (APRA) is proposing to change remuneration requirements by de-emphasising the role that objective financial metrics play in determining executive compensation.

While well-intended, we believe the changes will have unintended negative outcomes which impact both investors and the wider public. We recently made a submission to ARPA outlining our concerns. We believe that rather than the proposed caps on financial performance metrics, 'active ownership' will ultimately see better outcomes for all stakeholders.

Background to the proposed changes

On 23 July 2019, APRA released for consultation a discussion paper, “Strengthening Prudential Requirements for Remuneration”. The new prudential standard on remuneration (CPS 511) will address recommendations from the Financial Services Royal Commission.

The core elements of the changes to CPS 511 are to:

  • Strengthen governance of remuneration frameworks and outcomes, in particular through an expanded Board role, where the Board needs to be active and have direct oversight.
  • Set overarching remuneration objectives that inform design of all remuneration arrangements and influence remuneration outcomes.
  • Limit the use of financial performance metrics (share price and profit-based).
  • Set minimum deferral periods (up to seven years) for senior executives to provide more 'skin-in-the-game' through better alignment to the time horizon of risk and performance outcomes.

Changes that will help improve the resilience of the financial system and alignment between the interests of financial institutions and those of shareholders, customers and beneficiaries, regulators and the broader community are welcome.

However, the proposal to limit the maximum weighting of financial performance metrics to 50%, and for this to apply to all employees, will have unintended outcomes on APRA-regulated entities.

Financial metrics are more tangible and objective 

We believe the majority of measures for both Short-Term Incentives (STIs) and Long-Term Incentives (LTIs) should be easily identifiable, measurable and relate directly to the company’s performance. Non-financial metrics do not meet these criteria.

Non-financial metrics include, for example, customer outcomes such as loyalty and complaints, reputation and trust, alignment with firm values, employee engagement, teamwork etc.

With these qualitative, non-financial measures, there is difficulty in ultimately devising the correct metrics for each firm. This can create confused incentives, often leading to perverse outcomes.

In contrast, financial metrics which include relative Total Shareholder Returns (TSR), are tangible and objective.

A prime example of a poor application of a non-financial metric was the CBA’s introduction of a ‘people & community’ metric in 2016. Absent of formal intervention by the Board in 2017, application of the ‘people & community’ metric for CEO pay would have resulted in an outcome that was outside the realm of reasonability given the AUSTRAC issues at the time.

By favouring all stakeholders, none benefit

Using non-financial metrics as proscribed by APRA means treating all stakeholders as equivalent. This will inevitability result in a ‘tragedy of the commons’ situation, in which a lack of clear direction leads to a degradation of the business’s ability to focus on long-term value creation for its customers.

This contention is supported by academics. For example, expert in corporate governance and Professor of Finance at NYU Stern School of Business, Aswath Damodaran, predicts that “expanding decision-making to take into account the interests of all stakeholders will create decision paralysis.”

In a world of global competition, a lack of focus at the board and executive level will inevitably lead to poor decisions and poor outcomes for all stakeholders.

We do see merit in using non-financial measures as key performance indicators for specific employee groups, such as front-line staff who interact with customers and suppliers. There are significant differences in staff’s accountability and duty to customers compared to that of the CEO and Board accountability to their shareholders.

Qualitative measures are more easily rorted

Financial metrics such as TSR are not easily manipulated. Improvements in TSR is only achieved as a result of management efforts to deliver benefits to shareholders and stakeholders. However, if a minimum number of intangible measures are mandated by APRA, we expect management will find ways to ensure they are met.

We also have concerns that this could divert management’s focus away from adhering to unbiased accounting practices, reducing financial reporting quality. This could lead to the exact opposite of what APRA is aiming for, and encourage excessive compensation and reduce the independence of Boards.

Should lawmakers decide that components of STI and LTI become increasingly non-financial by nature, we as shareholders will vote against such measures at company Annual General Meetings.

We believe that active ownership, through strong interaction with both Boards and management, will ultimately see better outcomes for all stakeholders. Existing incentive structures, while imperfect, are already highly focused on these outcomes.


Will Baylis is a Portfolio Manager with Martin Currie Australia, a Legg Mason affiliate. Legg Mason is a sponsor of Firstlinks. The information provided should not be considered a recommendation to purchase or sell any particular security. Please consider the appropriateness of this information, in light of your own objectives, financial situation or needs before making any decision.

For more articles and papers from Legg Mason, please click here.


Additional information (not provided by Martin Currie)

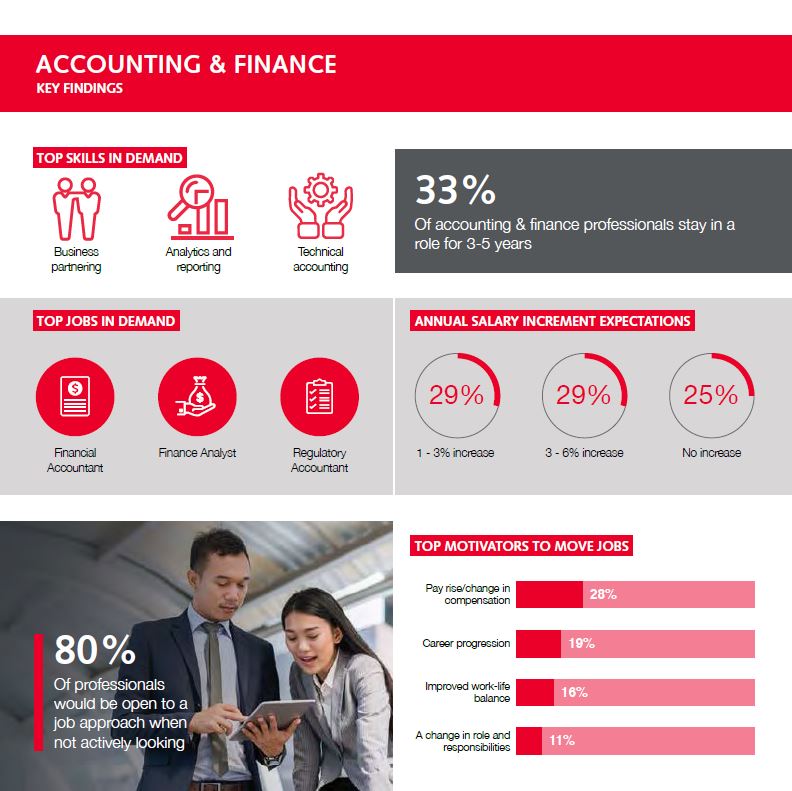
Recruitment consultancy group, Robert Walters' paper, Repair jobs at the banks, makes for additional reading on the subject of wealth management and retail and corporate banking sub-sector wage growth.
 

  •   4 December 2019
  • 3
  •      
  •   
3 Comments
Anthony Asher
December 04, 2019

Damodaran's article makes the reasonable point that you cannot maximise several competing objectives simultaneously. The CEO's he is criticising, however, only committed to the following:
- "Delivering value to our customers.
- Investing in our employees.
- Dealing fairly and ethically with our suppliers.
- Supporting the communities in which we work.
- Generating long-term value for shareholders"
This seems to me to be what he calls "constrained capitalism", and does involve constraints that can be measured and could form part of performance evaluation.
There is however much more to the debate on compensation:
- There is some evidence to show that excessive remuneration is not good for the company, nor its employees.
- There is overwhelming evidence to show that some "objective financial measures" bear no relationship to individual performance so fail to meet even their own stated objectives. Examples are backdated options, links to the overall level of the share market and links to returns on capital that can mean overgearing and turning down profitable projects.

Albert
December 04, 2019

It is not possible to regulate good ethics. waste of time and effort. most people have some morals and know how to balance stakeholders interests. Commonsense approach in our society.
however it is possible and desirable to not pay incentives. If you are being paid millions then there should be no further incentives to take unacceptable risks. we should not tempt CEO's to become living legends by encouraging excessive risk taking behaviour to achieve some bonus.
Without financial incentives, the only motivation left for a CEO is a non monetary one - peer group and community respect for good company stewardship.

George Wilson
December 10, 2019

See "I want to explore the problems that surround the concept of shareholder value and its maximization. I’m aware that expressing skepticism over this topic is a little like criticizing motherhood and apple pie."


https://www.gmo.com/americas/research-library/the-worlds-dumbest-idea/


Leave a Comment:

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.