Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 575

Australia: Most listed stocks per capita and biggest gamblers in the world

Australia has more listed companies per head of population than just about any other country on earth – and many times more than the US. Why?

Is it because we have many times more viable businesses opportunities to pursue? Or is it because we have the wiliest stock promoters and spruikers, and we are the biggest gamblers in the world?

Actually, it is both!

Aussies leading the world

Australia has 0.3% of the world’s population, and 1.5% of the world’s land surface area, but it has 4.5% of the world ‘s stock exchange listed companies. This is some 13x the world average number of listed companies per head of population, and five times more than the USA.

Since the earliest days of organised stock exchanges in Australia’s fledgling coastal cities and scattered across a host of remote, dusty mining towns, Australians have always led the world in investing their hard-earned cash in speculative mining ventures. To this day, Australia (along with that other wild west mining frontier land, Canada) continues to have the largest number of listed companies per head of population in the world, many times more than the US, UK and other ‘developed’ or ‘rich’ countries.

The left chart shows the number of domestic listed companies in the 80-odd countries in the world with recognised stock exchanges. Countries are ranked in order of population – from China at the top, to Bermuda at the bottom.
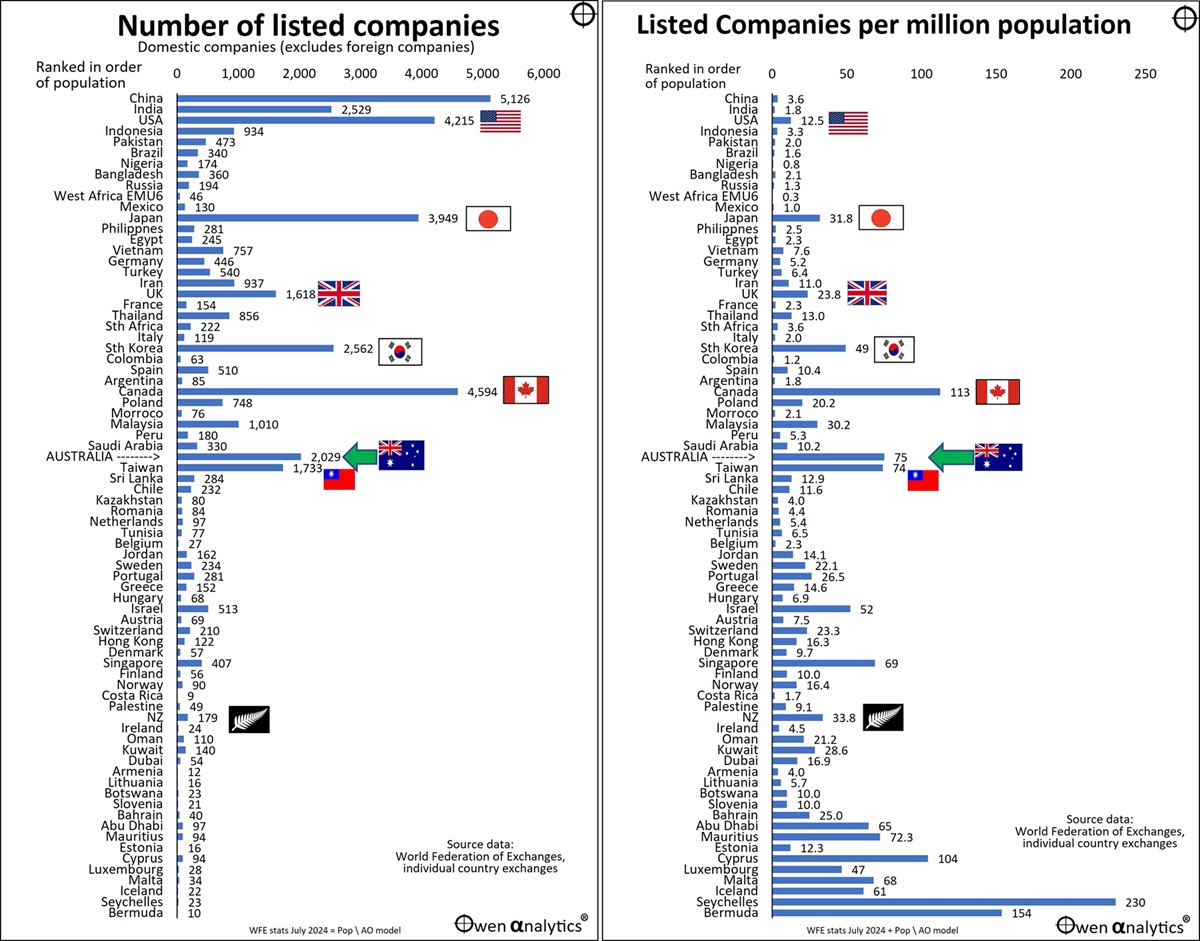
For this purpose I exclude foreign listed companies in order to eliminate double-counting (eg ASX-listed NZ-based companies like Xero, a2Milk, Fisher & Paykel Healthcare are included in the numbers for their home exchange in NZ, but not Australia). Likewise for foreign listings on other exchanges.

In total, there are more than 55,000 companies listed on stock exchanges around the world, but only around 50,000 companies excluding multiple foreign listings. Also excluded are listed funds (unit trusts) and ETFs.

Listed companies per capita

The right chart shows the number of domestic listed companies per million population in each country. Aside from some small tax havens down near the bottom of the chart, Canada is the leader, with 113 listed companies per million population. Australia is not far behind with 75 listed companies per million people.

Other countries with relatively high numbers of listed companies per capita are technology hubs Taiwan, South Korea, Japan, and Israel.

The US market has a wide diversity of industries and has been the dominant technology and innovation hub of the world for the past century, but it has only a fraction of the number of listed companies per capita than Canada or Australia. The number of US listed companies has been declining in recent decades, despite the huge tech booms in the 1990s and 2000s.

The number of listed companies per capita in Australia have been relatively stable, and several times US levels, especially since the late 1960s mining boom. In Europe the numbers of listed companies per capita are very low indeed, probably because of the heavy state involvement and regulation of business across Europe.

Mining speculators’ paradise

Australia and Canada are the stars – but why? They are not technology innovation hubs – in fact, the exact opposite. The stock markets of both countries lack the broad diversity of industries of the US market. Australian and Canadian stock markets are both dominated by a very small number of large banks and miners.

In the case of Australia and Canada, although each has more than 2,000 and 4,000 listed companies respectively, the vast majority of these are tiny revenue-less, profitless, wannabe mining explorers with little more than a map, a compass, and the promoters’ (mostly unjustified) dream of striking it rich. This has been the case since the earliest days of share trading in remote mining settlements.

The vast majority of tiny explorers will disappear worthless when they run out of money before finding anything useful to dig up. They will be replaced by the next round of tiny explorers that will also disappear worthless when they, too, run of money. There is always a next round of starry-eyed investors willing to throw money at dreams of hitting the jackpot in some faraway patch of dirt just waiting to be discovered.

More companies, not higher returns

It should be noted that simply having more listed companies to invest in does not lead or contribute to higher share market returns. Australia and Canada are similar to the US and all other stock markets in that the vast bulk of wealth created by the share market as a whole has come from a tiny handful of companies.

One of the main downsides for Aussie and Canadian investors has been that the huge number of cashless, profitless, speculative ventures tend to divert investors’ attention from the real generators of wealth.

It is very hard to resist the lure of hitting the jackpot by discovering the next Chalice Mining or Pilbara Minerals or Lynas.

Vast unexplored territories

There are probably two main reasons for Australia and Canada having much higher numbers of listed companies per capita than the rest of the world. The first is that both countries are vast, sparsely populated, frontier territories filled with an extraordinarily wide range of mineral resources just waiting to be explored and exploited.

Mining requires capital.

Aside from the initial alluvial gold fields that were exhausted quickly by hand at minimal cost, exploration and development of mines requires large pools of capital that generally require the collection of money from hundreds or thousands of willing investors. This requires corporate structures to protect investor rights, and processes to enable the secondary buying and selling of shares, which in turn requires brokers, lawyers, accountants, auditors, and recordkeepers – ie stock exchanges.

Highest income and wealth per capita

A second likely reason for the large numbers of speculative mining ventures in Australia and Canada, is that the combination of high-value resource exports plus sparse populations, has produced very high levels of individual wealth and incomes in both countries.

In many or most resource-rich countries (like Venezuela, Nigeria and dozens of other countries), much or most of the wealth has been, and still is, siphoned off by the rulers and their cronies, resulting in very low incomes and wealth for the great bulk of the population. In contrast, Australia and Canada have had relatively stable, representative political systems, and relatively low levels of inequality of incomes and wealth.

As a result of speculative mining riches (as well as from wool during the first 150 years), Australians have enjoyed the highest or near highest median income and wealth per capita in the world since the late-1800s, much higher than the US. This is still the case today.

Chronic gamblers

Australians have long been the biggest gamblers in the world per capita (eg see Productivity Commission report). This may be one of the reasons for our love of speculative mining stocks. Or is it the other way around? Are we a nation of mad gamblers today because of our history of speculative mining riches?

Meanwhile, time to get back to finding the next winner!


Ashley Owen, CFA is Founder and Principal of OwenAnalytics. Ashley is a well-known Australian market commentator with over 40 years’ experience. This article is for general information purposes only and does not consider the circumstances of any individual. You can subscribe to OwenAnalytics Newsletter here. Original article is here: Australia: Most listed stocks per capita, and biggest gamblers in the world - Is there a link?.


  •   28 August 2024
  • 7
  •      
  •   
7 Comments
Raymond
August 29, 2024

Ashley, I reckon the connection is a stretch. We just have a lot of crappy miners desperate for cash.

ashley owen
August 30, 2024

agreed. But every one of those 1,500 'crappy miners' (or wannabe explorers actually) got 'listed' on the exchange because they convinced thousands of willing punters to part with their hard-earned cash. That's the definition of gambling.
Australia got rich on taking big risks - not just in mining but in agriculture - big bets on the weather, crop selection, timing of planting/harvesting, droughts, floods, mice, locusts, global market prices, and a host of other risks. Our ancestors took big risks and won, big time! It's in our blood!
ao

Geoff
August 30, 2024

If you think 75 is "not far behind" 113 (Aus v. Can listed companies per capita), I'm glad I'm not driving behind you on a narrow country road... :)

ashley owen
August 30, 2024

well actually its a bit more complex than that. The question of 'organised stock exchanges is not exactly a black & white concept. It depends on which companies you count in each country. Eg in Canada there is the TSX, the TSX Venture Exchange, TSX Alpha Exchange, and Montreal Exchange. If I just counted the TSX (1,782 stocks), which is like the ASX, then Australia has more companies with a smaller population.
For this exercise I include TSX and TSX Venture + Montreal, but not the Alpha exchange. (its a bit like not counting the 'Pink Sheets' in the US market - they are publicly quoted and traded but I don't count them for this purpose).
As always, I try to select the best, most relevant data that presents a fair picture for the particular issue in question.
cheers
ao

Barry
August 31, 2024

It's spelt Chalice Mining, not Challis Mining.

James Gruber
August 31, 2024

Nice pickup, Barry.

It's been corrected in the text.

ashley owen
September 01, 2024

either way it was $10 bucks a share in late 2021 at the silly boom-time bubble price. Now its $1. That's a poison chalice if ever I saw one! Still a revenue-less, profit-less wannabe. Is it a buy now?
cheers
ao


Leave a Comment:

RELATED ARTICLES

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

Can you value a share just using dividends?

The 2025 Australian Federal election – implications for investors

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.