Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 444

Bank hybrids response to equity market weakness

What’s the relationship between hybrids and equities when equity markets are weak? Probably the best comparison are the couples that appear on the Bachelor/Bachelorette: it’s ‘complicated’. There’s almost no correlation between the two assets most of the time, but sometimes there is and sometimes it can be material.

Price markdowns on bank hybrids and bank shares

The chart below details the drawdowns (markdowns in prices) for the Elstree Hybrid Index (Banks Series – yellow line) with the S&P/ASX200 Banks Accumulation Index (source IRESS – blue line).

Banks are actually a bit more volatile than the All Ordinaries Index but the bank index is a better like-for-like comparison. At the time of writing, bank shares are around 10% off their highs and hybrids are weaker by around 0.60%. If you are into statistics, that’s a 1 standard deviation move for both markets. You get worse than that most years.
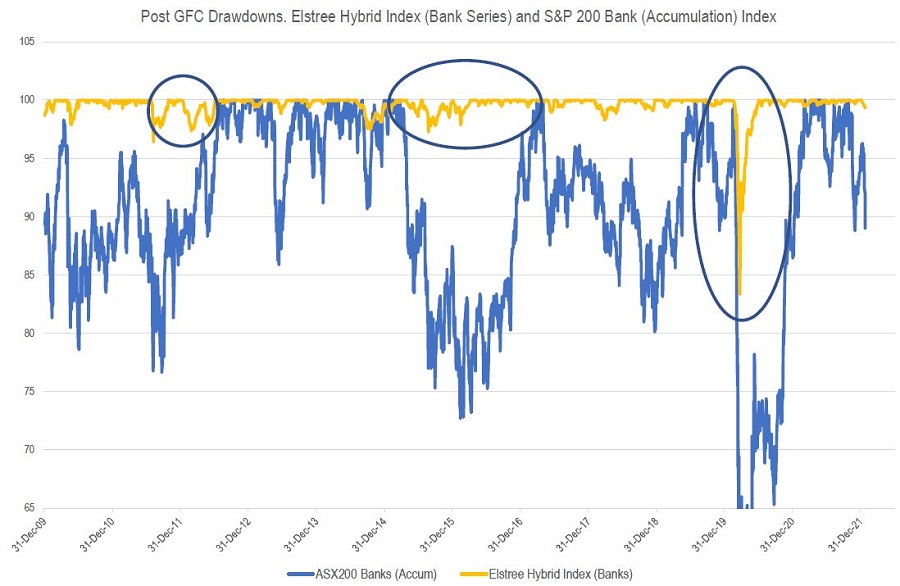
The three circled areas are the periods of material weakness since the GFC and there are some common factors for each of those periods which aren’t present to date in the current sell off:

  • Fears of material economic slowdown/economic chaos (China slowdowns, Euro bank problems, Greece, Covid, etc)
  • Protracted equity market weakness
  • Big drawdowns. Bank equities had to have sold off by more than 15%.

This sell off is not echoing the previous three. It’s an inflation/too fast growth/interest rate led sell off and so far, it’s only around 10%. At this stage, it looks like normal noise for hybrids. We might see another 0.5% - 1% weakness before we get a full recovery, or this might be the bottom if equity markets stabilise.

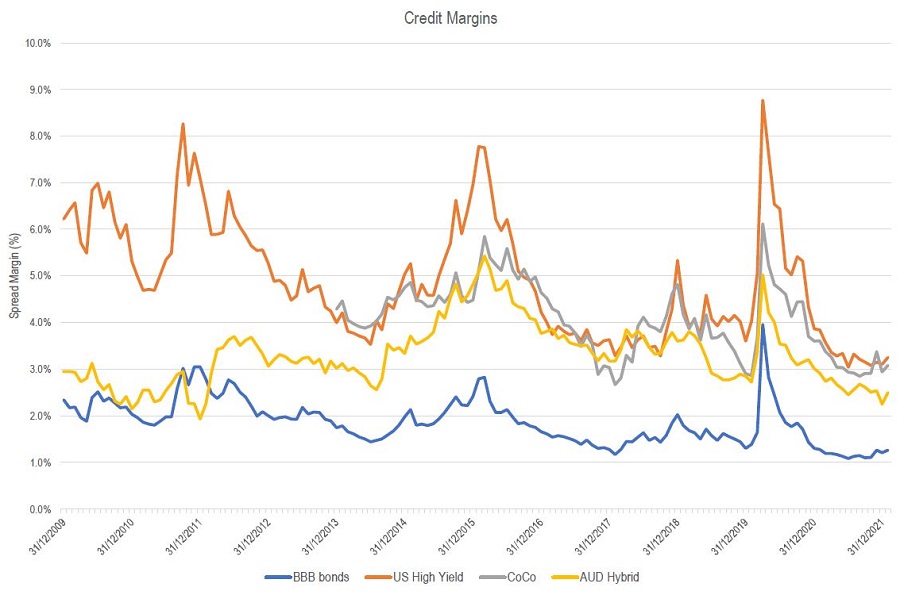
Nothing to see on credit margins yet

The chart below gives a longer-term perspective of credit margins (source BofA/ICE, Elstree) for four types of credit investments: ‘BBB’ rated bonds, High Yield bonds, CoCo (non AUD AT1/hybrids) and Australian AT1/hybrids. The last data point is 26 January 2022.
Will the last month lead to a surge in defaults down the track?

That would be nasty. We would be adjusting hybrid portfolios if we thought defaults were coming.

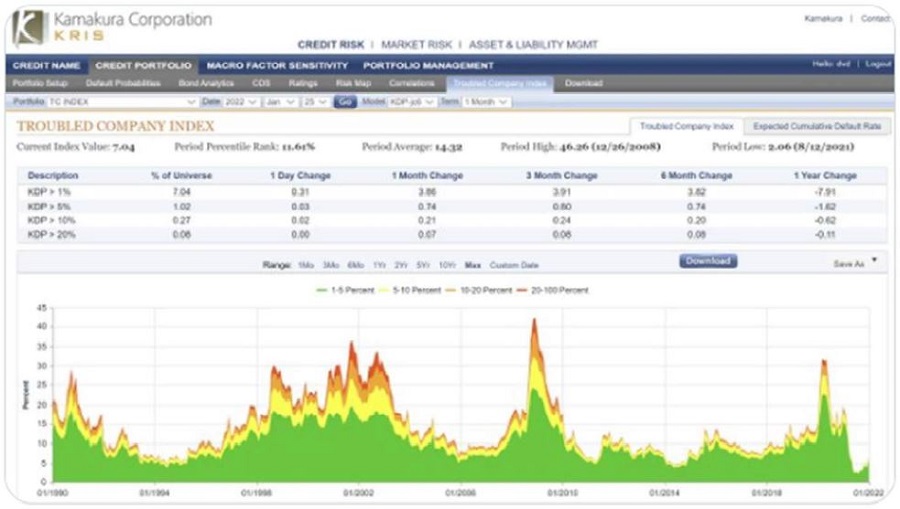
But at this stage it’s a non-event. Our favourite indicator is the Kamakura Troubled Company Index (source Kamakura). The index details the proportion of companies globally in various degrees of difficulty. While it’s a black box model, with its major inputs being equity markets and volatility, it has been extremely accurate predictor of default activity with a 12 month lead time. Credit conditions are still in the 11% of best periods since 1990, despite the month of market falls and its 1/3 as scary as what happened during Covid. There’s no default threat yet. The chart below is the 26 January 2022 update.
Why you own hybrids

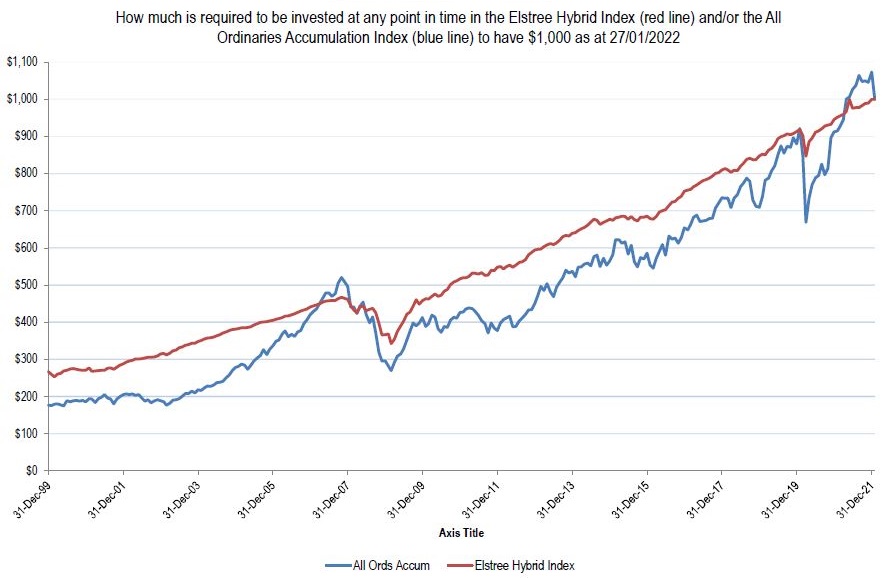
Here's our favourite chart that gives a rationale for investing in hybrids. It shows the amount (in dollars) you need to invest in the hybrid (red line) or equity market (blue line) at any one time over the past 21 years to have $1,000 today. Clearly, a lesser amount is better.

If you invested in our funds, the amount invested to have $1,000 today is even lower than that of the benchmark hybrid index.

The key takeaway is the delivery of similar return outcomes with lower risk. If you wanted to cherry pick data points, hybrids have outperformed equities since 2007 and also since just pre Covid. If you bought equities at the bottom of the Covid drawdown, you would have outperformed, but in general, hybrids have been great for much of the past 14 years. We think that is still a valid reason to invest in the asset class.
 

Norman Derham is Executive Director of Elstree Investment Management, a boutique fixed income fund manager. This article is general information and does not consider the circumstances of any individual investor. Elstree's listed hybrid fund trades on ticker EHF1. 


  •   2 February 2022
  • 2
  •      
  •   
2 Comments
Doug Turek
February 02, 2022

Terrific charts but is there some reason why they couldn't have started in 2001 when apparently you first created your useful Elstree Hybrid Index? It seems the key event of the GFC is missed and it would be useful to see the drawdown then. Also, well done comparing a hybrid to an equity in your last chart, as most compare hybrids to fixed interest investments. Of course a problem looking backwards with any fixed interest investment returns, is that they enjoyed wonderful starting high yields and won't today (ie. the 10 yr bond yield was 8% in '00 (hybrid 10%?) and is under 2% now and indebtedness limits its rise). Often the best predictor of future returns of a fixed income investor is the current yield (definitely not past performance) so perhaps one should just compare the current yield of the All Ords and hybrids. Your last chart is great but I question you can infer they will keep up with All Ords because they did. Put similarly I suspect a 30 year old fixed rate Gov't bond bought in 2000 would also have beaten the All Ords but a new one now only offers a prospective a 3% pa return for 20 years.

Campbell Dawson
February 02, 2022

Doug We've published the pre GFC drawdowns in another article: you can google it if you need to. The brief summary is that bank hybrids experienced an 18% drawdown which is almost entirely explainable by the capital losses from margins increasing from the 1% level we saw prior to the GFC to 5.5% (which is where they have topped out in the other very weak periods). If margins increased from the current 2.75% to 5% over the next year your capital loss would be c6.5% offset by 3% income , so a drawdown of c3.5%. There are other differences. Banks have doubled their capital since the GFC and prices of some bank hybrids in the GFC reflected a fear that they would not be redeemed. All these make using the GFC experience problematic. Returns. Hybrids are almost entirely floating rate so there has been no benefit from falls in interest rates. We've also published research that if you compare returns of equities to bonds over almost any long period, they rarely produce returns of greater than 2% better than the 10 year bond at the time you start your comparison. If that repeats, margins of c3% on hybrids may continue to provide returns that are comparable to equities. Thanks for the comments and for reading the article


Leave a Comment:

RELATED ARTICLES

Hybrids throwing up opportunities … and risks

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.