Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 243

Defaults low but no room for complacency

February is ‘Groundhog Month’ for credit market nerds. Moody’s publishes its annual default study each February and for seven out of ten years, not much happens. This year was one of those, which is good because it means it's been a boring year. Nothing that was investment grade at the start of 2017 defaulted during the year and only around 3% of sub-investment grade issuers defaulted. Overall default rates were just over 1%, which is around median levels.

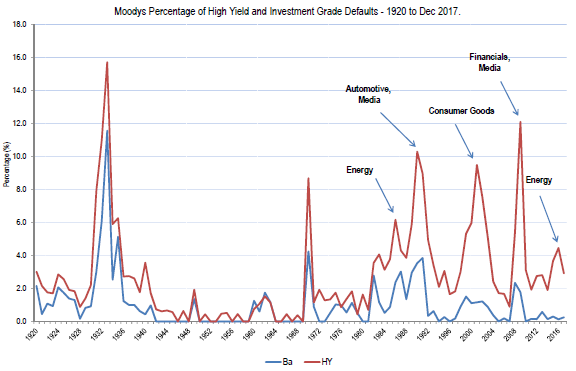
However, over the last few decades, the overall default and high yield default rates have been boosted by a higher proportion of lower-rated issuers who default more often. The chart below shows this with default rates of ‘Ba’ and ‘high yield’ since 1920. We have also shown the industries which were over-represented during default spikes.
Watch for the once-a-decade jump in defaults

Since the 1970s, there’s been a once-a-decade spike in defaults for investment grade and the upper end of the high yield market. Defaults in those sectors invariably coincide with recessions. For the lower end of the high yield market, there are always defaults, and they become chunky in recessions. Interestingly, there are always industry clusters of defaults. Energy is the most cyclical of industries and the large majority of defaults over the last three years have been due to energy (particularly shale energy) when the oil price fell. However, other sectors which have been disproportionately represented in high-yield defaults include media, construction and finance (during recessions).

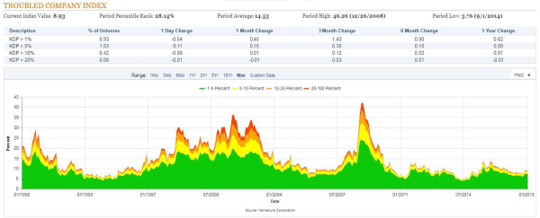
Two of our forward indicators are indicating another sleepy year. Moody’s uses a model to predict high yield defaults and it is forecasting that default rates will fall to 1.7% in 2018. If that occurs, it will be the second lowest default rate since 1981. The chart below shows the Kamakura Troubled Company Index, which has been an excellent predictor of the default rates 12 months ahead. It forecast the GFC default avalanche over a year before it happened, and also it picked the peak of defaults in 2009 about 12 months before.

Currently, conditions are in the best 28% of observations since 1990 and it is predicting subdued default activity over the next 12 months.
So where are we?

The standard position for an investment grade credit investor is to remain invested, because the margin over risk-free rates is sufficient to compensate for the default risk. If an investor bought every 5-year ‘BBB’ bond at the start of every year, they would have outperformed the risk-free government bond for that 5-year period in every year but one since the 1950s.

The default cost on that cohort of bonds has (almost always) been less than the additional yield investors receive on ‘BBB’ bonds over the risk-free government bond rate. It's more cyclical lower down the credit spectrum, but over the long run there is always a gain. However, for anyone who can correctly forecast a recession or near recession, selling can be extremely profitable.

Notwithstanding the positive non-recession forecast, there are some issues, including:

  • The non-default cycle is now very long-lived and over the post 1970s pain-free average (but still well below the 1940 to 1970 experience)
  • There has been an overall increase in leverage and other negative debt metrics over the past few years, and valuations are expensive
  • There's no recession in sight and if that continues, we'll see little stress on investment grade or high non-investment grade debt
  • We can't see any obvious industry bubbles and the two largest debt widow-makers (energy and commercial real estate) seem within normal valuation parameters.

However, take a look at the first chart, and see those spikes in defaults every decade or so. High yield defaults around 10% and investment grade around 2% to 4% are not uncommon.


Campbell Dawson is Executive Director at Elstree Investment Management Limited. This article is general information and does not consider the circumstances of any individual investor.


  •   7 March 2018
  • 4
  •      
  •   
4 Comments
Doug
March 08, 2018

Campbell, good information on an overlooked topic.

This article may prove quite prophetic esp. regarding more marketed unrated and high yield (non-investment grade / junk) bonds

I worry ...
1) new to the industry, mum and dad investor-buyers of unrated and high yield bonds have no history understanding the later surprise default and illiquidity thereafter
2) the bond brokers marketing and arranging these purchases can sometimes rely too easily on general advice and wholesale investor provisions
3) trusting the same brokers as Custodian of the bonds may be Lehman-like inappropriate
4) ASIC's focus is elsewhere
5) professional investors could also be caught out too, forced to take excessive credit risk to combat ultra low interest rates and relatively high (to the cash rate) TD rates

As you said it is all fine until it isn't.

Campbell Dawson
March 15, 2018

Hi Doug,
The best way to access the benefits of high yield is as part of a diversified portfolio strategy and via a very diversified ( ie >50) securities portfolio and to have a > 5 year time frame. There may be investors who don't realise that either the quantum of defaults will increase from the current extremely low levels, or that you need to hold through the cycle.
If an investor does not understand that or is not sufficiently diversified enough, there will inevitably be issues when the next default cycle happens,
The better the credit quality of the portfolio (ie investment grade), the long investment horizon becomes less critical, and a less diversified portfolio would still do ok, although credit is an asset class where holding lots of securities is a free lunch: returns dont fall much and the risk of a single default is far less consequential

stan
March 11, 2018

1 It would help to explain what is meant by "default".
2 Given the track record of the rating agencies (remember GFC ?) why put too much credence on their opinions?
3 Well thought out covenants are potentially more significant in assessing the risks of some bonds.

Campbell Dawson
March 15, 2018

Stan
1)Default is simply if an issuer fails to pay a coupon or redeem principal on time
2) Ratings are suprisingly good at quantifying/predicting default for corporate issuers. The ratings of the so called "structured securities" were much less accurate in predicting the default behaviour of those securities in the GFC (and continue to be less valuable)
Having said that, we think that within the "corporate" realm, credit ratings agencies do better on some industries than others.
3) You may be right. Academic literature is mixed on the value of covenants (probably because they are all different enough that you can't get a big enough sample)


Leave a Comment:

RELATED ARTICLES

Why would you invest in junk?

The case for high yield bonds

S&P default rates and the risks in bond investing

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.