Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 446

Howard Marks on selling versus staying invested

After 40 years of writing memos to his clients, Howard Marks of Oaktree Capital realised he had never written about selling. It’s surprising given the impact of the sales decision on investment results, and in particular, missing out on subsequent market gains.

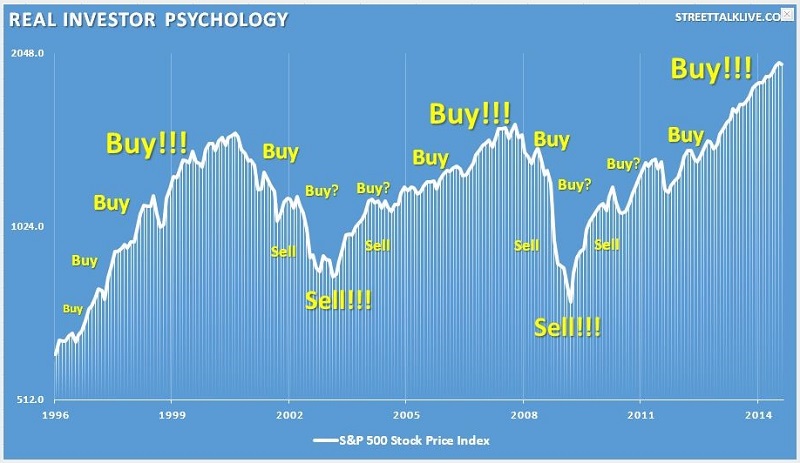
Numerous studies show the average fund investor performs worse than the average fund, and it’s mainly due to the entry and exit decision. Here is a typical chart which I often use during investor presentation, and while it might be exaggerated, there’s much truth to it. Inflows to funds tend to be at their maximum after a strong run and a market peak when investors are confident. Fewer people have the fortitude to buy after a sell-off, and worse, they sell because they fear further falls. This ‘buy high, sell low’ attempt at timing is rarely successful.

Marks cites Charlie Munger of Berkshire Hathaway, who notes that selling based on market timing gives an investor two ways to be wrong: the decline may or may not occur, and if it does, when is the time to reinvest?

Marks notes that the people who sell before a market fall and “too often may revel in their brilliance” but then they fail to reinvest at the market lows, so what did they achieve?
Who can hang on faced with big gains or losses?

Marks uses the classic example of buying Amazon to show how tough it can be hanging around for the long-term results. Amazon floated in 1998 for US$5, and it’s now US$3,304 (up 660X). But it hit US$85 is 1999, or 17X in less than two years, so who would not have been tempted to sell then? By 2001, it was down 93% to $6, so who would have panicked? And by 2015, it was back to $600, or 100X the price of 2001. Selling at a wonderful $600 would have missed 82% of the subsequent rise. Says Marks:

“When you find an investment with the potential to compound over a long period, one of the hardest things is to be patient and maintain your position as long as doing so is warranted based on the prospective return and risk. Investors can easily be moved to sell by news, emotion, the fact that they’ve made a lot of money to date, or the excitement of a new, seemingly more promising idea. When you look at the chart for something that’s gone up and to the right for 20 years, think about all the times a holder would have had to convince himself not to sell.”

Investing is a relative selection

Many investors sell when a share price rises because they do not want to lose the profit. Nobody enjoys seeing a big gain disappear. But likewise, many investors worry about allowing losses to compound. It’s bad enough when a stock loses 10%, but letting it go further to 20% or 30% seems neglectful. So markets up, markets down, investors tend to overtrade.

Marks is keen on an idea taught to him when he first started in the market by a mentor, Stanford University Professor Sidney Cottle, that all investing is a ‘relative selection’. Marks says:

“Selling an asset is a decision that must not be considered in isolation. Cottle’s concept of ‘relative selection’ highlights the fact that every sale results in proceeds. What will you do with them? Do you have something in mind that you think might produce a superior return? What might you miss by switching to the new investment?”

And so despite the risk of market falls, Marks says the most important thing is ‘simply being invested’. Buying and selling based on market timing is not likely to work and misses the potential for upside.

Backing his view, he cites data showing long-term returns from markets and the risk of missing out on a few days. In particular, anyone starting out investing as a young adult will do well by the time they retire. For example:

“JP Morgan Asset Management’s 2019 Retirement Guide showing that in the 20-year period between 1999 and 2018, the annual return on the S&P 500 was 5.6%, but your return would only have been 2.0% if you had sat out the 10 best days (or roughly 0.4% of the trading days), and you wouldn’t have made any money at all if you had missed the 20 best days. In the past, returns have often been similarly concentrated in a small number of days. Nevertheless, overactive investors continue to jump in and out of the market, incurring transactions costs and capital gains taxes and running the risk of missing those ‘sharp bursts’.”

One of the basic tenets of investing

Marks says that when the five founders of Oaktree established an investment philosophy in 1995, one of the six tenets focussed on market timing and inability to predict markets:

“We keep portfolios fully invested whenever attractively priced assets can be bought. Concern about the market climate may cause us to tilt toward more defensive investments, increase selectivity or act more deliberately, but we never move to raise cash. Clients hire us to invest in specific market niches, and we must never fail to do our job. Holding investments that decline in price is unpleasant, but missing out on returns because we failed to buy what we were hired to buy is inexcusable.”

I would qualify this by acknowledging that the portfolio should participate in the upside but not carry so much risk that the investor cannot sleep at night worrying about losses. Too much focus on preparing for losses is a mistake but there is no one-size-fits-all in investing. Many retirees simply cannot tolerate losing the money they have to live on when there is little or no capacity to return to work.

Marks’ bottom line

Howard Marks sums up his latest memo saying there is no ideal portfolio and no complete way to assess risk. Therefore:

  • We should base our investment decisions on our estimates of each asset’s potential
  • We shouldn’t sell just because the price has risen and the position has swelled
  • There can be legitimate reasons to limit the size of the positions we hold
  • There’s no way to scientifically calculate what those limits should be.

“In other words, the decision to trim positions or to sell out entirely comes down to judgment, like everything else that matters in investing.”


Graham Hand is Managing Editor of Firstlinks. This article is general information and does not consider the circumstances of any investor.


  •   16 February 2022
  • 4
  •      
  •   
4 Comments
Kevin
February 16, 2022

I do nothing at all.I have never been able to figure out why I should sell.The think 10 years ahead thing didn't make sense to me I always thought in 20 year minimum periods.
Buying decisions were always easy,the price has fallen ,buy.The only one I had doubts about was the NAB share purchase plan a couple of years ago at around $15.I thought for a couple of minutes,then habits kicked in and I bought .No way did I expect the return that has been achieved since then.
CSL this week was good,I was fairly accurate with what I thought would be the $253 price for the SPP,it was $253 and change .They scaled it back which I did not expect,and the share price was falling.Tuesday I got in at $241 and change,I thought I would be mad not to buy them at that price,now it is wait and see.I think the instos paid $283 for their shares in that SPP..
Now it is wish and hope for Macbank to get down to $150,and I'm in,I have doubts that will happen but never say never

Kevin
February 16, 2022

Strange things can occur on the buy side,a heatwave changes things.
Normally I would be out on the bike all day,never look,listen or see anything to do with with stock markets.The wonderful peace of no noise at all. I sometimes listen to first links podcast ( comment of the week there Graham?) on the bike..
As it seems never to have fallen to under 37C for about 10 years here in Perth with this heat wave I have time on my hands.Out early to avoid the heat and back 3 or 4 hours later to avoid the heat.The markets are still open.
So last week and this week with time on my hands I've been buying,doing something,I thought I was allergic to that .
All bought for the 3 dividends in a year.
CBA,what a shock when that jumped $6 after reporting,I bought the day before.There didn't seem to be the usual run up in price so I thought I would dividend chase. FMG as a new buy,I may finish up averaging down on that one if it drops to around $14. WOW as a new buy,purely as better returns than money in the bank ( FOMO?).CSL and then today WES after a good early fall. WES can trend sideways for long periods but you've got to be in it to win it .
I like the sit on your hands to stop you do anything dumb Buffett mantra.Perhps feet on the pedals is better,with the benefit of keeping fit..
I might have to hide the phone,or hide in the shade on the bike to avoid the heat

Trevor
February 19, 2022

Kevin : You say : "As it seems never to have fallen to under 37C for about 10 years here in Perth with this heat wave..." Hmmm! I would not want to rely on your memory to guide my investment advice. Try some Perth temperature data in 2021: Coldest day 10.3°C at Bickley on 1 Aug, 2021. On 10 Aug, 2021 Coldest night 0.1 °C at Jandakot Aerodrome. On 22 Jun, 2021 Coolest nights on average 11.6 °C at Bickley. Warmest nights on average 15.8°C at Rottnest Island, all in close proximity to Perth Try taking the thermometer out of your pocket.

Matt
February 17, 2022

While I agree with the philosophy of buy hold, there are the inevitable times when good stocks turn bad, get worse over time and eventually go into receivership and your money is gone, all when you watch from the sidelines thinking they will come back eventually, I learnt that a few times with what we're at the time I bought considered gold standard stocks. When you think about it, all companies have a lifetime, some very long, some not so, you J st don't know when bad management or change of market might kill them off.


Leave a Comment:

RELATED ARTICLES

Happy RBA refuses to blink while market runs ahead

Five strategies to match your investing to your behaviour

US market boom-bust cycles - where are we now?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.