Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 387

Investor downside when management controls access to the board

"A lot of people die fighting tyranny. The least I can do is vote against it."

- Carl Icahn

Capital markets have been wonderful inventions. Freed from self-interest and patronage, they allow Adam Smith’s ‘invisible hand’ to unemotionally allocate scarce capital around the economy, investing where it will be most productively used. Society as a whole reaps the benefits. Greater economic output raises living standards for all. Better investment returns benefit retirees and those planning for retirement.

These days capital markets are heavily-regulated structures. They should be. Despite their capacity to turbo charge economic growth, capital markets have significant flaws. Some of these shortcomings are plain to see. Wealthy and compassionate societies don’t let market forces decide whether an ambulance arrives.

We set the boundaries that markets operate within because we know there are many problems that markets can’t solve. For the problems we do want them to solve, however, capital markets can still fall well short, often at the great expense of investors.   

The agency problem

The original sin within our model of capitalism is that it separates the ownership of companies from their management. Few family-owned businesses can attract the capital or talent necessary to build a BHP. Thus, by separating the ownership of a company from its management, businesses are able to grow - and create wealth and jobs - in ways private firms struggle to replicate.

In doing so, we create what economists call an ‘agency problem’. Investors, who put up their hard-earned savings and own the company, must rely on their agents - management - to run the business with the owners' best interests in mind.

Managers on the whole are an honourable breed. But, as Paul Keating liked to say, quoting Jack Lang: ‘In the race of life, always back self-interest - at least you know it's trying.’ Time and again, left unsupervised, managers have demonstrated a terrible tendency to run companies in ways that suit them, not their shareholders.

Our solution to this agency problem is supposed to be robust and independent company boards. Shareholders appoint directors and pay their salaries. They are there to act as the guardians of our capital and to stand up to managers on our behalf.

The ‘Wall Street walk’

The entire premise of shareholder capitalism rests on the notion that a board is there to represent shareholders. When the relationship is working well, a company’s corporate governance framework should look like the healthy model below.

Shareholders appoint directors who, in turn, oversee management. Boards are there to offer advice to management when it is needed, and to hold them to account when it is necessary. Management then have a clear guiding principle to work towards - prioritise shareholders and shareholder returns.
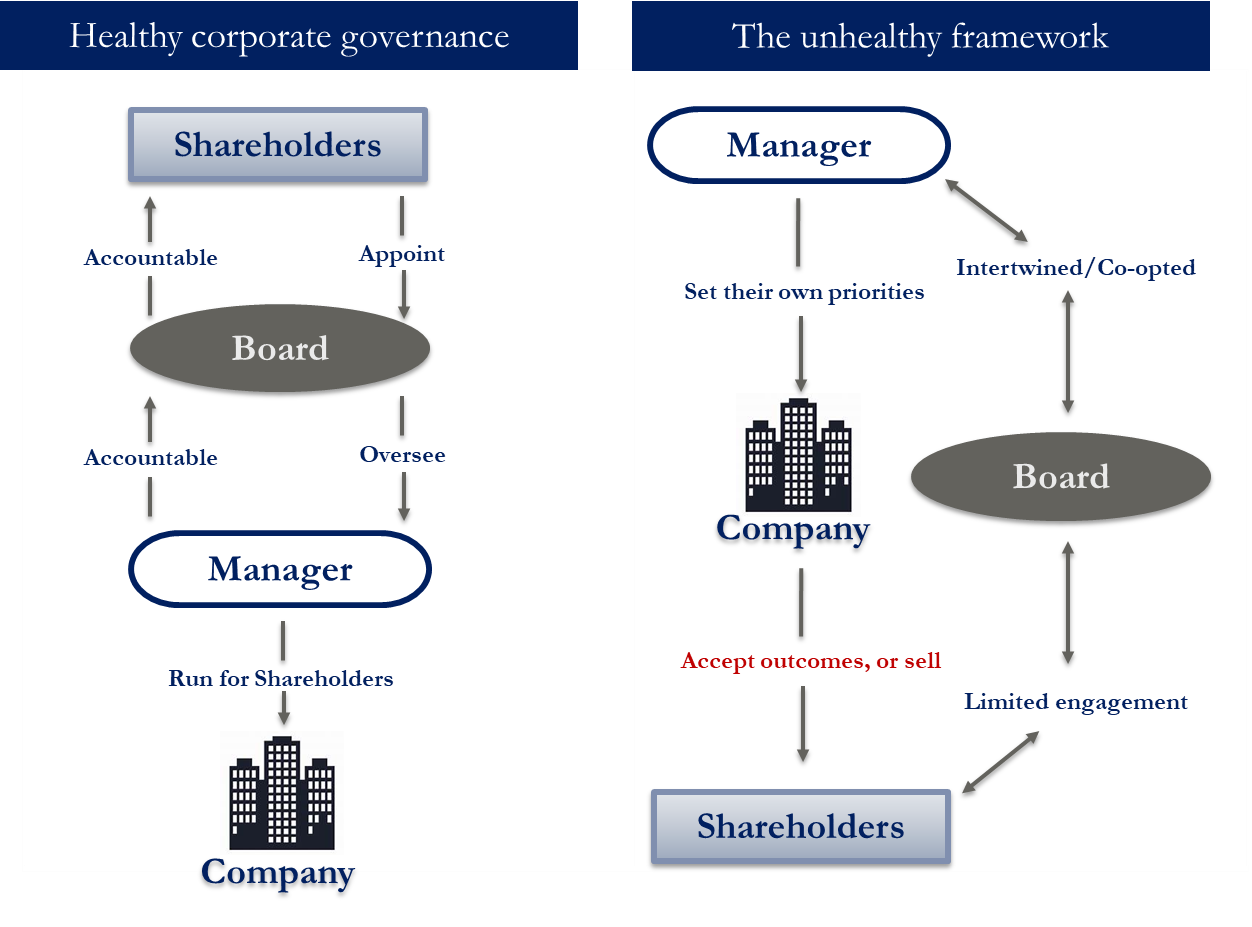
Well-functioning corporate governance models look great in textbooks. In the real world, modern capital markets have left shareholders increasingly separated from the boards that are supposed to represent them.

Shareholders come and go today with incredible speed. In the 1960s, the average share holding period for a US investor was six years. By the 1990s, this had fallen to just two years. Today it sits at six months. While a company’s owners come and go every few months now, boards and managers work together hand-in-hand for years, sometime decades.

It is easy to see how boards can become co-opted by their management teams. Almost all ‘shareholder feedback’ today comes to boards through the manager and the manager’s investor relations team.

When was the last time you directly spoke to the board of a company you owned?

Even with the best of intentions, boards are at risk of receiving curated shareholder feedback that fits with managements’ own agenda.

In the real world, the most common corporate governance failing at a company is that its board slowly becomes entwined with its management team. Managers then begin to set their own priorities for the company and their own vision for the future. Sometimes these overlap with what is best for shareholders. Too often they do not.

When this occurs, shareholders - who are the owners of the company - are left with two options. Accept the outcomes that management deliver or sell your shares and move on. In market parlance this second option is referred to as the ‘Wall Street walk’.

The passive problem

Exacerbating the agency problem in recent years has been the explosive growth of passive investing and the Exchange-Traded Fund (ETF) industry. The premise behind passive investing is hard to fault. ‘Efficient market theory’ argues that everything you could ever know about a stock is already in its price. Given that, don’t bother trying to analyse companies.

Instead, let others do the hard work of figuring out what a company is worth and passively invest into the markets as a whole. This logic is certainly boosted by the fact that, after fees, the average fund manager underperforms the market over time.

While ETFs have provided many investors with a great low-cost way to invest in the market, they have amplified the agency problem that already existed in the stock market. As the share of companies owned by passive investors has increased exponentially, fewer shareholders today are actually involved in the process of holding managers and boards to account.

Vote with your hands, not your feet!

When shareholders feel that the Wall Street walk is the only way to escape an underperforming company, the entire premise of how capital markets are supposed to work has broken down. The point of public companies is that public scrutiny and shareholder democracy is there to shine a light, to hold the people working for us to account.

If shareholders do not exercise those rights, self-interest and cronyism very quickly sets in. Worse, the cycle becomes self-fulfilling. When shareholders vote with their feet and not their hands, vested interests learn a very dangerous lesson. Once learnt, the problems tend to get worse over time, not better.

All of this means that it is more important than ever that shareholders pay attention to what is going on at their companies. If you are a shareholder in a company, you are the owner of the business. Make a point of engaging with your board - they are there to represent you. Most importantly, take the time to vote at shareholder meetings, and if you’re unhappy, vote with your hands, not your feet! You own the companies that you invest into. The people running them are supposed to be working for you.


Miles Staude of Staude Capital Limited in London is the Portfolio Manager at the Global Value Fund (ASX:GVF). This article is the opinion of the writer and does not consider the circumstances of any individual.


  •   9 December 2020
  • 7
  •      
  •   
7 Comments
Ray Tollefsen
December 09, 2020

Excellent article.
I am a shareholder and I do engage with management during the year when I have a question/issue. I also go to as many AGMs as possible, ideally each company every second year. That is the only real opportunity retail shareholders have to speak directly with Board members. Unfortunately, virtual AGMs this year have killed that opportunity, but all companies I own have stated they want to return to in-person meetings as soon as they are able. That's a sign of companies which do want to engage with shareholders and are the only type I am interested in investing investing in.
I encourage all shareholders to go to AGMs and not just for the nibbles. If you haven't before, you should be pleasantly surprised by the experience, unless it's a company with a 'hired gun' CEO and Board who are really only interested in Instos and Poxy Advisors, i.e most Blue Chips . If you aren't happy, let them know and, depending on the response, sell out.

Michael
December 09, 2020

Agree - an excellent article. My impression is that some companies tolerate retail investors rather than engage with them and it is relatively easy to determine this through communications that are directly sent, or advised of, to shareholders. Excellent companies are frequent direct communicators to the nominated e-mail address. But sadly with many companies if you do not check ASX communications you will be in the dark including on market sensitive announcements. I'm not sure if this is a cost saving measure - with Computershare, Link and Boardroom - or just lack of interest by the Boards.
Your views would be appreciated?
When Boards lack sufficient operational or relevant industry experience the ground is ripe for poor management performance. Business must care for customers, suppliers, environment, community etc - it makes good business sense and you do want your company to be a good corporate citizen - but when you see Annual Reports where shareholder interests seem subordinate to customers, suppliers, community etc it does make you wonder whether the Board focus and skill set is balanced. Wesfarmers is one company that bucks the orthodoxy and has expressed their objectives well, but again most do not.
Nowhere is orthodoxy more evident than in the formulaic approach to remuneration. Despite the voluminous pages the current orthodoxy does not work well. There are numerous instances where actual performance and actual executive remuneration are not well aligned and this is due to the formulas used - but little changes. Origin is the standout example this year with a Board completely out of touch with the real losses suffered by their shareholders. While the Board changed their approach pre-AGM retail shareholders were not given an opportunity to look at the proposal and voice an opinion.

JAMES
December 09, 2020

Yes, excellent article. Miles's final paragraph sums it up perfectly. If you are not happy then do something about it - and vote. You may well be surprised at the very high number of shareholders that agree with you - and the changes that can be made to happen.

Peter
December 10, 2020

For small shareholders in Australia the Australian Shareholders Association provides an easy effective way for your vote to count or at least have influence! Beats me why people don't stop whinging and simply do something positive like assign the ASA as your proxy!

Rod.
December 16, 2020

Spot on Peter,
when I was much younger I met an Older Gentleman at an AGM over a cup of tea.
He advised me to assign my proxy to the ASA.
For all the reasons you outlined this a sensible course of action for the "small" investor.
Now that I am much Older and hopefully a Gentleman I pass this advice on to anyone who is prepared to listen.
Similarly with GVF Miles and Emma provide an avenue for the small investor to have serious Professionals work and do the "hard" analysis for them and use sensible Activism for the benefit of many Not the Few.
Good Luck.

John Symonds
December 13, 2020

I used to vote at the various AGMs but have never been satisfied with a reply. My "pet hate" is when Officers
Give themselves a bonus even though the company has NEVER turned a profit. Voting analysis seems too
hard for the shareholders to be given.

Janine
December 16, 2020

Voting at an AGM is our only way to be heard, we must make it a priority to read the agenda, notes and make an informed decision.


Leave a Comment:

RELATED ARTICLES

Why investment stewardship matters for long-term investors

Why the ASX is losing Its best companies

A Bunnings play without the hefty price tag

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.