Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 248

Is it time for ‘set and forget’ to consider retirement?

The simplicity of set-and-forget investment approaches is that once established, you don’t need to worry about them too much. Set … and … forget. It’s simple and it rhymes! You will still need to determine things like rebalancing and reinvestment policies but month-to-month, day-to-day, and minute-to-minute, there’s a reasonable chance of achieving your return objective over the long term by sticking to the plan. Indeed, obsessing over market gyrations can lead to investors making a mistake (for example, selling at the bottom).

Set and forget or remember to revisit?

This set and forget approach has been best exemplified in the strategic asset allocation (SAA) arena. Here, the realisation of long-term average returns and volatilities have combined with the benefits of diversification to help many to meet and exceed their objectives over several decades. Ten years on from the GFC, the central-bank-fuelled ‘bull market in everything’ rages on and proponents of SAA strategies can safely declare victory. Set and forget wins. Right?

Not so fast!

While traditional SAA strategies have delivered in the past, there’s no guarantee this will persist. In fact, we would argue that market conditions are such that an SAA approach will likely fail to deliver in the period ahead. Further, SAA has typically focused on the theoretical long term and realising long-term returns in a shorter-term reality may not happen. That reminds us of a famous quote whose true source is ‘unknown’ but is mostly attributed to part-time philosopher and full-time athlete, Yogi Berra, NY Yankee Baseball player:

“In theory, there’s no difference between theory and practice … in practice there is.”

Sometimes the long run is too long

Unless you have an infinite time horizon, you cannot necessarily rely on ‘long-run average market returns’ to deliver on your investment objectives. Historical averages don’t foretell the future. In particular, long-term averages don’t contemplate current valuations, future correlations, and certainly don’t consider the path to get there.

Taking each of those points in turn.

First, consider the elevated level of valuations across equities and fixed income (illustrated in the chart below), with P/E multiples at extreme levels and bond yields around record lows. The starting point matters, even for the theoretical long term. Even with a relatively optimistic outlook, it’s safe to say that expected returns in the period ahead are lower than seen historically.
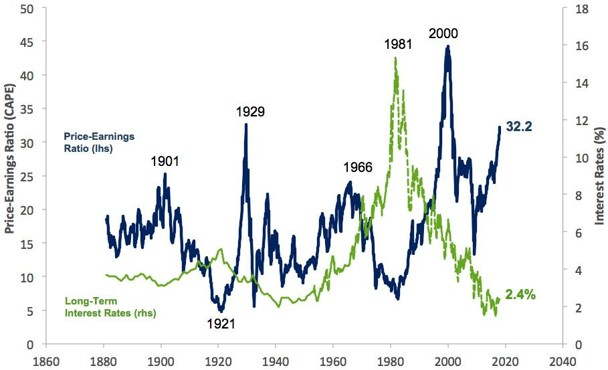

Source: Robert Shiller, Yale University, data to 31 December 2017. US 10-year sovereign interest rates or equivalent.

Second, the assumption that fixed income is defensive at all times and always offsets underperformance in growth assets is not borne out in the data. In fact, correlations between asset classes vary from period to period (see below). The average historical rolling 3-year correlation between global equities and global bonds of around 0.1 masks extreme changes in this relationship which has profound implications for diversification (maybe that lunch wasn’t ‘free’ after all).
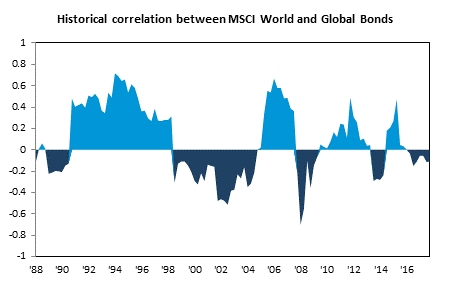

Source: Bloomberg, CFSGAM as of 31 December 2017. Rolling 3-year correlation based on quarterly data on the MSCI World Net Total Return USD and Citi World Government Bond Index (WGBI) USD Indices

Finally, and perhaps the most concerning of all, is that set and forget SAA strategies have never really contemplated the problem of sequencing risk (or the order in which events, often negative, happen). Those approaching retirement should care deeply about the path taken to achieve objectives, since there is much less time to overcome a major negative event such as a 40% equity drawdown. In this sense, SAA strategies have never really considered the retirement phase, and we believe investors with more defined investment horizons, should consider phasing out of SAA strategies at the appropriate time.

The options

So what options do investors have?

We believe there are three strategies:

  • Do nothing: Accept potentially lower returns and/or higher volatility in an existing SAA strategy.
  • Increase risk: Increase growth assets, ride the inevitable volatility, and hope for the best.
  • Increase active management: This could take many guises, including more dynamic asset allocation strategies, allocations to alternatives or appointing more active security selection.

Despite the challenges outlined, we think achieving long-term objectives is possible without materially increasing portfolio risk.


Kej Somaia is a Senior Portfolio Manager at CFSGAM. This article is for general information only and does not take in account your individual financial circumstances.

For more articles and papers from CFSGAM, click here.


  •   12 April 2018
  • 2
  •      
  •   

RELATED ARTICLES

Is FOMO overruling investment basics?

The most important investment decision you’ll ever make

Defence beats offence in investing

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.