Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 329

Managing risk using asset diversification

Employing a strategic asset allocation (SAA) can minimise the overall level of portfolio risk for a given level of return. The investment strategy sets target weights to the asset classes in a portfolio. Weightings are primarily allocated based on the investment objective, time horizon and, most importantly, the risk tolerance of the investor.

Combining uncorrelated assets

Support for SAA is provided by the fundamental benefit of portfolio diversification. Combining a group of assets that are less than perfectly correlated can reduce the overall risk of a portfolio for a required rate of return. The main theory, known as Modern Portfolio Theory, was pioneered by Harry Markowitz for which he was later awarded a Nobel Prize (for Graham Hand's interviews with Mr Markowitz, see here and here).

It is centered on the notion that the return of an asset should not be viewed in isolation but assessed on its contribution to the overall portfolio risk and return. The portfolios that provide the highest return for a defined level of risk fall on what is called the efficient frontier. This combination of assets is deemed to have greater diversification and be less susceptible to nonsystematic risk.

To illustrate the risk and return benefits of a SAA in a portfolio, 10 year back-tested data has been provided for three portfolios with different risk profiles: Conservative, Balanced and High Growth.
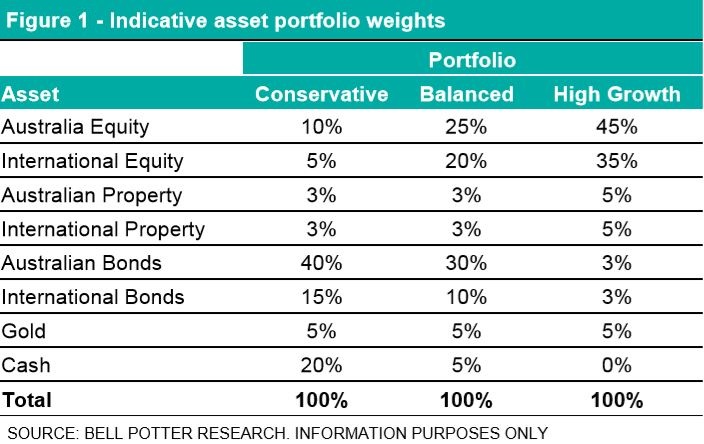
The portfolio asset weightings have been based on the corresponding BetaShares ETF Model Portfolios of the same risk profiles. This example is provided for information purposes only and is not intended to reflect the actual performance of the model portfolios they have been based on. Risk profiles of each model portfolio are produced in accordance with the Australian Prudential Regulation Authority’s (APRA) standard risk measure.

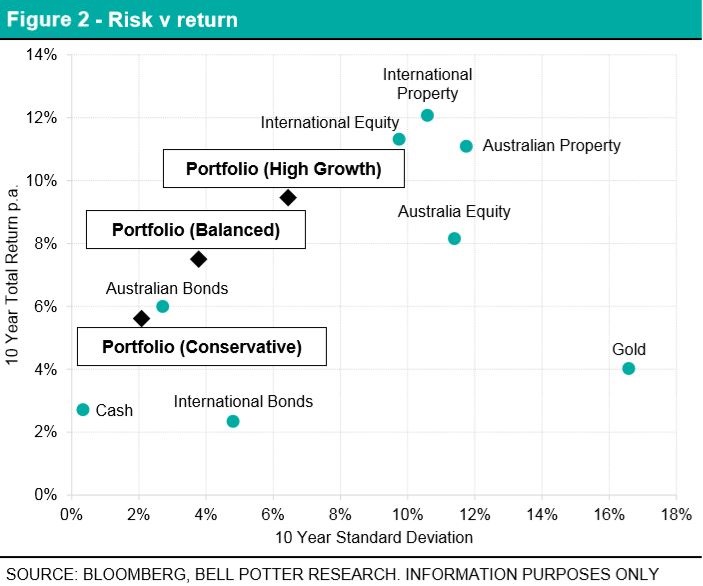
In Figure 2, we have calculated the performance over a period of 10 years ending 30 September 2019, with monthly rebalancing back to the target SAA weights. Broad market cap weighted total return indices are used to generate asset class returns, focusing on indices that are commonly tracked by ETFs.

Figure 2 illustrates that each of the portfolios can be seen as ‘optimal portfolios’ that broadly fall on the efficient frontier. Compared to a portfolio of solely Australian Equity, the ‘High Growth’ portfolio provided a higher 10-year return and lower risk whilst having a monthly return correlation of 92.4%.

A 100% weighting towards Australian Equity would have been a sub-optimal portfolio and an inefficient investment strategy over the 10 years. This highlights the importance of asset diversification in a portfolio and the long-term risk versus return benefits it can provide.
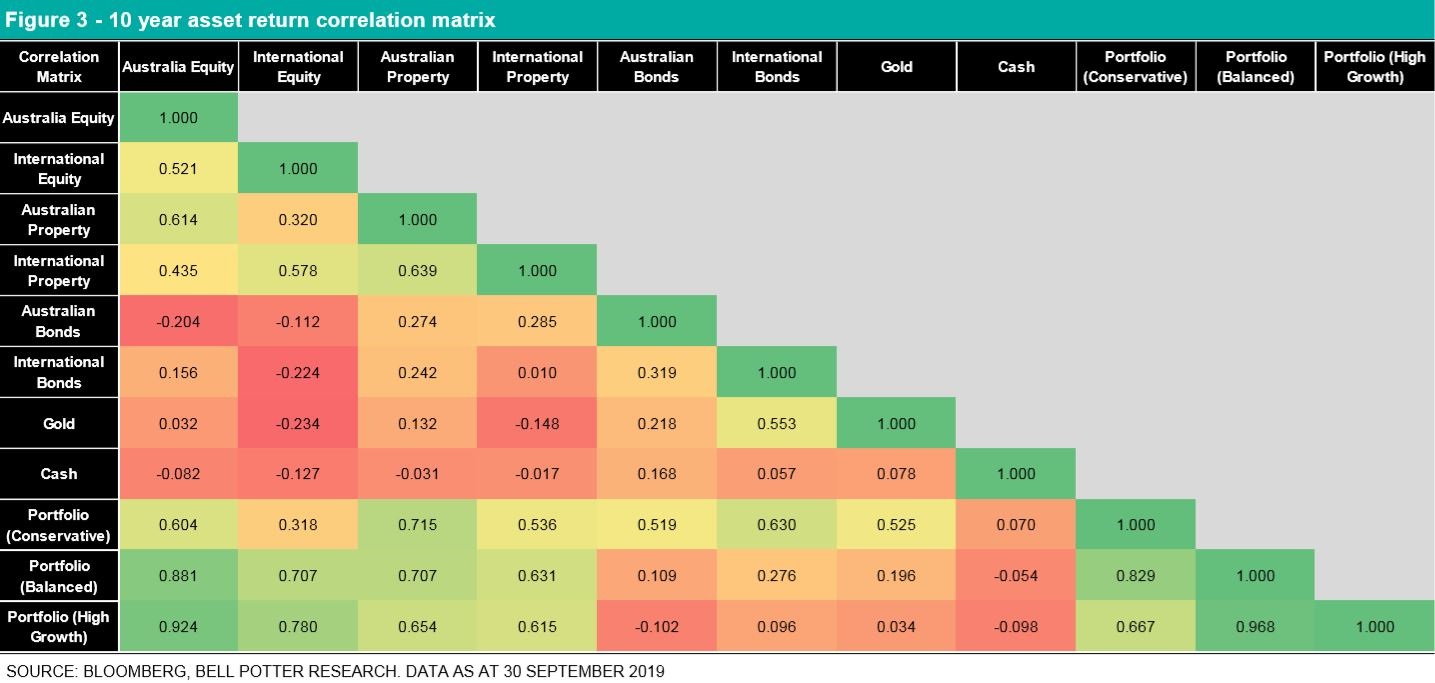
Correlations in returns between different asset classes are also relevant in building a portfolio. Figure 3 shows a 10-year correlation matrix, including the blended portfolios described above. It's notable that even a 'balanced' portfolio has a high correlation to equities.
The results also show the higher returns come with greater 'risk', measured by the standard deviation. These are the classic trade offs expected under Modern Portfolio Theory.


Will Gormly is an ETF/LIC Specialist at Bell Potter Securities. This article is for general information only and does not consider the circumstances of any investor.

Firstlinks provides regular reports on LICs trading at discounts and premiums in the Education Centre.


  •   23 October 2019
  • 2
  •      
  •   

RELATED ARTICLES

Putting portfolios together when the world is falling apart

Stars align for fixed income

Do Government bonds still have a role to play for Australian investors?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.