The August reporting season was far better than originally feared by many market participants. Analysts downgraded aggregate earnings by close to half a percent against an historic average of 0.8%. Downgrades were mainly on well-publicised cost headwinds, including raw materials price inflation and rising wages combined with now more expensive debt.
Pleasingly, offsetting costs, revenue growth was far stronger than expected, particularly for industrial companies. ASX200 non-financial revenue has been upgraded by 0.8% for the next 12 months, amongst some of the largest revenue upgrades in the last 20 years.
Fear leading up to the reporting season
There was a lot of uncertainty in the past 12 months, as the world moved from pandemic fears to the reopening of economies, while rampant inflation also caught the world by surprise. The share market is a fantastic gauge for fear and greed and has been on a rollercoaster ride, with investors switching from inflation fear to recession fear.
Consumer and corporate confidence plunged, and news reports of falling house prices become common place. As central bankers in Australia (and overseas) appear committed to raising rates, analysts were consistently downgrading the earnings outlook for corporates.
This reporting season was heavily anticipated, as investors prepared to assess just how bad the state of our economy is.
And the truth is, it’s not that bad.
How we fared on specific companies
Consumer sentiment, by and large, seems to be holding up well. Most retailers reported strong FY22 performances and even the July and August trading updates have been exceptional (partly due to cycling lockdowns last year in Sydney and Melbourne).
The likes of JB Hi-Fi (ASX:JBH) and Super Retail Group (ASX:SUL) have both seen strong share price recovery post result as trade remains buoyant.
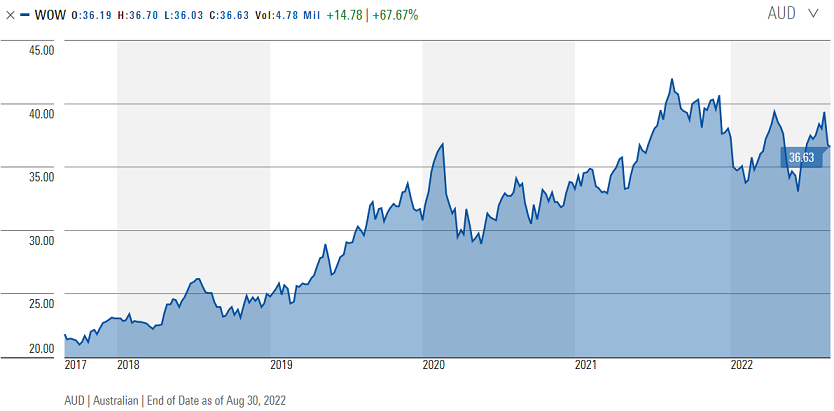
Consumer staples such as Coles Group (ASX:COL) and Woolworths Group (ASX:WOW) that have been the investor favourites off the back of expectations they would be inflationary beneficiaries, have both disappointed. They have been unable to pass on all the cost inflation to consumers and say they need to provide more promotions to draw consumers into stores.
Source: Morningstar.com
Not surprisingly, costs were highlighted as an issue for most businesses during reporting season, though most are able to pass through higher prices. Labour costs have been cited as most acute and the margins outlook over the next 12 month will be under pressure. This is perhaps an indication that inflation is likely to be elevated for some time yet.
Housing stocks experienced continued demand and there is an extended pipeline for the building materials businesses. We are seeing sharp falls in forward new builds as rates rise. For building materials businesses though, rising cost pressure is the main issue, with many unable to offset this with price increases. This is the area of concern in the next 12 months as demand falters.
Commodities businesses have mostly reported strong revenue growth, however they have been dampened by sharp rising costs. Despite being awash with free cash flow, many have chosen to pay out less than expected in dividends, as they contemplate acquisitions and growth in capital expenditures.
Mixed results from tech
The big laggard in performance over the past 12 months has been the technology sector. It is true that most of them have reported better results, although this is more as a result of cost savings, rather than a brighter revenue outlook.
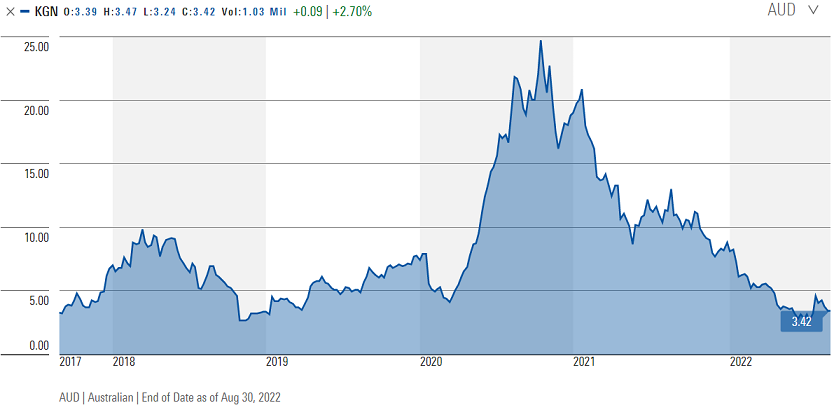
Equally, we have heard from many unprofitable businesses this season that are setting out a clear path to profitability and have subsequently been rewarded by sharp share price jumps, some of up to 50% on the day. One such company is Kogan (ASX:KGN).
Source: Morningstar.com
We also seen takeovers in this sector as many of those fast-growing businesses are now trading on their cheapest revenue multiples in years. Aerial imagery technology and location data company, Nearmap (ASX:NEA), is a good example, defying sceptics and delivering good results with a takeover bid at a 40% premium.
Some of the other bright spots of this reporting season also include likes of China-facing companies such as Treasury Wines and A2 Milk. Both former market darlings underpinned by structural demand from Asian consumers experienced significant earnings challenges as China has undergone regulatory reform and lockdowns. Pleasingly both have now come through with strong outlook for the coming years as they overcome near term challenges. We believe businesses such as these will continue to deliver returns regardless of economic cycle.
In better shape than expected
There has never been a dull moment during this reporting season, and it was good to see many corporates continuing to experience buoyant trading conditions and managing rising costs. We are heading into a weaker FY23 as consumers and corporates tighten their belts, though we are still expecting above trend earnings growth in the high single digits (excluding resources companies). In short, our economy still in good shape.
Jun Bei Liu is Lead Portfolio Manager, Alpha Plus Fund at Tribeca Investment Partners, a specialist investment manager partner of GSFM Funds Management, a sponsor of Firstlinks. The information in this article is provided for informational purposes only. Any opinions expressed in this material reflect, as at the date of publication, the views of Tribeca and should not be relied upon as the basis of your investment decisions.
For more articles and papers from GSFM and partners, click here.