Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 244

Retained profits a conspiracy against super and pension funds

In Part 1 of this series, we showed that the company tax rate has no impact on the amount of after-tax dividend received by an Australian shareholder.

This Part 2 examines whether a company should retain earnings or pay them as dividends to shareholders. Fund managers often advise that it is best for companies to retain profits and redeploy the capital to generate attractive returns. This advice ignores the tax implications for different types of investor.

Better for superannuation and pension funds to receive dividends

Retaining after-tax profits in a company in Australia means that from each $100 in company profit before tax, $70 is reinvested by the company (after the 30% tax). The cost to a shareholder of investing that $70 in the company is the forgone after-tax dividend.

This is $53 or $65.50 for an individual after tax, depending on the personal tax rate. This might seem a good deal for these shareholders, but the deal becomes less than favourable when capital gains tax (CGT) is taken into account.

For a superannuation or other low tax-paying shareholder, however, the retention by the company is singularly unattractive. The cost to the shareholder of investing that $70 is the foregone after-tax dividend of $100 if the shareholder is a pension fund or $85 if the shareholder is a superannuation fund.  Neither of these represent an attractive means of adding $70 to their investment in the company.  Companies do need to retain capital in order to continue to operate and to expand but retaining some of their after-tax earnings is an easy and indeed lazy way for the directors to grow capital.

CGT implications make it even worse

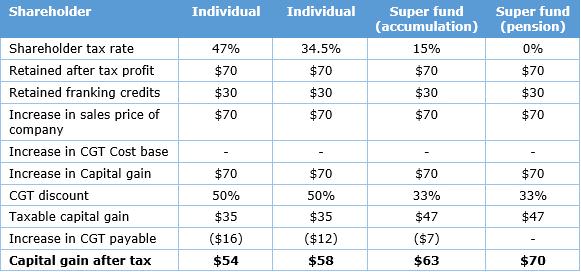
Consideration of CGT does not improve the position. Retaining an after-tax profit of $70 within the company rather than distributing it as an increased franked dividend only makes sense if it increases the value of the company by at least $70. For CGT purposes, the retained after-tax profit does not change the cost base for future calculation of CGT.

If the shareholding is sold having held the shares for more than 12 months, the position becomes:
Consider the ‘dividend after tax’ scenario modelled in the table last week, reproduced below.
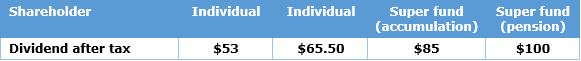
The impact on a shareholder of investing $70 into an Australian company because the company did not distribute a dividend and retained the $70 will be:

  • individual shareholder on a marginal tax rate of 47% - instead of receiving an after-tax dividend of $53, the after-tax benefit if sold at that time would be $54, or close to a line-ball.
  • individual shareholder on a marginal tax rate of 34.5% - instead of receiving an after-tax dividend of $65.50, the after-tax benefit if sold at that time would be $58.
  • superannuation fund shareholder on a tax rate of 15% - instead of receiving an after-tax dividend of $85 the after-tax benefit if sold at that time would be $63.
  • pension fund shareholder on a tax rate of zero - instead of receiving an after-tax dividend of $100 the after-tax benefit if sold at that time would be $70.

Both the superannuation fund and pension funds would be significantly better off if the company distributed the profits rather than retained then in the company, and then raised new capital as required in other ways, including from the shareholders who received the dividends.

The case for dividend reinvestment rather than retaining earnings

Retained after-tax earnings is an easy and lazy way for company directors to increase or retain capital but it is a conspiracy against low tax-paying Australian shareholders. The alternatives would be for the directors to justify the need to raise capital by a share offer to shareholders and the market.

Of course, directors could encourage dividend reinvestment by making it more attractive. With dividend reinvestment, the company retains the after-tax amount of $70 but the benefit of the franking credit is distributed to the shareholders.

Further, for tax purposes, the shareholder has invested $70 in the company and this is reflected as an increase in the cost base for future CGT purposes whenever the shares are sold. The company’s value has still increased by $70 but so has the cost base so there is no immediate CGT liability if the shares are sold at this time.

Company directors should be asked why they do not seem concerned at the tax inefficiency of retaining after-tax profits.

(Note that no comment is made here on the proposed Labor Party policy to stop refunds of excess franking credit. Labor is not proposing an end to dividend imputation, and there is too much uncertainty about whether Labor will be elected, whether they will change their policy or whether they can pass it into legislation).


Graham Horrocks is an actuary specialising in financial planning and superannuation, and a former General Manager, Research & Quality Assurance, with Ord Minnett. Since 1999, he has been an independent financial adviser. The article was reviewed by Geoff Walker, former Chief Actuary at the State Bank of New South Wales and winner of the 1989 JASSA Prize for published research on the implications of the then relatively-new dividend imputation system.


  •   14 March 2018
  • 1
  •      
  •   

RELATED ARTICLES

What might the Tax White Paper say on imputation and CGT?

Completing the reform of CGT: tax real losses like real gains

Is the government being honest with us about its business CGT changes?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Retirement

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

2026 is not 1999

The US market looks eerily similar to the dot-com era with soaring AI spending and tech giants dominating returns. But one difference separates today’s boom from the dot-com bubble and it could determine what happens next.

Planning

Taxing time for trusts

Trusts are facing a shake-up, but an overhaul may not be necessary. Families can explore restructuring strategies that preserve succession and the asset protection benefits that have made these structures valuable.

Economy

Why the US economy is stronger than you might think

War, inflation and higher rates were expected to derail America. But has the market got it wrong? Three forces are driving the economy beyond expectations, revealing implications for stock prices and portfolio positioning.

Gold

How much trust is in your portfolio?

Everyone talks about diversifying assets. Far fewer think about diversifying trust. As inflation, debt and market assumptions collide, the question is whether portfolios need greater protection from unexpected outcomes.

Retirement

Retirement in reality - 7 months in

Seven months into retirement, I'm still uncovering surprises. This month was spent reflecting on the slow pace of health change, the myth of neatly scheduled part-time work and the unexpected persistence of retirement guilt.

The new geography of technology leadership

The next chapter of technology may not belong to the companies or business models many expect. As the landscape shifts, some opportunities are emerging in places that remain surprisingly overlooked by global markets.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.