Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 319

Retirees facing steep increases for basic items

The ASFA Retirement Standard benchmarks the annual budget needed by Australians to fund either a 'comfortable' or 'modest' standard of living in the post-work years. It is updated quarterly to reflect inflation and provides detailed budgets of what singles and couples would need to spend to support their chosen lifestyle.

What does modest and comfortable mean?

A modest retirement lifestyle is considered better than the age pension but still only able to afford fairly basic activities.

A comfortable retirement lifestyle enables an older, healthy retiree to be involved in a broad range of leisure and recreational activities and to have a good standard of living through the purchase of such things as:

  • household goods
  • private health insurance
  • a reasonable car
  • good clothes
  • a range of electronic equipment
  • domestic and occasionally international holiday travel.

The June quarter 2019 figures indicate that couples aged around 65 living a comfortable retirement need to spend $61,522 per year and singles $43,601, up 0.8% for each on the previous quarter. At the modest level there was an 0.6% increase for singles and a 0.5% increase for couples.

These various changes are more or less in line with the All Groups CPI 0.6% increase between the March and June quarters.

Over the year to the June 2019 quarter, costs were up around 1.5% for couples at both the comfortable and modest levels, compared to the 1.6% increase in the All Groups CPI. This equates to couples needing to spend $918 more a year, and for singles the amount is $648.

Budgets for older retirees rose from the previous quarter by around 0.7% at the comfortable level and by 0.5% at the modest level.

Many retirees would have welcomed the recent decision to decrease the deeming rate in the asset test for the age pension but at the same time they have been facing increased costs of living and lower returns from investments, such as term deposits. Having sufficient savings in superannuation to support the lifestyle Australians want and deserve in retirement is an imperative. Moving to 12% for the Superannuation Guarantee is a necessity for those not yet retired.

Prices that have risen substantially

However, while the increase in the headline rate of the CPI might not look large, retirees have been facing significant increases in the price of many necessities of life. The drought has impacted the prices of a range of foods, the cost of private health insurance continues to grow at around twice the general rate of inflation, and petrol prices are up.

The costs for retirees that increased substantially over the last 12 months are:

  • Price of bread up by 4.8%
  • Price of beef up by 6.0% and lamb up by 13.5%
  • Price of milk up by 2.9%
  • Price of fruit up by 4.9%
  • Price of vegetables up by 6.2%
  • Price of beer up by 2.5%
  • Property rates up by 2.3%
  • Price of hairdressing up by 2.9%
  • Price of private health insurance up by 3.25% on average
  • Price of dental services up by 2.3%
  • Price of domestic travel up by 3.5% and price of international travel by 4.1%

The most significant price increases in the June quarter were automotive fuel (10.2%), medical and hospital service (2.6%) and international holiday, travel and accommodation (2.7%).
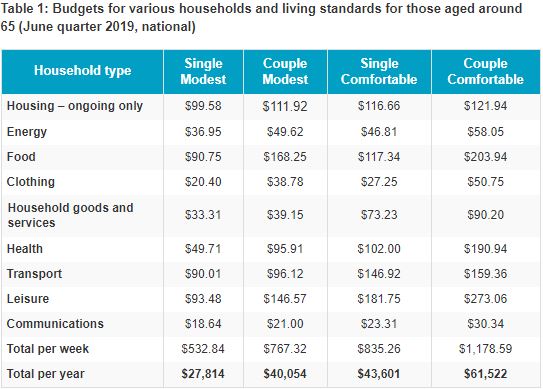
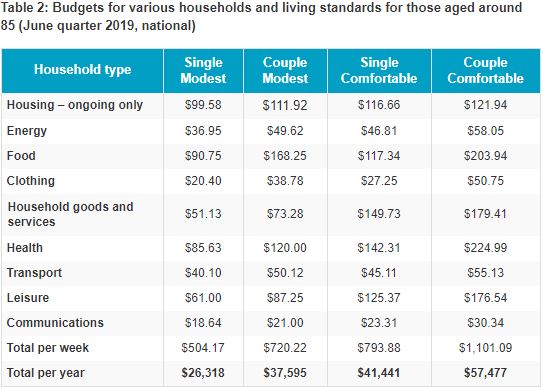
The figures in each case assume that the retiree/s own their own home and relate to expenditure by the household. This can be greater than household income after income tax where there is a drawdown on capital over the period of retirement. All calculations are weekly, unless otherwise stated. Annual figure is 52.2 times the weekly figure.

More information

Costs and summary figures can be accessed via the ASFA website. ASFA provides individual calculators to help Australians plan for retirement. Australians can find out more about superannuation on the independent Super Guru website.


Martin Fahy is Chief Executive Officer of The Association of Superannuation Funds of Australia (ASFA), the peak policy, research and advocacy body for Australia’s superannuation industry. This article is general information and does not consider the circumstances of any person.


  •   13 August 2019
  • 5
  •      
  •   
5 Comments
Frank
August 14, 2019

Most important to realise is all these numbers assume you own your own home. This will become increasingly uncommon putting a lot of pressure on older folk.

Graham W
August 16, 2019

What a load of rubbish that retirees need $65k pa. I know many pensioners solely receiving the age pension that have full and active lives. As long as you own your place of residence this is pretty much a given,apart from mainly the capital cities. We maintain a large home ,3 vehicles and lots of holidays towing a luxury caravan,more like $50k pa.
We all started as frugal baby boomers and know how to make a quid stretch ,without economising too much.The north of WA is chokka with caravanners enjoying the good life,few need $60k pa to live a life in their unit doing little but watching the goggle box.Economists are rubbish.

Peter W
August 17, 2019

Graham W,
I would suggest that you may not represent all retiree's. I think I can make a number of assumptions about you.
You are obviously blessed with extremely good health as health can be a major cost to a retiree. Also i wonder if you even have private health cover which is another cost. You don't have any diet issues as the cost of food if you have an intolerance is much higher than usual. Also you obviously don't travel overseas or if you do it is to very low cost destinations on a low budget and a rare occasion. Also when I consider you own three vehicles and a caravan and considering the depreciation, running costs and the maintenance cost on your home I would like to see look over your finances to see how you manage on $50k a year. Sorry but I very much doubt your costing.

Roger Farquhar
August 16, 2019

I would think that these sums are conservative and are dependent on what you consider to be comfortable. Our housing - rates and insurance - are far more than allowed and then there are the inevitable replacements due to wear and tear.

Yes there are retirees on the road - they crawl along in high gear to save fuel and budget from one park to the next.

Geoff
August 19, 2019

I've run my personal numbers for (retired) life at 60 and they're certainly way, way higher than the comfy / miserable numbers that are forever being touted and upgraded by ASFA. I can't see that all that much will change between 60 and 65. People should interrogate them and come up with their personal costs and work backwards from there. Guidelines, not rules.

You just don't get two phones, an internet connection and a "sinking fund" style allowance for replacing a couple of laptops and/or tablets every five years or so for $30.34 a week (communications/comfy/couple/65). Not even close. And that's modern day essential for a cohabiting couple, I'd suggest.

And is wine under food, health or leisure? :)


Leave a Comment:

RELATED ARTICLES

Retirement affordability myths

Clime time: Inflation cruels a comfortable retirement

Why spending more in early retirement can improve lifetime income

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.