Market uncertainty is not new. In fact, there have been 12 bear markets in the past 25 years. However, 2020 was a year when investors experienced almost the full range of market behaviour, from the fastest fall in recent history to the sharpest recovery on record.
S&P 500 and S&P/ASX200 Total Returns in 2020
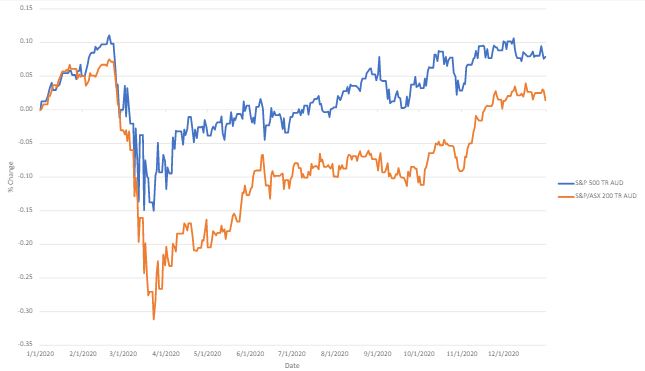
Source: Morningstar Direct
With a bit of certainty now creeping back in, it’s a good time to review what lessons we can take out of the last 12 or so months to navigate future crises.
Here are my top six lessons for investors:
1. Averages don’t count
There’s a joke about averages, where a statistician has his head in the oven and his feet in the freezer and says, “On average, I feel fine.”
For investors, the average may feel fine, but the reality is pretty dire.
During times of extreme market stress, it’s easy to fall victim to behavioural biases such as loss aversion, anchoring or herd mentality. But this type of behaviour is almost always detrimental to long-term superior returns.
It’s one of the hardest parts of investing — especially at the extremes — but I believe investors need to find a way to play devil’s advocate with themselves. This means asking tough questions about why they are making certain investment decisions, and properly analysing both the opportunities and risks that the current market presents.
2. Balance discipline and flexibility
There is a fine line between being disciplined and being dogmatic. One of the keys to successful investing is reacting to changes faster than others in the market and not being static or inflexible. Unfortunately, it often seems that the more discipline people find, the more rigid they become.
It is critical to understand the data points that may appear to be conflicting during the most severe part of a market correction. As an active manager, I believe this is the most important period for adding value for our clients.
3. Cheap doesn’t mean safe
Valuations are always important but investors should not fall into the trap of thinking that 'cheap' means 'safe' during a crisis.
During a financial crisis, the lines between growth, value and other factors blur. What was once growth is now value and what was once cheap may now be heading for bankruptcy. As a quality investor, I certainly appreciate the fundamental argument of not overpaying for a future earnings stream, especially in a crisis. But it’s about quality for me, not cost. I focus on certainty of earnings and strong balance sheets.
4. Use the 'sleeping' test
A good rule of thumb for investors is that if a stock is keeping you awake at night, sell it — or at least sell it down to a level where you can sleep.
One of the best ways to ensure a good night’s sleep during a crisis is to invest in companies with quality and experienced management teams. This experience will stand them in good stead during the crisis, and management teams that know how to compound capital in tough times are more likely to prosper.
5. Start with 'what could go wrong'
The first step in investing is to avoid mistakes. That may sound pretty obvious, but it’s actually more complicated — and harder — than one might think. Before making any investment decisions, investors need to think carefully about what could go wrong with a company and then go from there.
If you don’t own it, you can’t lose money on it. As another favourite saying goes: 'I don’t have to fish in every pond, just the ones that have fish in them.'
6. It’s the things we love that ruin us
Investors often find that buying stocks is easy. It’s selling them when the trouble starts. Investors that focus almost entirely on the purchase price and then base their investment decisions on trying to sell at a higher price, are falling prey to 'anchoring' and are failing to assess a stock on its true merits in the current market, which is constantly changing. Price matters, but it’s not the only thing that matters.
Alignment of interest
I think that 2020 was the ultimate test for many investors. Volatile markets and an uncertain economic outlook in the wake of Covid-19 led to a lot of investor angst. But overarching these top six lessons is one source of truth for all investors: only invest with a manager that eats their own cooking.
A fund manager’s job is to compound each investor’s money, and it is important that the manager and the investor have aligned interests. For more certain investment outcomes, I believe it’s crucial to invest with fund managers who have a majority of their net worth invested into the same investment options that they offer for their clients.
Why? I find this focus automatically changes investment management behaviour. It changes from simply beating a benchmark to producing real returns. It ensures the investment manager is serious about adapting and evolving to different market conditions.
A focus on quality, combined with an adaptive process that avoids being too dogmatic about what has worked in the past, is the key to compounding capital over the long run. In my view, a focus on the forward nature of quality, purchased at suitable prices, is the best defence over time.
No one wants to overpay for assets, so in that sense, we are all value investors. It is just that some of us are more dogmatic about it than others.
Rather than simply asking 'what is the price?', the real question should be 'what am I getting for the price I’m paying?'. On this basis, I believe there are still good opportunities for investors in the current market.
Rajiv Jain is Chairman and Chief Investment Officer of GQG Partners. This article contains general information only, does not contain any personal advice and does not consider any prospective investor’s objectives, financial situation or needs.