Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 58

The ‘new normal’ and demographic change

From day to day, we are barely conscious of our own ageing, never mind the long term trends in Australia or the world. You might receive a sudden jolt when you see an old friend after a 30 year absence, all wrinkles and paunch, and wonder if you have also changed as much. Or you look back and realise you’ve had the same job for 30 years, or lived in the same house for 20.

The one time we all consider the passing and future decades is when we approach retirement, and think about how long our money needs to last. However, we cannot plan our own financial outlook without considering an economic or global context. For example, if we retired at a time when the number of retirees was small in proportion to workers (the so-called ‘dependency ratio’), then we could be more confident that rising tax revenues and economic growth would support age pensions, health systems and public transport. Notwithstanding the introduction of compulsory superannuation over 20 years ago, the majority of Australians will continue to access at least part of the age pension, and this reassurance about future services is crucial for their retirement plans.

But what if that low dependency ratio is in the past? In recent weeks, Treasurer Joe Hockey and other Federal Government ministers have made it clear that the budget deficit cannot be allowed to blow out to sustain the levels of support traditionally provided. We have a pension system which exempts the family home, and a couple sitting in a multimillion dollar house with $1 million in other assets and annual income of $60,000 can draw a part pension with all the associated health benefits (hearing aid cost $5,000, supplied for free, come back for another next year). The current debate on increasing the pension age from 65 to 70 is scratching the surface on likely changes.

Consider the following table, showing the proportion of the Australian population in each age group: the younger people up to 19 years of age; the large bulk of the working population from 20 to 64; and the older people (currently pension age) of 65 years and older.
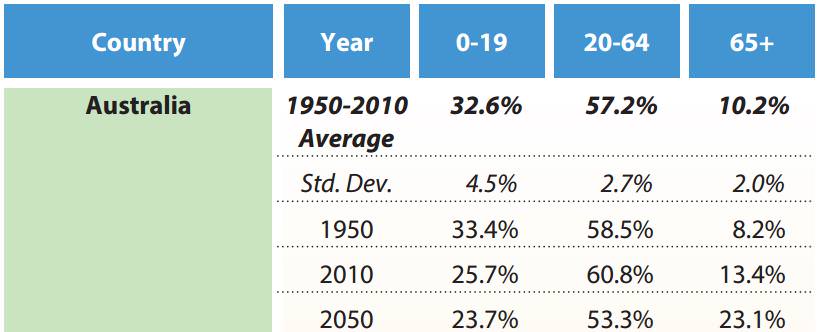
Source: Journal of Indexes, September/October 2013, ‘A New ‘New Normal’ In Demography and Economic Growth’, by Robert Arnott and Denis Chaves, page 25.

In 1950, only 8.2% of the population was over 65, but by 2050, it is expected to reach 23%. At the moment, two-thirds of people aged 65 to 69 are retired. For a person aged 65 expecting to live at least another 20 years, the majority of their remaining years will involve some level of disability or dependency. The costs of such services in Australia are a massive drain on public resources, as well as the age pension. There’s no doubt future entitlements will reduce, and we need to focus on the demographic changes that are coming, and not think as 2030 or 2040 as the never-never.

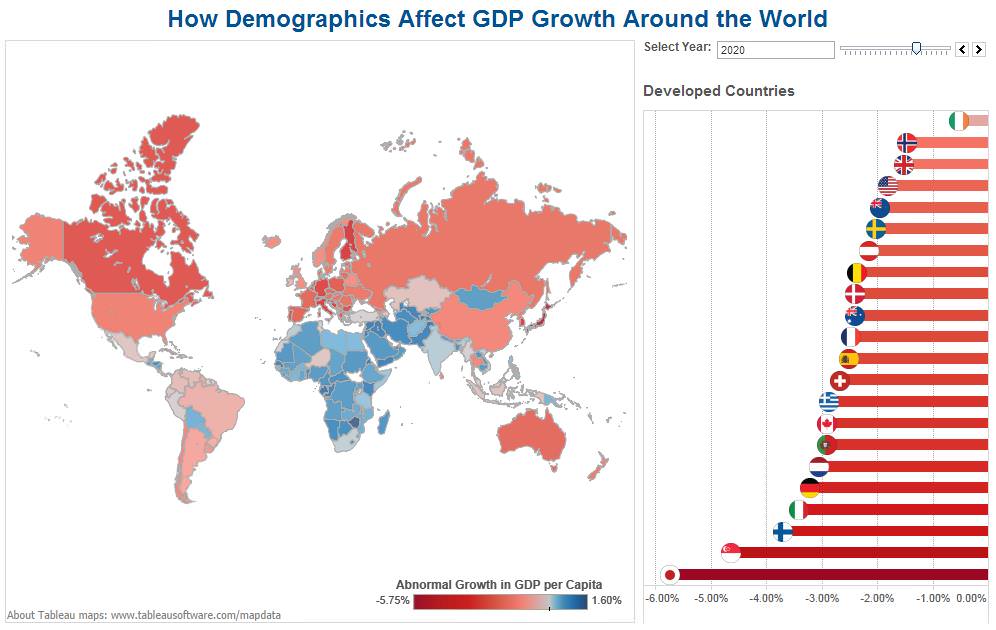
The Californian research and investment strategy company, Research Affiliates, has produced interactive maps which show the likely effect of demographic change on GDP for major countries around the world, including Australia. In addition, Robert Arnott and Denis Chaves have written extensively on the economic and social implications of these changes, as shown in the following article.

The first ‘infographic’, linked here, allows the user to select the year by moving the tab in the top right corner, and see the effect on GDP growth of demographic change in that country. For example, the figure below shows the year 2020.
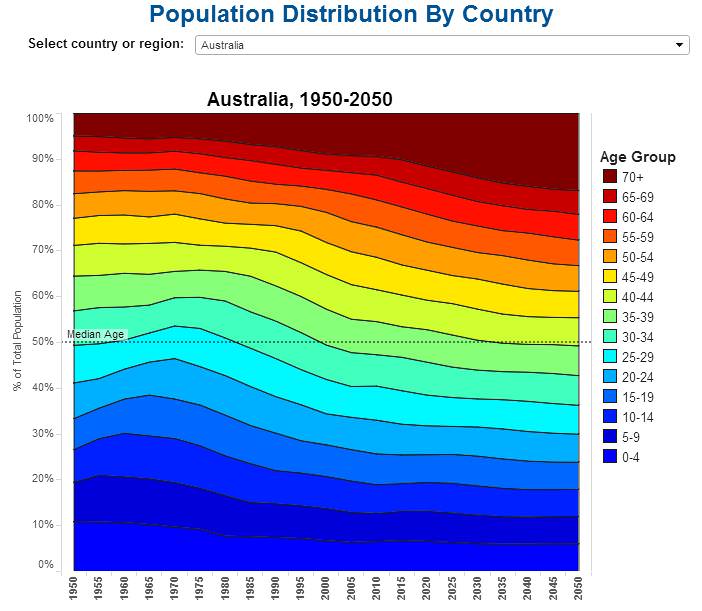
The second ‘infographic’, linked here, shows population distribution by country, with Australia shown below. The most notable increase is in the 70+ age group, accompanied by a rapidly rising median age.
Introduction to the Arnott and Chaves paper

This is background to the following paper by Rob Arnott and Denis Chaves of Research Affiliates. They argue there is a disconnect between what we take for granted given our recent experiences and what we should anticipate given simple arithmetic. We are not automatically entitled to fast-growing prosperity and ongoing high growth.

In recent decades, we have been blessed by the favourable demographics of a younger, more productive workforce which provided a growth tailwind. The reversal towards an older population will create more of a headwind, and our policies cannot simply spend our way out of trouble for as long as it takes. How we manage the transition will determine the quality of retirement for the majority of Australians.

(Note that the infographic reflects changes between demographics and GDP per capita growth based on the percentage size of each age group. This method results in more extreme forecasts as the size of each age group, especially retirees, continues to grow, while the following article uses an average of two methods that results in a smoother result).


  •   17 April 2014
  • 3
  •      
  •   
3 Comments
Geoff Walker
April 17, 2014

I'm somewhat more sanguine than many about society's ability to cope with demographic change.

Ultimately, the generation of rising standards of living comes from the human race's ability to become more productive through the invention of new and better ways of doing things. And there is no way that our ability to innovate is going to be muzzled by demographic change.

Rising standards of living can manifest in a number of ways beyond the simple real pay rise. Historically we have seen reductions in the length of the working week and increases in the proportion of workers who have accumulated the financial wherewithal to retire early voluntarily.

It's not a big leap to see that increased productivity arising from human ingenuity can be used to finance longer retirements arising from increased longevity.

Bruce Moon
April 17, 2014

I am becoming quite peeved at the lack of 'crap detection' on this topic.

The desire by the neo-conservatives to lower tax rates for the upper end remains their holy grail. To that end, they have a knack of misleading by misconstruing facts.

Yes, it is true that the 'boomers' are a tabular aberration. And, as this cohort passes the retirement age, they will add to the federal budgetary outlays.

No, it is not true that politicians should use past stats as a guide to the future.

POINT 1 -

as a cohort, boomers are far more wealthy than previous generations. While their Super contributions will not negate access to Age pension, it WILL limit federal outlays.

POINT 2 -

as a cohort, boomers are less fit then previous generations. The levels of obesity - caused in part by sedentary behaviour - will impact on mortality rates. While coffin sizes may need to increase, longevity will decrease over time.


When our ideologically driven pollies bandy out numbers to frighten, I wish researchers would focus on these two points to question the validity of the claims.

Cheers

V Clifton
April 21, 2014

Bruce Moon. I can't see how longevity will decrease over time. Drugs are continually being tailored to meet the percentage of the population who don't intend to help themselves. Mortality is the cessation of the economic boom for drug companies.


Leave a Comment:

RELATED ARTICLES

Mind the (expectations) gap: demographic trends and GDP

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.