Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 629

The DNA of long-term compounding machines

Investors are often trained to look for size as a proxy for safety. Blue chips, household names, and index leaders dominate portfolios not only because they feel familiar, but also because of herding bias – the psychological pull to follow the crowd rather than stand apart. But history shows that tomorrow’s champions are often built quietly, well before they attract mainstream attention.

Canva’s rise offers a case in point. Barely more than a decade old, the private design platform is now worth around $65 billion. It is more valuable than Telstra, Brambles, and Rio Tinto – companies that have taken over a century to build. While Canva is exceptional in scale, it highlights a broader trend: founder-led firms with aligned incentives and disciplined cultures will continue to reshape Australia’s corporate landscape.

Why incentives matter

The way leaders are rewarded has a direct impact on the way businesses grow. According to the Australian Council of Superannuation Investors, 91% of Australia’s top listed CEOs received a performance bonus last year, typically vesting over three years. This structure often drives short-term priorities.

Founders, in contrast, are rewarded only if their businesses thrive over decades. Their ownership stakes and reputations are tied to long-term outcomes. Their long-term motivation is reflected in bolder decision making, leaner organisational structures, and faster responses to change. For investors, understanding these differences is critical in assessing why some companies compound value more effectively than others.

Telltale signs of founder behaviour

Founder-led firms are not immune from challenges. Some stall, others remain niche, and a few will fail outright. But collectively they demonstrate a pattern of behaviours investors can analyse:

  • Capital discipline: prioritising sustainable margins and reinvestment over empire building.
  • Alignment: boards, executives, and shareholders cohesively building long-term value rather than chase personal gain.
  • Strategic patience: committing to opportunities that compound over decades, even when short-term sentiment resists.
  • Scalable structures: setting up organisation structures that ward off corporate bureaucracy and continue to proliferate the founder’s philosophy

These traits do not guarantee success, but they are observable markers that investors can use when evaluating businesses and management team’s decision-making.

Emerging examples

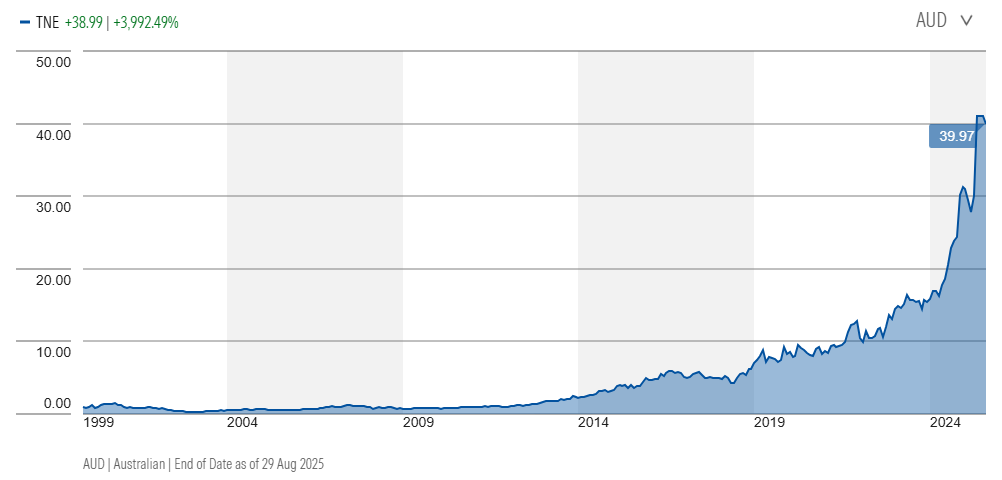
This mindset is visible across a range of Australian companies. Objective Corporation [ASX:OCL] in government software, Hansen Technologies [ASX:HSN] in specialised software products, and Macquarie Technology Group [ASX:MAQ] in cloud and data services have all grown under founder influence. Private firms such as Expert360 and Lakeba are building new models in talent platforms and applied technology. Even mature names like Technology One [ASX:TNE] retain founder DNA in their culture of customer focus and capital efficiency.
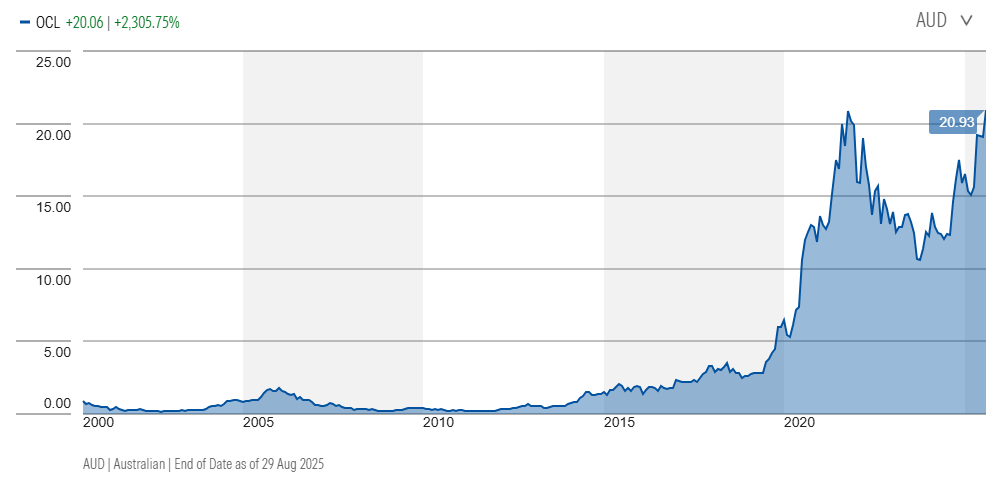
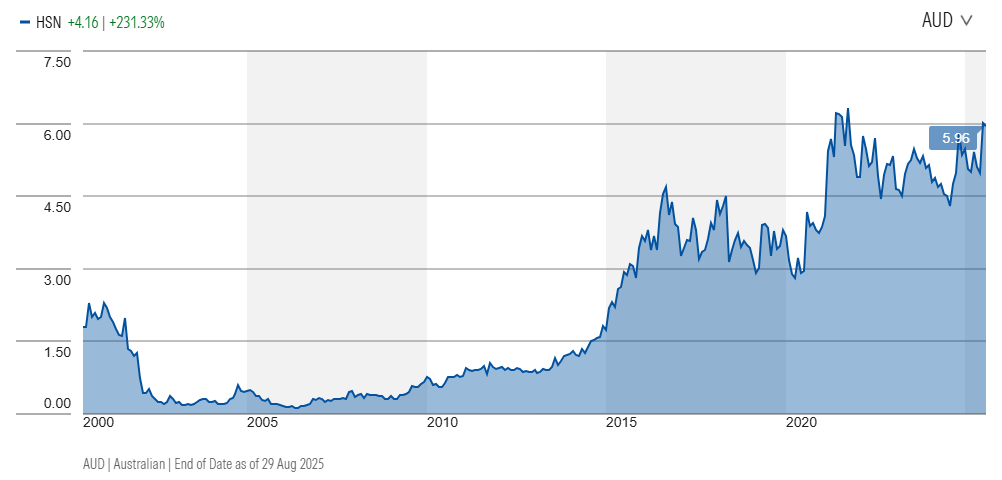
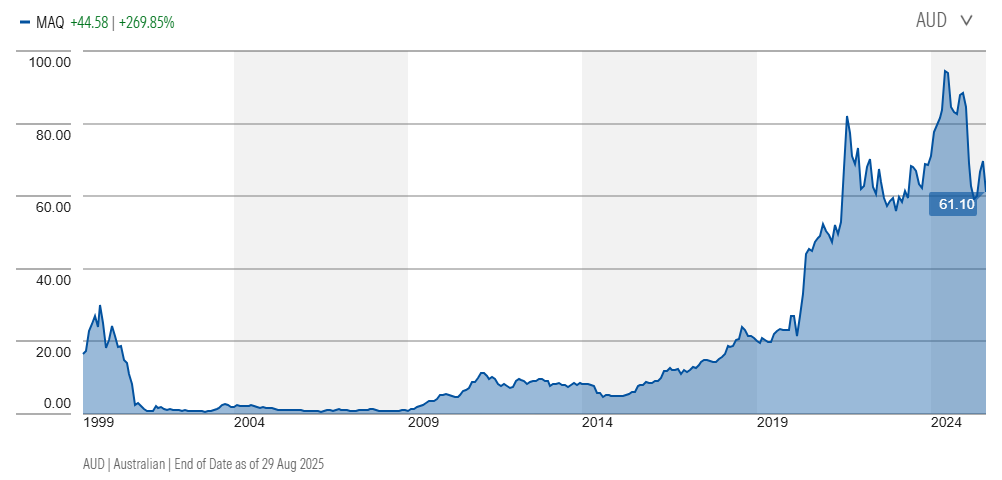
Source: Morningstar.com.au

These are not stock recommendations, but case studies of how founder structures can shape performance. For investors, the lesson is not just which names to watch, but what patterns to recognise when allocating capital.

The takeaway for investors

The next generation of wealth creation is unlikely to come from the obvious megacaps. It is more likely to emerge from founder influenced firms that combine scalable models with long-term alignment. By the time these companies appear in index products or attract heavy broker coverage, much of the edge is already gone.

Investors who want exposure to this trend need to build frameworks for identifying founder alignment early, before the crowd does. That means going beyond market capitalisation, looking at ownership structures, and assessing the decision-making culture that sits behind the numbers.


Lawrence Lam is the author of The Founder Effect (Wiley) and Managing Director of Lumenary Investment Management. He writes on leadership, markets, and the traits that define exceptional management. More at lawrencelam.org and lumenaryinvest.com. The material in this article is general information only and does not consider any individual’s investment objectives. Companies mentioned have been used for illustrative purposes only and do not represent any buy or sell recommendations.


  •   17 September 2025
  • 3
  •      
  •   

RELATED ARTICLES

Nvidia's CEO is selling. Here's why Aussie investors should care

Compare the pair: Expensive versus cheap

Lessons from the rise and fall of founder-led companies

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.