Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 415

Warning about timing of investments in ETFs and trusts

(This article republishes a previous warning at the end of the financial year about timing of distributions).

Most fund managers struggle to deliver a 1% outperformance after fees, and with the cash rate at 0.1%, investors need to eke out every bit of return they can find. So it’s important to know how investment structures work. In particular, the tax impact of investing after a distribution can be a trap for the unwary and cause unexpected leakage in tax.

Distributions from a unit trust

In a unit trust, all income received (including realised capital gains) is divided among unit holders based on how many units they hold at the time of a distribution. Unit holders must then include their share of this income (which may comprise dividends, interest, capital gains and franking (imputation) credits) in their own tax return in the year it was earned.

The same distributions are paid to all unit holders according to their holding on a particular day, whether or not the investor was in the fund one day or one year. Distributions are not pro-rated for investors who were not unitholders for the whole period. An investor may receive some of their investment back immediately as income if they invested just before a distribution.

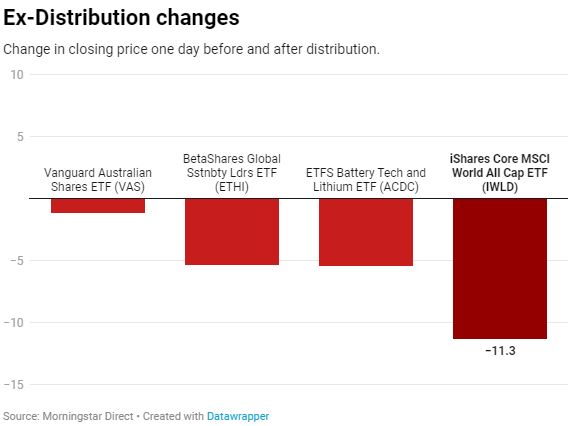
Immediately after a distribution is declared, the unit price of the fund will usually fall by the amount of the distribution, because the distribution reduces the fund’s assets. For example, these ETFs listed on the Australian exchanges fell heavily after their FY21 distributions.
Don't convert capital to taxable income

An investment in June that receives a distribution in July may be converting capital to taxable income. For example, if someone invests on 25 June when the unit price is say $1.00 and then a 10 cent per unit distribution is made on 30 June, the unit price will fall to 90 cents (assuming no market movement) at the beginning of July. The 10 cents will be taxable income in the hands of the unit holder in their tax return.

Obviously, the worst consequences are for individuals with high marginal tax rates where the distribution includes no franking credits. This might be the case for a global equity fund which distributes once a year with no franking credits from Australian companies.

Alternatively, an investor such as a tax-free charity or super fund in pension mode in an Australian equity fund might pay no tax and receive a franking credit, so a June investment might actually be favourable for them.

The only way to eliminate these effects would be for the fund trustee to make a daily distribution, but clearly this is not practical. The more often a fund distributes income during the year then the less of an issue this distribution inequity becomes. For example, most Australian equity funds distribute twice per year but most international funds only distribute once per year.

Other funds with particularly punitive outcomes for unit holders who invest close to a distribution date might be actively-traded funds in a rising market. They might have large capital gains on shares not held for longer than 12 months (and therefore, not subject to the 50% CGT discount factor). The distribution might contain a large taxable capital gain component.


Graham Hand is Managing Editor of Firstlinks. This article is general information and does not consider the circumstances of any investor.


  •   5 July 2021
  • 6
  •      
  •   
6 Comments
Davo
July 07, 2021

Hi graham, good and valuable article. My first ever investment was accepted on 30 June one year and I was stung badly....a lesson well learned. The Article howver would be much more valuable in May -June though, not a week too late for anyone to avoid the trap

CC
July 07, 2021

yes a very important reason why the supposed advantage of active ETFs over LICs is not what it's cracked up to be.

Peter Thornhill
July 10, 2021

Working in the funds management industry I remember well a new fund that we launched and it coincided with the governments allowance of a tax deduction for gearing into overseas funds. there was a surge of interest prior to the tax year end and then in July the fund distributed a 20% dividend. It was repeated the following year which meant that 'investors' had 40% of their capital returned within 2 years and a commensurate fall in the unit price. Avoid the trap, use a listed company structure.

Danny
July 18, 2021

You referring to LIC's Peter?

John Wilson
July 11, 2021

Although articles about investing in June highlight the problem, inherited previous unrealised capital gains can be a potential negative for new investors in unit trusts regardless of which month they might invest.

Geoff F
July 11, 2021

Good point John. Is there any reporting (daily basis) by funds which reveal their unrealised capital gains position so investors can determine how much CG they're buying ? I'm invested with one of the majors and I haven't seen any reporting along these lines.


Leave a Comment:

RELATED ARTICLES

Two of the best-kept secrets for the EOFY

Warning about investing in unit trusts in June

Warning about investing in unit trusts in June

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.