Growing up in Perth, escaping the mining industry was almost impossible.
Every second person seemed to work in mining, provide services to mining companies, or had a family member whose fortunes rose and fell with the iron ore price.
After moving away, I assumed I'd left most of that behind. Yet, here I am writing about BHP.
Perhaps that's no surprise. Whether owned directly, through super or via a fund, Australia's largest listed company sits in countless portfolios. In one way or another, a large portion of capital is tied to the fortunes of the resources sector.
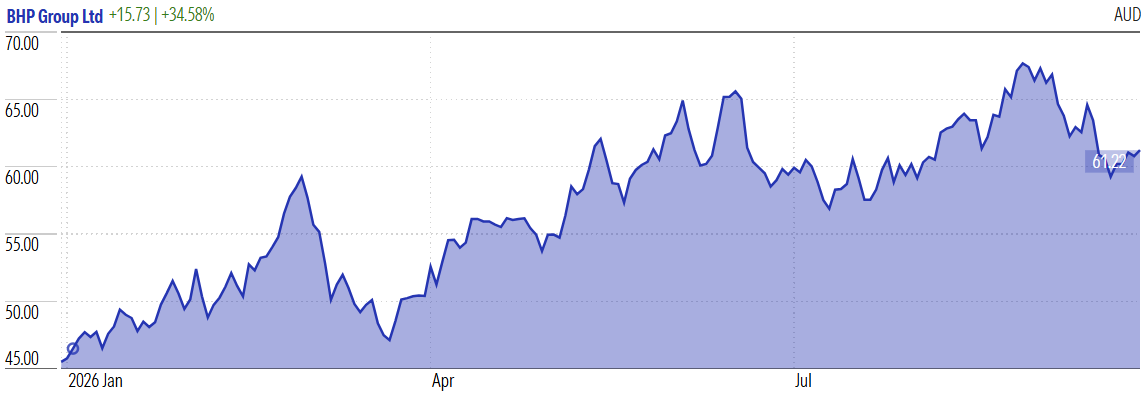
Shares hit a record $68 in late August, after results showed underlying profit jumping 30%, as well as a 65% jump in dividends. All figures that were unlikely to draw many shareholder complaints. But is there a need to be cautious?
Most companies are assessed based on their ability to grow revenue, take market share or improve margins. Mining is different. A company can have world-class assets, low production costs and excellent operations, yet still see profits collapse if commodity prices move against it.
In industry jargon, miners are "price takers". When commodity prices are strong, earnings often surge. When prices weaken, profits can fall just as quickly.
Yet when earnings jump, our instinct is often to extrapolate this. History suggests we’re at our most optimistic near cyclical peaks and most pessimistic near cyclical troughs.
Some perspective
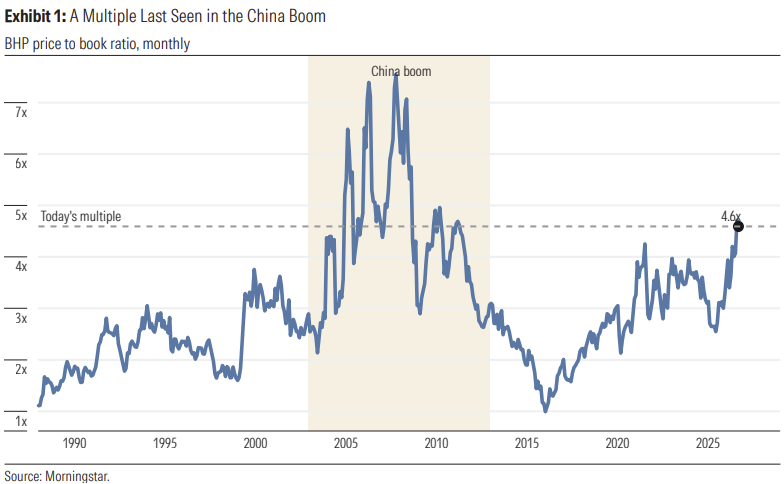
My colleague Lochlan Halloway recently performed an analysis to determine what expectations are already embedded in BHP’s share price. At present, it trades around 4.5 times book value, which is a lofty multiple for a cyclical business.
Using a standard valuation framework*, this suggests the company needs to generate a return on equity of around 30% over the long run. Not necessarily every year, but on average through the cycle. In other words, the market is expecting a very high level of profitability for a long time.
To put it in perspective, BHP generated a return on equity of 27% in its most recent financial year and this was a period that was reasonably favourable for commodity markets.
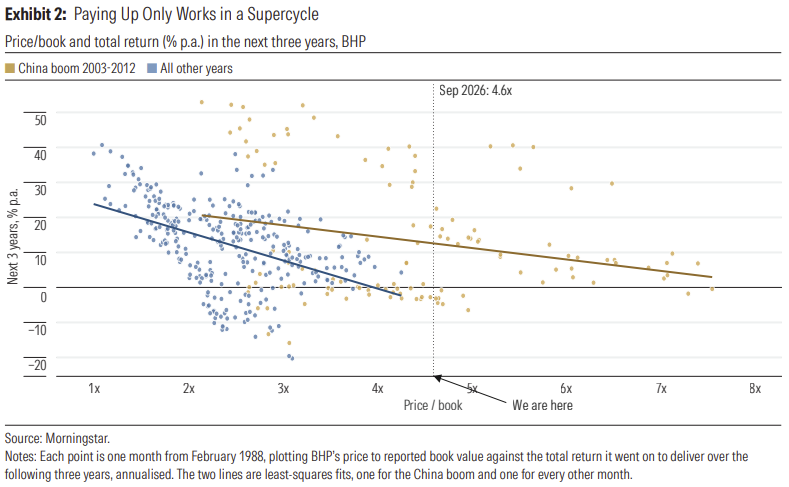
History suggests that paying such valuations can still be rewarding, but only under exceptional circumstances. The clearest example is during the China-led resources boom between 2003 and 2012, when industrialisation created a once-in-a-generation environment for miners.
Even investors who paid seemingly high valuations were rewarded as the boom proved larger and longer than most anticipated. Of course, the challenge is that periods like these are rare.
The role of copper
Copper has become increasingly important to BHP's future. Much of the investment case rests on themes like AI, electrification and renewables. All roads seemingly lead to higher copper demand. If these structural drivers translate into a meaningful and sustainable increase in consumption, current prices may be justified.
However, I find that compelling narratives often become embedded in prices long before they become embedded in reality. As prices move higher, producers have greater incentive to expand existing production, as well as explore alternatives.
The elephant in the room
For all the discussion about AI and electrification, it is easy to forget that the biggest force in commodity markets over the past two decades has been China. The country accounts for over half of global refined copper demand, yet demand seems to be slowing amid concerns about the economy.
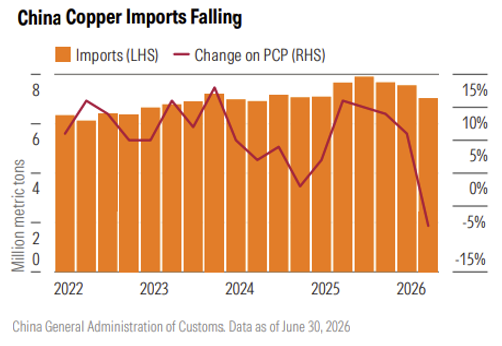
While investors focus on future sources of demand, a key question is whether they are paying enough attention to the world's largest existing source.
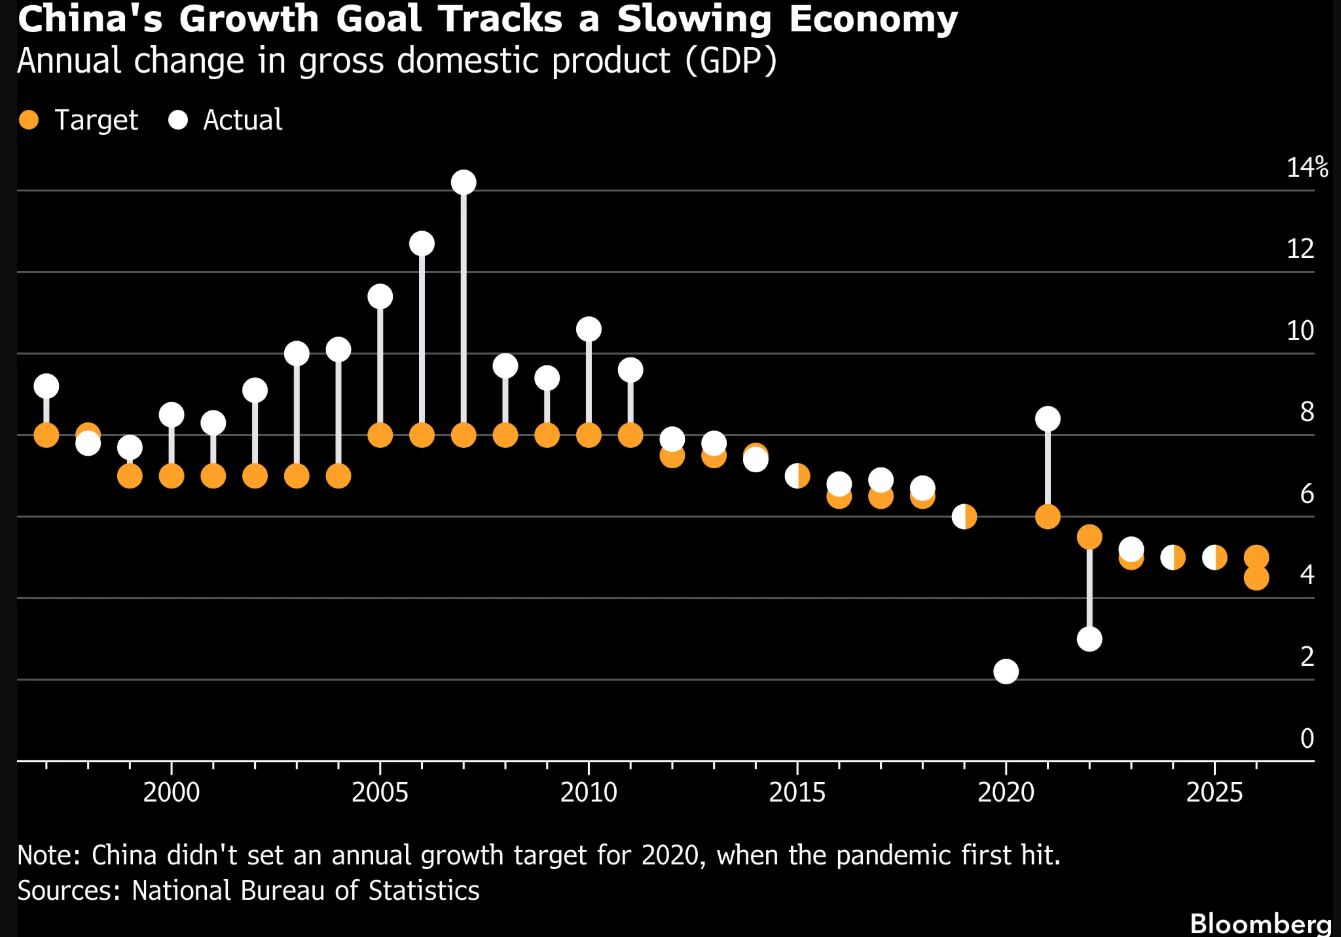
Indeed, it is industry consensus that the world will require substantially more copper than it does today, however, whether it requires enough to meet expectations is the difficult part.
It's often said that investing is the art of distinguishing between what is already known and what is not yet reflected in prices. In his book The Most Important Thing (2011), Howard Marks describes this as:
“First-level thinking says, ‘It’s a good company; let’s buy the stock.’ Second-level thinking says, ‘It’s a good company, but everyone thinks it’s a great company, and it’s not. So, the stock’s overrated and overpriced; let’s sell.’"
Concluding thoughts
If it isn’t already obvious by now, I am not a geologist, mining engineer or commodities forecaster.
Like most investors, I have no unique ability to predict where prices will be the next decade. Commodity markets are influenced by several complex factors like economic growth, advancement in technology, supply disruptions and so on. It is not my intention to make a grand call on whether copper is headed materially higher or lower from here.
However, it is worth delving into how other investors are thinking about such businesses. Investing is less about predicting the future than it is about understanding the expectations already embedded.
*Assume a standard set of assumptions for a perpetuity model: a 9% cost of equity, long-run growth of about 3%, and a business that distributes most of what it earns.
Simonelle Mody
***
Weekend Market Update
From Shane Oliver, AMP
Global share markets mostly rose over the last week helped by strong US economic data, a return of AI optimism and renewed hopes for a diplomatic solution to the Strait of Hormuz blockage. For the week US shares rose 1.2%, Eurozone shares rose 0.8% and Japanese shares rose 2.1% but Chinese shares fell 1.5%. The Australian share market remained under pressure falling another 0.8% not helped by ongoing expectations for RBA rate hikes on top of worries about the impact of rising oil prices, rising bond yields which act as a drag on share market valuations and falling property prices. The falls in the ASX 200 were led by utility, telco, energy and bank shares.
Gold fell on the back of increased expectations for Fed rate hikes and rising bond yields which raise the opportunity cost to holding gold, but Bitcoin broke decisively above $US80,000. Metal prices rose but iron ore prices fell as did the $A with the $US up.
Despite a fall early in the week on hopes for a diplomatic solution flowing from US/Iran talks during the UN General Assembly, Saudi Arabia moving to reopen its east-west pipeline and signs of more ships getting through Hormuz, oil prices rebounded as the talks didn’t appear to make much progress. Trump’s comments threatening to “annihilate” Iran again before then saying the talks were “very good” didn’t add much clarity. Iran has reportedly offered a plan to reopen Hormuz and revive nuclear talks but it sounds like the failed June peace deal and is contingent on the US unfreezing Iranian assets and removing its blockade so it may not get up or offer a durable solution beyond any short term relief. That said, Trump is likely to try and do what he can to bring down energy prices given the increasing probability of a Republican wipe out in the midterms, but the risks are high with the now more hardline Iranian leadership likely wanting to keep it bubbling along to inflict more damage on Trump politically.
Petrol prices in Australia at around $2.38/litre have now caught up with and overshot the rise in oil prices. This is partly due to a blow out in oil product prices relative to crude oil prices due to Ukranian attacks on Russian oil refineries which have curtailed Russian fuel exports. A failure to resolve the crisis could see oil head to $US150/barrel and petrol prices head above $2.70/litre.
The past week saw another surge higher in bond yields reflecting ongoing concerns about high energy prices adding to inflation, rising expectations for central bank rate hikes, worries about big budget deficits in the US and elsewhere, increased corporate borrowing to fund data centre investment, erratic US policy marking and a rising trend in Japanese bond yields leading to a reversal of the so-called carry trade. The US 10-year bond yield rose to its highest since 2007. As US bond yields are the base for global yields their rise has continued to flow through to Australia with the local 10-year bond yield rising to its highest since 2011. Bonds are oversold and due a tactical rally but their continued sell off despite being oversold is a sign of the strength of the bear market in bonds.
Rising expectations for Fed rate hikes are progressively flattening the US yield curve, which if it inverts (shorter term rates above long-term rates) will start to drive renewed talk of recession, even though an inverted yield curve gave a false signal in 2022-24. Rising bond yields present big problems for governments as they mean more revenue has to be devoted to paying interest on past debt. This in turn is likely to drive pressure for spending cuts or if not then even higher budget deficits. Australia is less at risk than most but is not immune.
Australian shares are down 4.5% so far this month, consistent with the historical track record of September being a weak month. Eurozone shares are also down 2.3% but US shares are up slightly. However, the risk of a deeper correction in shares remains high. Along with the back up in bond yields at a time when equity risk premiums are low the worry list for shares remains high and includes: the likelihood of more central bank rate hikes; the ongoing oil supply shock; worries about an AI bubble; and political uncertainty ahead of the US midterms with a Democrat win potentially flagging the risk of US tax hikes.
The extension of the US/China trade truce for another two months into January is good news but the Trump/Xi summit didn’t really resolve the economic and geopolitical tensions between the two countries, including around AI or the Iran War. But at least they are still talking with more summits likely. Investment market implications are minimal. US tariffs on China are currently around 20-25% - comprising tariffs from Trump’s first term and the forced labour tariff of 12.5% - which is below where they were when the truce was first agreed but are still likely to ramp up again with “excess capacity” tariffs probably after the midterms and maybe even more next year if the truce expires.
AI-nnihilation. Talk of AI ranges from super optimism based on a huge boost to productivity to extreme pessimism with worries about a jobs wipeout (even though it seems to be generating more jobs than its destroying so far) to panic over the last few weeks that it will wipe out humanity by the end of the decade. The latter emanated from Anthropic and was then backed by Sam Altman at Open AI and Elon Musk but it looks more like a virtue signalling publicity stunt to support lofty valuations ahead of capital raisings and protect US AI from cheaper Chinese models combined with a bit of nervousness about being locked in an unsustainable AI arms race and a desire to find an off ramp to slow the AI capex boom. There are lots of risks with AI and some guardrails are wise. But the threat of harm applies to all new technologies – whether it be fire, steam engines, electricity, cars, nuclear energy, etc. Humanity has long had a fascination with things that could wipe it out – whether it’s the bomb in films like Fail Safe, nuclear energy in The China Syndrome, Hal the computer in A Space Odyssey, population growth in Paul Ehrlich’s The Population Bomb, global cooling and more recently global warming. AI is just the latest of a long list of things the handwringers can worry about.
In Australia, the RBA (Tuesday) is expected to hike the cash rate by 0.25% for the fourth time this year, taking it to 4.6%, its highest level since October 2011. While unemployment surprised on the upside in August the data was messy, and the RBA will likely still see the jobs market as a “bit tight” and consistent with meeting its full employment objective. But this is not the case for its inflation objective with underlying inflation at 3.6% running well above target and July inflation data along with the latest surge in energy prices, the AI spending boom and extreme weather indicating it will take longer to get back to target than the RBA was forecasting just last month. While cooling economic growth, the rising trend in unemployment and the downturn in home prices should start to take pressure off inflation, after more than five years of inflation being above target threatening RBA credibility it does not have the luxury of continuing to “wait and assess”. Recent commentary from the RBA has been pretty clear in indicating that unemployment needs to rise, that its not too concerned about the fall so far in home prices and that inflation is its top priority right now. Of course, RBA commentary has left a bit of wiggle room but it’s August post meeting statement referred to “increasing the cash rate target further if upside risks [to inflation] materialise” and Governor Bullock told the House Economics Committee a week ago that “some of these upside risks to inflation appear to be materialising”. So, with the upside risks to inflation now materialising it’s likely to tighten in the week ahead as it has suggested it would.
We also expect it to be a hawkish hike with RBA commentary continuing to warn that it may have to raise interest rates further, albeit the move may not be unanimous. But by the time it gets to the November meeting there is likely to be more evidence of a cooling economy, falling home prices, a softer jobs market and rising recession risks so we don’t think a second hike let alone a third will be necessary. So, while a second hike is a high risk it’s not our base case and we should see an extended hold out to around mid-next year at 4.6%. The rising trend in unemployment evident in the August jobs data is consistent with this. The money market has priced in a 90% probability of a hike on Tuesday which we agree with but its expectation for another one or two hikes beyond that looks too hawkish.
- The Australian Government’s latest Intergenerational Report painted a somewhat bleak picture for the next 40 years. The key takeaways are: Treasury sees a further slowing in economic growth to just 2% pa for the next 40 years. This is depressing as 3% pa used to be the norm for Australia. The slowing is mainly due to slower workforce growth as a result of falling fertility and rising old age dependency.
- Lower projections for per capita GDP than in any of the IGRs so far. This means lower material living standards and partly reflects the low starting point – where real per capita GDP today is 13% or $15000 below what was projected for now in the 2002 IGR. But it would be even lower were it not for an optimistic assumption that productivity will grow 1.2% pa over the next 40 years, which is the same its been over the last 40 years. The trouble is that over the last decade its just been 0.2% pa and even if the Productivity Commission’s expectation that AI will boost productivity by 2.3% over 10 years is correct that maybe only gets us to 0.5% pa.
- Ongoing high levels of government spending and a budget deficit forever. The latter partly reflects the capping of tax revenues as a share of GDP at past highs on the realistic assumption that future governments will give back future bracket creep – in contrast to the May Budget that assumed an ever-rising trend in the revenue share to bring the budget back to surplus. But the bigger issue is that the IGR projects a permanently higher share of government spending in the economy due to the cost pressures flowing from an aging population and more spending on defence, NDIS and debt interest.
The good news is that the cap on revenue implies tax cuts ahead, but the problem is that IGR is not really fulfilling its original purpose which was to highlight the fiscal impact of an aging population and support spending cuts or restraint as an offset. More broadly to turn the budget back into a surplus and provide confidence that productivity will be at least as good as the 1.2% pa assumption and so improve the outlook for material living standards the IGR highlights the need for more serious economic reform:
- to get government spending back down to more in line with levels prevailing prior to the pandemic – the IGR estimates that the growth in the non-market or mainly public sector of the economy has cut 0.3% pa off productivity growth since 2017-18;
- substantially reduce the regulatory burden on business – Productivity Chair Danielle Wood’s pointing out that a doubling in company board time spent on compliance issues and the cost of this in becoming too risk averse is an example of the problem here; and
- tax reform to reverse the rising reliance on income tax, boost reliance on the GST & move to a road user charge.
Also in this week's edition...
Testamentary trusts are often considered a vehicle for the wealthy. Estate lawyer Abbey John, explains how even the typical Australian family could save in taxes.
The superannuation debate has been reignited and Kaye Fallick is back to discuss whether the system needs another look.
House prices are slowly sliding, but Michael Collins argues that job losses amid growing economic risk, could turn the correction into a crash.
Susan Bell presents new research from Challenger that reveals the greatest retirement risk in a generation.
Do you qualify as 'rich'? Mark LaMonica attempts to evaluate what financial success really looks like.
The market is always stirring with new narratives. Diana Mousina from AMP shares five risks to watch out for.
Amongst the hard-to-miss headlines about the weakness in global bonds, Christine Benz asks whether some investors are missing the point.
Curated by Simonelle Mody and Leisa Bell
Latest updates
PDF version of Firstlinks Newsletter
Australian ETF Review from Bell Potter
Listed Investment Company (LIC) Indicative NTA Report from Bell Potter
Plus updates and announcements on the Sponsor Noticeboard on our website