Every year, we spend considerable time reviewing our underlying managers, not simply looking at returns, but assessing how they think, where they find opportunity and whether they remain disciplined through changing market conditions.
Following the end of FY26, we asked ten of our underlying managers a simple question: What are you seeing today that the broader market may be missing?
While their portfolios differ significantly, what stood out was how often their answers converged. Across growth managers, value managers, small-cap specialists, quality investors and activist managers, views generally converged around the following:
- valuation matters more than ever;
- opportunities are emerging beyond Australia's largest companies;
- passive investing is creating pricing distortions;
- volatility is creating opportunities for active managers; and
- patient stock selection will become increasingly important through FY27.
This paper brings together those insights and highlights why we believe a diversified portfolio of specialist active managers remains well positioned for the opportunities ahead.
What are managers seeing for FY27
The past financial year was one of the most unusual in recent history. While the S&P/ASX 300 delivered another positive return, the headline index masked an increasingly concentrated market, heightened stock-specific volatility and widening valuation gaps across sectors. Passive investment flows continued to favour Australia's largest companies, while many quality businesses outside the ASX 20 traded at historically attractive valuations.
1. Active management is becoming more valuable
One of the strongest themes from our managers was the growing opportunity for active investors.
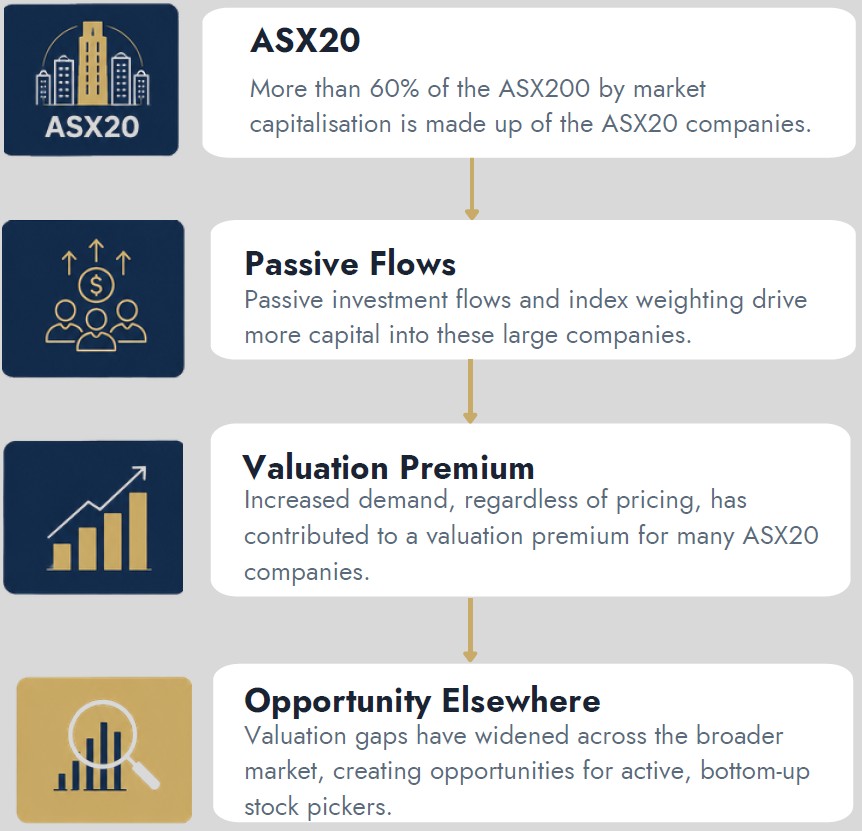
After several years where passive investing dominated fund flows, managers increasingly believe those flows are creating pricing distortions across the Australian market. Rather than reflecting company fundamentals, many share prices are now being driven by index weightings and ETF flows.
As passive capital continues concentrating in Australia's largest companies, active managers see increasing opportunities to identify businesses trading well below intrinsic value.
Our managers are seeing:
- Greater stock dispersion
- More valuation anomalies
- Increasing concentration risk
- Better opportunities outside the benchmark
2. Opportunity exists beyond the ASX20
If there was one message repeated throughout the interviews, it was this: The biggest opportunities are increasingly outside Australia's largest companies.
Several noted that the ASX20 now represents around two-thirds of the ASX200 by market capitalisation, resulting in greater concentration risk for passive investors.
Many believe valuations across the largest companies, particularly the major banks, remain stretched, while quality businesses further down the market offer stronger earnings growth at significantly lower valuations.
3. Valuations matter again
Managers repeatedly observed that FY26 wasn't simply about earnings. It was about valuation.
- Quality healthcare has de-rated despite resilient long-term earnings.
- Software de-rated.
- Banks became increasingly expensive.
- AI winners attracted enormous capital.
Many quality companies traded well below intrinsic value despite continuing to deliver solid earnings.
Table: Where active managers are finding value today
|
Healthcare
|
- Large sell-off despite long-term quality; valuation becoming attractive.
- AI-driven healthcare innovation with significant long-term growth potential.
- Structural demographic growth and attractive long-term outlook
Examples: CSL, Regis Healthcare, Healius, Artrya, 4DMedical, PYC Therapeutics
|
|
Software & Technology
|
- Attractive earnings growth at more reasonable valuations.
- AI and digital infrastructure continue to drive long-term demand.
- Market has become increasingly selective, rewarding profitable growth.
Examples: Life360, Block, Megaport, Technology One, Codan
|
|
Large Caps
|
- Valuations don't fully reflect long-term earnings potential.
- Short-term market concerns have created buying opportunities.
- High-quality businesses with resilient cash flows and global growth exposure.
Examples: The Lottery Corporation, James Hardie, CSL, BHP, BlueScope
|
|
Small & Mid Caps
|
- Benefiting from AI, electrification and infrastructure investment.
- Strong earnings outlook supported by structural growth.
- Less researched than large caps, creating greater alpha opportunities.
Examples: SKS Technologies, Southern Cross Electrical Engineering (Scee), Wagners, Codan, Aurizon
|
|
Growth Companies
|
- Consistent earnings growth with expanding market opportunities.
- Valuation resets have created attractive entry points.
- High-quality management teams with long growth runways.
Examples: Tyro, Life360, Block, Evolution Mining, Megaport
|
4. AI isn't one investment theme
Perhaps the most fascinating observation was that managers are investing in AI very differently. Few are attempting to own AI directly. Instead, they are investing across the broader ecosystem - from the infrastructure powering AI to the businesses benefiting from increased productivity and digital adoption.
- Artificial Intelligence: OpenAI, Anthropic, Microsoft
- Date Centres: NextDC, Megaport
- Power: NexGen
- Copper & Resources: BHP, IGO, PLS Group (Pilbara Minerals), Firefly Metals
- Contractors: SKS Technologies, Mineral Resources, MAAS
- Software: Life360, Block, Technology1
- Healthcare/Medicine AI: EchoiQ, Artrya, 4DMedical
5. Volatility is creating opportunity
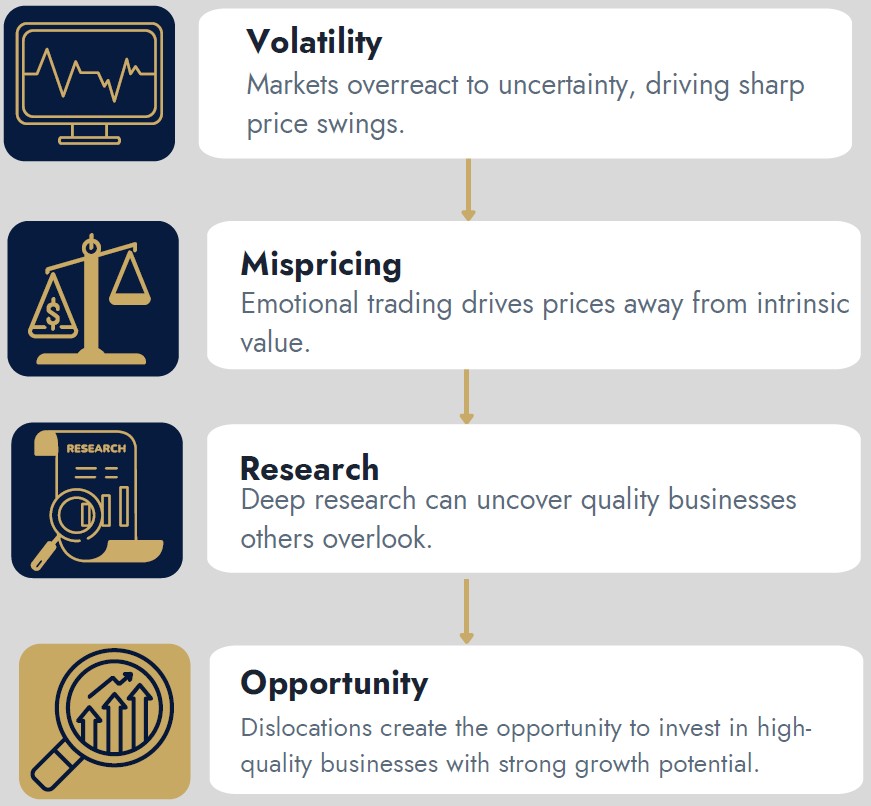
While markets appeared relatively calm at the index level, individual companies experienced enormous swings. Several ASX20 companies suffered one-day share price declines of between 10% and 40%. Rather than fearing volatility, our managers increasingly view it as a source of opportunity.
A common conviction
While each of our underlying managers invests with a different philosophy, their outlook for FY27 was remarkably consistent. Markets remain highly concentrated, passive investing continues to influence pricing, and short-term volatility is creating wider gaps between share prices and underlying business value. Rather than viewing this as a challenge, our managers believe it is creating one of the most attractive environments for active stock picking in recent years.
While markets will continue to be driven by short-term headlines, long-term investment success comes from owning exceptional businesses at sensible valuations. That remains the common conviction across our managers as we head into FY27.
Chris Cuffe is Portfolio Manager of the charitable trust Third Link Growth Fund and of the Australian Philanthropic Services Foundation General Portfolio. Chris is involved with many other groups as a director, chairman and investment professional. This article is general information and does not consider the circumstances of any person. The views expressed are his own and they are not personal financial advice.