Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 342

Who does compulsory superannuation really benefit?

Whether the Government should be increasing the superannuation guarantee (SG) from 9.5% to 12% has become a topic of hot debate. Our research finds that whether a higher SG would benefit most people is far from straightforward for two reasons.

First, the appropriate SG varies greatly across individuals. We think this supports an argument for more flexibility rather than imposing a higher SG on everyone.

Second, the case for increasing the SG depends on what superannuation policy is trying to achieve. A clear case emerges if the aim is to replace the age pension, but not necessarily otherwise.

Super pushes money from pre-retirement to post-retirement

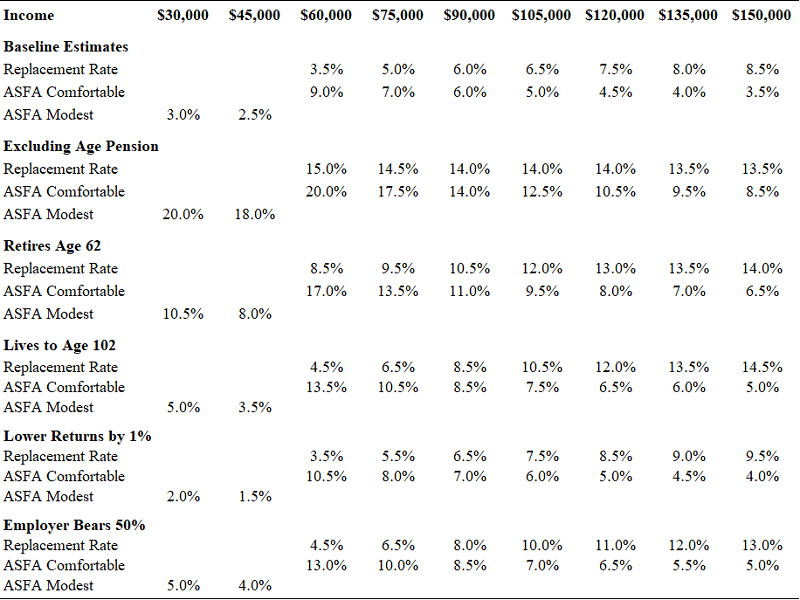
In a recent study (link below), we identify what might determine the ‘right’ level for the SG, and how it varies depending on the individual and assumptions. The analysis is conducted across nine income levels ranging from $30,000 to $150,000 and differing target spending levels. We apply existing rules that govern tax, superannuation and the pension. The table below presents selected estimates for the ‘optimal’ SG, although this is only a subset.

Our model focuses on the trade-off involved in saving via superannuation, which reduces money available pre-retirement but creates a benefit in terms of post-retirement income. Evaluating super as a trade-off is important. Focusing only on ‘how much super is needed’ to generate adequate income in retirement overlooks the possibility that some people might have better uses for the money.

For example, forcing lower income earners or women to place money in super need not make them better off if they are struggling to make ends meet or could use the funds to help buy a house during their working life.

‘Optimal’ SG estimates per income level and objectives
No single SG suits all

The table illustrates the wide range of SG estimates that emerges depending on income and other assumptions – anywhere between about 2% up to 20%. The lower SGs are associated with the ASFA modest income target which is 85%-90% covered by the pension plus supplements. The higher SGs exclude the pension.

Further, there are dimensions we don’t investigate that add to the potential differences across individuals, including household status, gender, assets outside of superannuation and homeownership. In particular, those who own a home obviously need a lot less income during retirement than those who have to pay rent.

The key point is that there is no ‘one-size-fits-all’ SG. Further, there is an asymmetry around the SG itself. Individuals can currently do nothing about an SG that is set too high but can contribute more if it is set too low. We think this adds up to a case for not forcing everyone to save more regardless but rather adding in some flexibility.

The SG might be better positioned as a default rather than a hard compulsion, while enhancing scope to vary contributions subject to limits that guard against people opting out too far.

Two conditions justify a higher SG for all

Our modelling also identifies two conditions under which increasing the SG would benefit the vast majority of Australians. Both relate to what the SG is trying to achieve, suggesting that the Government should settle the policy objectives before deciding whether to increase the SG to 12%.

The first condition would be using superannuation to replace the age pension. This implies getting as many people as possible to become self-funded retirees, with the pension acting purely as a safety net. Excluding the pension from our analysis indicates what savings are required without the pension, in which case an SG of 12% may not even be enough. The alternative is counting the pension as an income stream that is broadly available to all. In this event, the need to save for retirement is much lower because the pension supplies substantial income support, especially for lower income earners. Policy makers might be clear on whether the purpose of superannuation is either to substitute or to supplement the pension.

The second condition would be to ensure that people save enough to support themselves through retirement if things don’t pan out as expected, i.e. using superannuation as a self-insurance mechanism. There are three key risks that may lead to savings turning out to be insufficient:

  1. Living to a very old age so that the money runs out, also known as longevity risk.
  2. Retiring earlier than expected, such that contributions stop before the pension becomes available, thus creating a need to fund spending by running down savings. (Career breaks have similar effects, but there is the chance to catch up on super contributions later, and other income sources may be available such as unemployment benefits or paid maternity leave.)
  3. Low investment returns that impair the funds accumulated. The table reports results where we assume living to age 102, retiring at age 62 and lower returns by -1%.

We are not convinced that imposing a higher SG is the best way of addressing these risks. The problem is that requiring everyone to save more ‘just in case’ can result in over-saving if the feared risks do not eventuate. If the additional savings are not needed, then an individual’s pre-retirement standard of living would have been sacrificed without getting commensurate benefit, along with larger bequests for the children.

Other mechanisms to deal with these risks include social security and risk sharing amongst individuals. The latter are known as ‘pooling’ solutions and include annuities and various forms of member collectives. We would prefer to see policy makers explore these mechanisms.

The ‘who pays’ issue

A higher SG could be beneficial for some individuals if is paid for by employers rather than coming out of their take-home pay via some form of wage offset. However, this issue is far from straightforward. Evidence is mixed on whether the SG has been offset by lower wages in the past. And even if the employer pays in the first instance, where the burden ultimately falls is unclear. Profits taking a hit is one possibility, but others include the cost getting slated back to individuals if businesses increase prices or cut employment.

Conclusion

It makes more sense to add more flexibility to vary contributions rather than increase the SG. Further, the case for an across the board increase in the SG depends on what superannuation policy is trying to achieve. We see a clear argument if the aim is to replace the age pension, but otherwise the value of an increase is debatable.


Geoff Warren is Associate Professor at The Australian National University. This article draws on research undertaken in conjunction with Dr Gaurav Khemka and Yifu Tang. The full paper can be found here.


  •   29 January 2020
  • 7
  •      
  •   
7 Comments
Kym Bailey
January 29, 2020

Terrific article.
Whilst we are looking at SG, is it about time the SGAA 1992 was given a make-over? It is rooted in the industrial age and in many ways has not moved with the times. It is complicated and too often, judicial interpretation is required (contractors v employees is top of the pops). The new addition, SG opt-out, is too complicated and reminds us all that the problem is the base legislation. It's tying hands behind backs.

Peter Bellanto
January 29, 2020

Does the concessional contribution limit increase from $25K when the SG increases from 9% ??

Greg
January 29, 2020

I quote from the article:
The problem is that requiring everyone to save more ‘just in case’ can result in over-saving if the
feared risks do not eventuate. If the additional savings are not needed, then an individual’s
pre-retirement standard of living would have been sacrificed without getting commensurate
benefit, along with larger bequests for the children.

Doesn’t this hit the nail on the head.

We know the life expectancy of our population peers.

We don’t know when any individual will die.

A cautious person will save, targeting a spend time horizon longer than the (average) life expectancy to ensure they are not adversely impacted by Survival Risk – that is, living longer than expected/planned and running out of money.

If we all behave like this then (approximately) half of us will die “too soon” and have over-saved.

The other (approximately) half may have savings to match their actual life.

Bottom line – it makes sense for all of us to save for that “longer” timeframe. On average, sensible retirees with savings capacity will save too much.

Peter
January 29, 2020

I agree with Greg's comments. I am one that saved for that "longer" timeframe only to experience the Government's legislative changes which reduced the SMSF non-taxable pension to a maximum of $1.6m (worth about the same as an Old Age Pension Handout at present interest rates). Self funding incentive reduced!
Superannuation is a bad deal for the lower paid worker who is likely to retire and draw the pension anyway! Locked away savings for such a worker makes his life much more of a struggle. If he could retire with a home mortgage paid off, then the pension might be ok.
Peter

Aussie HIFIRE
January 30, 2020

One of the problems with having variable rates for different people is that system will very quickly become incredibly complex and will be dismissed as too hard to figure out by the majority of the population, particularly with the government and regulators doing their best to drive up the cost of advice so that it isn’t affordable for most people. There are a lot of flaws with a one size fits all solution, but it does make it a lot easier to understand and administer.

Secondly, left to their own devices most people will save no more than they are forced to for retirement. So if we’re going to have a lower amount that people are forced to save, we’re going to end up with more people on the age pension, and will need to pay for that somehow.

Lastly, it seems pretty clear to me that no matter which party is in power over time they will continue to try to reduce the number of people receiving the age pension, and reduce the amount they are receiving. This will mean that people will have to fund their own retirement, and therefore having more money rather than less would be ideal.

So as much as I agree a one size fits all system has a number of problems, it’s better than a more complex system with variable contributions required.

Darryl Davies
February 05, 2020

Really well said Aussie HIFIRE, I agree with all your statements. I am a self made individual coming from a poor background to being rather well off from gaining an education & investing.

People from a poor social background will spend all there money from pay to pay. A gradual informed increase in Super for all is the way to go. Forget the flexibility argument it would be difficult, costly & frustrating to administer.

Tony G
February 02, 2020

I see the SG as a flawed policy that creates distortions and unfair outcomes. It should be dumped in favour of a one-size-fits-all non-means tested, non-assets tested NZ style old-age pension scheme. This arrangement will be very simple with no deeming rules, taper rates, Etc. and will probably not cost more than the tax concessions within the SG scheme that overwhelmingly go to the better off.


Leave a Comment:

RELATED ARTICLES

The elusive 12%: is superannuation at a turning point?

Helping your children build their super

What is the new work test exemption?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.