Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 314

What is the new work test exemption?

From 1 July 2019 new legislation provides an opportunity for recently retired individuals to contribute to super without needing to meet the work test. In this article we will review the work test requirements and the new exemption.

Contributions test varies by age

Individuals under age 65 are eligible to make voluntary contributions to super regardless of their employment status. However, after age 65, individuals must meet the work test. The following table outlines the different types of contributions and the age-related conditions that must be met:
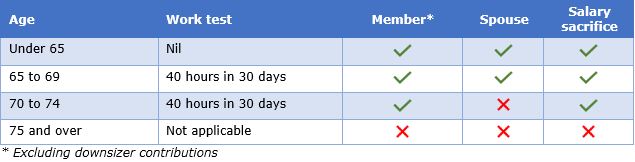
The work test requires individuals to be gainfully employed for 40 hours in a 30 consecutive day period in the financial year in which the contribution is made.

Trustee acceptance of contribution

Super fund trustees cannot accept voluntary contributions from members over age 65 unless they meet the work test. The work test only needs to be met in the financial year in which the contribution is made. Accordingly, it is possible for the work test to be met after the contribution is made. However, some fund trustees require the member to be able to make the work test declaration at the time the contribution is made.

Gainfully employed definition

Gainfully employed is defined in super law as:

Employed or self-employed for gain or reward in any business, trade, profession, vocation, calling, occupation or employment.

The definition requires an expectation of income or profit in return for personal exertion. For an employed person this is generally easy to prove via a PAYG payment summary or income statement. Unfortunately many self-employment ventures do not result in financial gain, but the expectation needs to be there. An activity which is of a personal or hobby nature will not qualify even if there is financial gain.

Volunteering will also generally not qualify as there is no employer/employee relationship.

Work test exemption

The new work test exemption provides a one-time opportunity to make voluntary contributions in the year after retirement if the following contributor meets the following conditions at the time of contribution:

  • Age 65 to 74
  • Total super balance is less than $300,000 at the previous 30 June
  • Met the work test in financial year prior to the year the contribution is made
  • Not used work test exemption previously
  • Contribution made after 1 July 2019

Once the work test exemption has been used for a financial year, it cannot be used again in a later financial year, however multiple contributions can be made within the financial year subject to the contributor’s age at the time of each contribution.

The new work test exemption provides an opportunity for individuals to make non-concessional contributions if they triggered the bring forward rule whilst they were under 65 but were not able to fully utilise the bring forward rule at that time.

Case study

Dawn was 64 on 1 July 2018 and she contributed $140,000 before her 65th birthday on 1 March 2019 when she permanently retired. Under the three year bring forward rules Dawn could contribute $160,000 by 30 June 2021 however she would need to meet the work test in the year she makes the contribution.

If Dawn’s total super balance is under $300,000 at 30 June 2019, she could contribute $160,000 in 2019/20 using the work test exemption.

Concessional contributions, including catch-up of unused concessional contributions cap amounts, could also be used.

Another area where the work test exemption will be valuable is for small business CGT contributions. For many small business owners, selling their business is their retirement plan and they often have small accumulated balances at retirement.

In many instances we see a great deal of effort put into the complex tax side of determining eligibility for the small business CGT concessions however sometimes the eligibility to contribute to super after age 65 is overlooked.

Case study

Arthur and Martha sell their small business at age 68 and 66 in July 2019 and embark on a round-the-world tour for the next 12 months. The proceeds from the sale of the business are received in August 2019 and arrangements made for small business CGT contributions and the appropriate forms to be made to their super fund in September 2019.

Under previous law, Arthur and Martha were not eligible to make the small business CGT contributions to super unless they met the work test in 2019/20.

However, if their total super balances are each under $300,000 at 30 June 2019, they may use the work test exemption to make their small business CGT contributions.

Superannuation guarantee contributions and downsizer contributions are not impacted by the new measure as they are not subject to a work test.


Julie Steed is Senior Technical Services Manager at Australian Executor Trustees. This article is in the nature of general information and does not consider the circumstances of any individual.


  •   10 July 2019
  • 6
  •      
  •   
6 Comments
Ray
July 11, 2019

The last budget the govt announced a change for 65-67 ?? age group. Has this been legislated or is it being ignored

Tom
July 11, 2019

Could Ray,s question be answered ,please?i.e. that there was to be no work test for concessional contributions for those 65-67. from 1-7-19

Julie Steed
July 11, 2019

Hi Ray,
There has not been any legislation passed yet regarding the Federal Budget announcements to increase the work test to those under 67, up from 65. However, the measure was announced to apply from 1 July 2020 so it is still plausible that legislation will be passed before 30 June next year.
Regards
Julie

David Klumpp
August 11, 2019

Can “gainfully employed” be as self-employed, and the work being privately managing one’s own investments (obviously for financial gain)?

Julie Steed
August 11, 2019

Hi David, Gainfully employed can be self-employed however the self-employment needs to be for income from a business, trade, profession, vocation, calling, occupation or employment. Managing the passive receipt of income from one’s own investments will generally not qualify as the individual is not in the business of managing an investment portfolio, rather this is a personal activity. Gain or reward is the receipt of remuneration such as wages, business income, bonuses and commissions, in return for personal exertion from these activities. It does not include the receipt of passive income (no matter how hard one seems to work at it). Regards, Julie

Cynthia
August 11, 2019

What are the time frames for lodging your work test exemption form e.g before you complete your tax return before the end of the financial year?


Leave a Comment:

RELATED ARTICLES

Division 296: the initial moves to make before the windows close

Meg on SMSFs: Ageing and its financial challenges

Meg on SMSFs: Where are the risks in our major super sectors?

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.