Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 207

Why 10/30/60 is no longer the rule

The 10/30/60 rule has become one of the stalwarts of investment advice in superannuation. The rule was developed by Don Ezra with his colleagues at Russell investments, at a time when double-digit equity return expectations were common.

Ezra explains through this rule that, on average, for every dollar of income spent in retirement (from retirement savings), 10 cents came from contributions, 30 cents was from investment earnings in the accumulation phase, and 60 cents was earned in retirement while capital was being drawn down. It’s a stunning idea.

Sadly, today it’s no longer true.

Low returns require higher contributions

In the first version for defined benefit funds in 1989, he noted that 20% of payments typically came from contributions, which could fall to 10% when returns were high. In today’s low rate environment, high investment return assumptions are unrealistic. Ezra himself noted this back in 2011 when he suggested that a ‘15/30/55’ rule would be more appropriate. Without the higher returns, more money needs to be contributed to produce income later in life.

Indeed, in the Australian context, using averages of 6% net returns and 2.5% average inflation since the start of the superannuation guarantee in 1992, the result would be a 15/31/54 split, close to Ezra’s modified rule.

This is a great example of the power of compound interest and it highlights the leverage provided by contributing early and regularly to super. It highlights the benefit of (and need for) high returns in retirement. In practice, it is more to do with ‘money illusion’ and the fact that inflation skews the way we count the money.

For example, let’s assume that the return environment will be broadly similar to the last 25 years, with returns at 6% with inflation at 2.5%, or the 15/31/54 rule. ‘Notional’ is the key word here because the 15 cents to the 25-year-old who makes their first contribution is worth a lot more than the 15 cents they spend as a retired 80-year-old, 55 years later. Treating the two amounts as equivalent is where we fall for the money illusion.

It is simple to model the rule if returns are assumed constant. The rule still ‘works’ when they are not, but only on average. A bad sequence of returns can prematurely end the income, producing something like 15/31/21, and retirees feeling seriously short-changed.

Ezra’s rule depends on the impact of inflation. But what happens when you take inflation out of the equation?

Keeping it real by thirds

In real terms, the rule is starkly different. With a real return of 3.5% (and real salary growth of 1% also in line with historical achievements), the rule becomes 32/33/35, or roughly a third, a third, a third. That’s right - in real terms, each component makes an equal contribution to the end result. Rule 101 of pension finance is to think in terms of today’s dollars or real income in the future. In other words, we should think about our retirement income through the lens of today’s purchasing power. ASIC requires that forecasts of retirement income streams be in today’s dollars in order to take into account the assumed change in the cost of living over the relevant period.

Maintaining the balance

The lop-sided nature of a 10/30/60 rule makes it seem that contributions are not really significant and that if all else has failed, a retiree will be able to make up for everything if they can just get high returns in retirement. While some like to imagine retirees sitting on a beach (or a yacht) while their investments do the hard work, this is probably as close to reality as a Monty Python skit. As the Black Knight in Holy Grail found out, things do not always end well.

In the real world, the final outcome needs a balance. Money needs to be saved (contributed to super) to build a decent savings pot, and investing early in super makes sense due to compounding. Investment returns needs to be generated in both the accumulation and the retirement phases. The difference will be in the way risks are managed. In the accumulation phase, the investor has the time to recover from swings in the market. In retirement, that luxury is diminished and the risk of a bad sequence means that retirees have to balance the need for return against managing the risks.
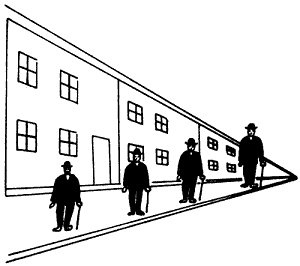

Source: Pinterest (ankeshkothari.com)

Just like the optical illusion replicated here, inflation can skew our perception of the relative size of objects that are equal.

What does all this mean for superannuation funds and retirees? In real terms, with good investment returns, workers can expect to spend $3 in retirement for each dollar they contribute while working.


Aaron Minney is Head of Retirement Income Research at Challenger Limited. This article is for general educational purposes and does not consider the specific needs of any investor.


  •   22 June 2017
  • 8
  •      
  •   
8 Comments
Ashley
June 22, 2017

Retirement – wotz that? – does anybody really retire any more? The ‘retirement’ industry is stuck in the outdated idea of 100% work on Friday to zero work starting the next Monday for the rest of their lives. I’ve never met anybody who does that.

Rob
June 22, 2017

Ashley, I've met lots of people who do, or have done just that, myself included (provided your definition of "zero work" means zero paid work, not voluntary stuff or hobbies).

Peter Vann
June 22, 2017

In any event, if you partially retire from full time work and need to supplement income from paid work with drawings from your investments, super or other investments, then the method of analysis Aaron is discussing is still valid. Instead of using the usual simple starting retirement income profile of a fixed annual amount in real terms, one uses an income profile (again in real terms). In this case it will start with a lower portion and rise of and when one fully retires from paid work.
If fact any practical analysis of retirement expenditure should use income profiles changing through the drawdown phase,

Garry M
June 22, 2017

It strikes me that superannuation policy was introduced in Australia in a high inflation environment and the incentives given to save were in part aimed at encouraging people to spend less on current expenditure.
We have now been in a low inflation era for quite some time and may well remain that way for a bit longer,yet I suspect policy makers are still thinking how to constrain retirement savings portfolios within this inflation mindset(i.e. still in the 10/30/60 era).
Instead of encouraging current consumption and sensible long term saving of a quantum required to meet the 33/33/33 to deal with lower nominal growth and people living longer in retirement,we have a situation of no confidence in spending more on current items(other than punting on real estate) and no capacity or real incentive to invest more in long term savings because of the threat that these will be taxed/constrained further by future governments.

Geoff Warren
June 23, 2017

Great article by Aaron, and a pertinent reminder that care needs to be taken in interpreting output from any model which depends on the set-up and assumptions. The point about real versus nominal investment returns is a substantial one. I want to add some context about the 10/30/60 research from the perspective of a Russell alumnus.
First, this analysis was never meant to be taken literally. It was designed to make one point with some impact: investment returns really matter a lot for retirement outcomes, so don't get too carried away focusing only on contributions. Translating to the current context, this would amount to saying that the question of whether a SGL of 9.5% is sufficient for retirement adequacy may not be as important as the returns that the markets will deliver going froward.
Second, an (overly modest) Don Ezra bucks up when you refer to 10/30/60 as "his" rule. The genesis is a Russell paper dated January 2008 by Matt Smith and Bob Collie. The press release appears at: http://www.prweb.com/releases/investment/russell/prweb974204.htm. Nevertheless, this paper did acknowledge Don for the original concept about the relative importance of investment returns, which arose when writing about defined benefit funds in 1989 (which he put at about 80%).

Justin Ahrens
June 25, 2017

Great article; it highlights that there is no 'set it and forget it' mode, and also that individuals need to pay attention to their investments, need quality advice, and need to educate themselves about this topic - they don't need to be experts, but certainly need to be able to hold their own in the conversation.

John
June 25, 2020

The Australia 10Y Government Bond has a 0.879% yield. 20Y is 1.502%, 30Y is 1.710%. Unless buyers of these bonds are stupid (unlikely) money will remain insanely cheap until death for any current retiree. This suggests the economy is likely to remain depressed for 30 years. Consequently, investment returns are unlikely to average anywhere near historical 6% levels. Time to tell your kids there will be no inheritance.


Leave a Comment:

RELATED ARTICLES

It's not a shock that retirement is different

Understand the retirement income challenge

Where is superannuation research heading?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.