Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 309

Why are Aussie bond yields at lowest ever?

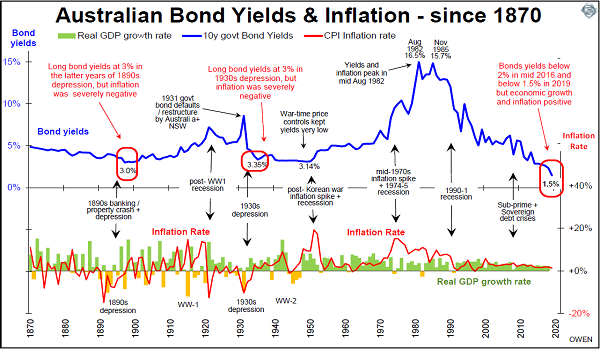
Yields on Australian government bonds have continued falling this year. At the end of May 2019, the 10-year bond dipped below 1.5%, the lowest in history. Yields on 10-year government bonds peaked at an incredible 16.5% in mid-August 1982 and have been declining (along with inflation rates) ever since.

The chart shows bond yields, inflation and economic growth rates in Australia since 1870.

What do low bond yields tell us?

As bond yields represent the market’s collective view on the outlook for economic growth and inflation, the current ultra-low yields are extremely pessimistic. Yields are now lower than in the depths of the 1890s depression and the 1930s depression, when economic growth and inflation rates were deeply negative.

But since economic growth and inflation are positive now, why are yields so low?
Click to enlarge

At first sight, it appears that the current all-time low yields are a sign that ‘the market’ is expecting worse outlooks for growth and inflation than in the 1890s depression and the 1930s depression. However this is misleading. Prior to the 1990s Australia was regarded as a high risk ‘emerging market’ and so yields on bonds were higher to reflect a higher risk of default. Indeed the Commonwealth government defaulted on its entire stock of domestic bonds in 1931 (having taken over responsibility for the State debts, and in particular the defaulting NSW). Australia only regained respectability in international credit markets after the long post-WW2 boom which allowed the debt to be repaid, and after the reforms in the 1980s including dismantling tariff barriers, privatisation, deregulation, and floating the dollar.

Australia’s good standing in credit markets now partially explains the lower overall level of yields in the past few years compared to the prior 100 years.

But yields are too low

Even allowing for this change in status of Australia as a credit-worthy borrower, the current yields are still far too low. Australia may be heading for a local slowdown and possibly recession in the coming year or so, but the current yields are suggesting we should expect virtually zero growth and inflation for the next decade. This is far too pessimistic for a country with the fastest growing population, the most favourable demographics, the lowest government debt levels in the developed world, strong public institutions and a stable government.

The main reason for the low yields is that most Australian government bonds are owned by foreigners scouring the world for yield, and Australia is one of the very few countries left with a ‘AAA’ credit rating. Australian yields may be low relative to our history, but they are still higher than many other countries.

Japanese and German yields are still negative thanks to years of massive central bank ‘quantitative easing’ bond-buying programmes. UK yields are not far above zero, and French and Spanish bonds are below 1%. Australian yields are now even lower than in Canada. Canadian yields are being kept relatively high by the close links to the US, where the economic recovery boosted by the Trump tax cuts has kept US yields above 2% since their post-Brexit lows in 2016.

What does this mean for investors? Although we believe Australian yields will rise in the medium term, we have significant allocations to Australian bonds in portfolios as we had been expecting yields to fall in the short term. The declining yields generated above-average returns of around 6% for 2019 to date (and they beat shares by 8% in 2018). Not bad for boring old bonds in a so-called ‘low return world’.

For borrowers, it will probably mean we heading into a period when fixed rates on loans are the lowest we will see for many decades.


Ashley Owen is Chief Investment Officer at advisory firm Stanford Brown and The Lunar Group. He is also a Director of Third Link Investment Managers, a fund that supports Australian charities. This article is for general information purposes only and does not consider the circumstances of any individual.


  •   5 June 2019
  • 13
  •      
  •   
13 Comments
Dudley
June 05, 2019

"Why are Aussie bond yields at lowest ever? ... most Australian government bonds are owned by foreigners scouring the world for yield":

Why is that so?

Because so many nations owe so much to so many that not repressing interest rates would cause a global default.

Better to pretend as long as possible.

Alexander Austin
June 06, 2019

Can you provide more context on the debt default in 1931. I had never heard that Australia had defaulted.

Warren Bird
June 06, 2019

Hi Alexander,

Ashley wrote a four part series on that a few years ago. Here's part 1: https://cuffelinks.com.au/australias-default-part-1-a-primer/

I believe that the experience generated a strong public commitment that such debt behaviour would never happen again. It was used to establish our current regime of Commonwealth-State financial relationships, with what's now called the Commonwealth Heads of Government framework in place to oversee debt levels and the amount of payments from the Commonwealth to the States. Doesn't mean that there won't be a default in future, but it would in my view come only from an extreme failure of our capacity to repay debt, rather than from the sort of willingness to renege on obligations that existed back then.

In relation to this current article about bond yields, well here we are. After all the hand-wringing a year or so back about how the decline in bond yields was over and we all need to get out of the asset class (not Ashley, I might add - he was relatively bullish on bonds at the start of 2018), we now have them even lower and returns over the past year have been pretty decent.

I don't think that foreign ownership is a sufficient explanation of the low level of yields. I think of it this way - if a 1.5% cash rate for nearly three years wasn't low enough to generate strong economic growth and a pick up in inflation, then there's a structural issue with the risk free rate of return that our economy is capable of generating.

In the pre-GFC world, Australia generated a real risk free rate of return of around 3%. Add inflation of 2-3% onto that and you had a 'neutral' cash rate of around 5.5%. When rates were cut to 5% or less, the economy picked up and inflation increased, and when they were increased to 7% things slowed down again.

Add a term premium of 0.5% pa onto that for 10 year Government bonds and you had bond rates that traded in a range of 5-6%.

Since the GFC we've been grappling to find the 'new neutral'. A cash rate of 3% seemed to be what stimulated when the economy recovered during 2009, but things quickly turned south again during 2011 and we saw cash on a one way trend down to 1.5% by 2016. While that seemed to have steadied the ship, it never generated a strong enough pick up to absorb all the unemployment and other spare capacity in the economy, so inflation has remained low.

So if 1.5% cash is on the tight side of neutral it's no wonder that long bond yields have fallen to 1.5% now.

Ashley makes a valid point in the article about how Australia used to be a high yield market. Indeed, our spread to the US for many years in the 1980's/early 1990's was around 4-5%, similar to 'junk bond' spreads over US Treasuries. When we got off the bucking inflation bronco after the 'recession we had to have' in the early 1990's, that spread narrowed to around 1-2%. It was tighter than that when our economy was softer than the US, and wider when we were going strongly. It's trended down to negative territory over the past year as the US has done OK (partly because of the Trump tax cuts, as Ashley says), while we've struggled.

I hope Ashley is right and bond yields move back up again. It's not an appealing outlook for bonds to pay investors only 1.5% per annum for the next decade, but that's what they're priced to do right now. It's not artificial, and it's not a conspiracy (as Dudley seems to think), it's a reflection of the reality of the structural link between the economy's performance and the level of interest rates.

That's why Aussie bond yields are at their lowest ever in my view.

Dudley
June 07, 2019

"It’s not artificial, and it’s not a conspiracy (as Dudley seems to think), it’s a reflection of the reality of the structural link between the economy’s performance and the level of interest rates.":

I suggest it is the reality of how much interest can be supported by the productive capacity.

Interest = Interest_rate * Debt.

Increasing debt to 'straw that broke camel's back' requires interest rate to decrease if debt is to increase. Increasing debt is seen as a means of increasing consumption to reduce over capacity and result in inflation.

Somehow rent figures similarly.

Paul
June 06, 2019

what are the yellow bars in the chart?

ashley
June 06, 2019

Hi Alex - yes the Commonwealth Government had a full-on 'Greek-style' default - quaintly called a 'restructure' these days. I wrote 4 articles on it in 2014 here on cuffelinks - starting with this one -

https://cuffelinks.com.au/australias-default-part-1-a-primer/

cheers
ashley

ashley owen
June 06, 2019

hi dudley,
Since 1788 Australia has always relied on foreign capital for its development. The post-white settlement Australia we live in now was built by foreign people and foreign capital. Australia has always had more opportunities and demands for capital than its relatively small savings pool, so we rely on foreign capital. No surprises there.

Other countries are different - eg 95% of Japan's debt is owned internally within Japan (mainly by Japanese pension funds). Japan can never repay its debts because it has a declining population, declining tax-payer base and rising welfare costs. But it can solve its debt problem internally (it will mean lower pensions for future pensioners) and is not beholden to foreign creditors.

in contrast, most of the US government debt is owned by foreigners - so it is reliant on his main banker China, which is its main enemy. Different dynamic altogether.
cheers
ashley

ashley owen
June 06, 2019

Hi Paul,
the Green/yellow bars in the bottom section are positive/negative real GDP growth per calendar year. So the yellow bars are economic contractions in those years.
we haven't had any since the recessions of the early 1990s and early 1980s, but they were quite common for most of our history
cheers
ashley

ashley owen
June 07, 2019

hi warren - thanks for your detailed comments and insights.
Yes the carry/spread on USD/AUD had been 3-4% in recent decades but is gone now that cash rates and CPI inflation are higher in the US than they are here.

I believe this is just temporary due to timing mis-match in the cycles - US is recovering from GFC, while Australia is slowing into the housing / construction slowdown + China slowdown. Probably structural inflation and interest rates are still higher here than in the US, and the a positive carry/spread situation will return in time.

Another reason for ultra-low bond yields here (and ultra-low yields on just about every asset in the world) is simply the sheer amount of excess capacity in the world - labour capacity (despite low headline unemployment rates), industrial capacity, bank balance sheets, central bank balance sheets. There is simply too much money in the world chasing the supply of assets, and so yields are low on everything.
All this excess capacity will only be soaked up when global demand picks up. This is going to take a long time time - with the demographics turning sour - ie boomers retiring, aging /dying populations in Japan & Europe, China's urbanisation boom past its peak, robotics/AI replacing human jobs, etc. This is no 1960s/1970s baby boom, or 1980s/1990s boomers borrowing and spending boom. The world is aging and will start dying soon - literally.
The 'Washington consensus' era is over, and we are now at the start of a new era of monetary & fiscal orthodoxy. Exciting times!

ashley

Warren Bird
June 07, 2019

Ashley, yes a lot of excess capacity.

I remember soon after the GFC a lot of commentators were saying that the easing of monetary policy around the world would create a massive lift in inflation. Fund managers set up 'inflation protection funds' to capitalise on this fear/concern/forecast. My view was that this wouldn't happen because the world was going to take a long time - at least a decade - to repair, including demand growing enough to soak up the excess capacity that existed. The fact that demand has been slow to recover only means that more capacity has built up.

You make an interesting point about the ageing population and what means for that excess. Of course, there are still a lot of people in countries like India and China, not to mention Africa if that continent ever got its act together, to replace us oldies in the West when we pass on. Don't know that I'd rely on that to take this problem away.

Agree that the current 'negative spread' between Australia and the US is cyclical. The more normal level should be around 1-2% rather than the old 'high yield' days of 4-5%.

Dane Allen
June 09, 2019

Hi Ashley, very informative. Your theory around ultra-low bond yields dovetails in nicely with Larry Summers' well-documented theory of secular stagnation.

The Lege
August 12, 2019

Hi Dane
Secular stagnation does not exist. It is an academic invention to provide cover for failed economic policies that have ultimately led to suffocating indebtedness. Once your citizens are spending most of their money servicing debt to pay for consumables you get stagnation — you have brought the future forward meaning the future is now a spending black hole.

Secular stagnation is not a mysterious phenomenon – and it actually has a cure: debt deflation. Highly painful, but very rapid. You can be sure no country will opt for this voluntarily. But it will come.

Baz
July 05, 2019

Here's VGB over the last year 9.90% total return


Leave a Comment:

RELATED ARTICLES

Are debt and its servicing cost serious worries?

Why have bond fund distributions been shrinking?

Why 'Don't fight the Fed' now has a different meaning

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.