The tax efficiency of some managed funds and exchange traded funds (ETFs) is often an underappreciated and less visible benefit for investors. In Australia, fund manager performance is most often assessed on pre-tax returns. A low portfolio turnover can potentially provide significantly better after-tax returns relative to that of a high turnover actively managed fund, assuming all other factors are equal. For broad Australian equities exposure, we provide an illustration of how a low turnover structure can potentially improve after-tax returns up to 1% p.a. Furthermore, the ETF structure typically better insulates investors from having to pay capital gains tax if there is a high level of redemptions from other investors, when compared to traditional managed funds.
Why low turnover lowers tax
One of the features of index-linked strategies is that they usually don’t require a high turnover of stocks from year to year, typically only around 10% a year while an Australian actively managed equity fund can be as high as 80%. The lower the portfolio turnover of a managed investment, the fewer assets will be sold each year and therefore the lower the potential annual capital gains tax (CGT). Low turnover means the tax payable on any accruing capital gains in a portfolio will largely be deferred until the gains are realised at a later date – typically when investors sell their investment – which, in turn, means an investor’s portfolio value can remain higher for longer. Investors receive more benefit from return compounding over time.
Low portfolio turnover also means that a greater portion of the assets are likely to have been held for more than a year, giving investors the benefit of CGT discounts applicable on long-term asset holdings. In Australia, individual investors apply a 50% discount to CGT when selling assets held for longer than one year, while superannuation funds (including SMSFs) apply a 33% discount.
We can demonstrate these tax effects using a simple numeric example. Assume that an investor places $100,000 in a managed investment that delivers pre-tax capital growth of 6% per annum, and sells the fund after two years (ignoring management fees and costs and distributions). The table below considers three cases: 1) no turnover in the fund over the whole period 2) a 10% turnover in the portfolio at the end of year one, and 3) an 80% turnover of the portfolio at the end of year one. Increasing portfolio turnover from 10% to 80% - assuming pre-tax returns are the same – significantly reduces post-tax returns. Indeed, for an investor in the top marginal income tax rate of 47%, the post-tax annualised returns are reduced from 4.5% to 3.5%. For superannuation funds (including SMSFs), the post-tax annualised return is reduced by 0.5%.
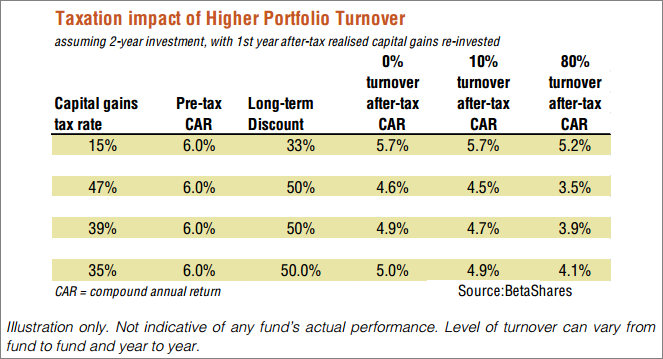
(Calculation details: If there is no turnover in the fund, the fund earns a compound 6% pre-tax return each year, growing to $112,360 on the date of sale. That means the investor is liable to pay tax on capital gains of $12,360. Assuming they are in the top marginal tax rate of 47%, and receive the 50% CGT discount, their tax payable is $2,905, reducing the after-tax value of their investment to $109,455, for an annualised two-year after-tax return of 4.6%. For a superannuation fund receiving a 33% discount on their 15% tax rate, the annualised two-year return is 5.7%. With 80% portfolio turnover at the end of the first year, however, the investor is liable to pay CGT (without any discount) on the 80% value of shares sold at the end of year one, reducing the value of the portfolio heading into year 2 even if all after-tax returns are re-invested. What’s more, when the whole investment is then sold at the end of year 2, around 80% of the gains relate to newly purchased assets held for less than one year, and so are again not subject to a CGT discount. Only the 20% of the portfolio held for two years is eligible for the discount. The end result is that the annualised after-tax return for an investor in the top income tax bracket falls to 3.5%. For superannuation funds, the return falls to 5.2%. With portfolio turnover of only 10% at the end of year one, however, the return for an investor in the top income tax bracket is 4.5%, or only 0.2% less than the ‘buy and hold’ case of zero turnover. For super funds, the return remains close to the 5.7% return for the zero turnover funds (the tax penalty associated with turnover is lower for super funds due to their lower marginal tax rate). The after-tax return is higher than in the case of 80% turnover because less CGT needs to be paid at the end of year one – allowing more of the portfolio to earn extra returns in year two – and because more of the CGT payable at the end of year two is subject to the CGT discount).
Dealing with investor redemptions
Another tax efficiency associated with ETFs is that their unique structure means investors are typically better insulated from having to pay capital gains tax if there is a high level of redemptions from other investors. In the usual managed fund structure, large investor redemptions mean the fund manager has to sell underlying assets to meet the cash demands of departing investors. In most cases – and especially where there are many small investors selling at the same time – it is administratively complex for the fund manager to assign (or ‘stream’) the capital gains tax associated with these sales to the individual investors in question. Instead, the fund is left with the capital gains tax liability which in turn is passed on to remaining investors in the fund at the end of the financial year.
With an ETF however, even if many small investors seek to sell their ETF holdings on the ASX at the same time, it is the authorised participant (AP) who facilitates these sales (effectively buying ETF units from individual investors in return for cash), and who then undertakes the redemption process with the ETF provider. Due to the fewer but larger redemptions involved, it is easier for the ETF provider to ‘stream’ the associated capital gains tax payable to the AP, sparing remaining investors in the ETF from having to pay this tax.
Tax efficiencies are an important benefit associated with ETFs and other low turnover structures that investors should keep in mind.
David Bassanese is Chief Economist at BetaShares, a leading provider of ETFs. This article is for general information purposes only and neither Cuffelinks nor BetaShares are tax advisers. Readers should obtain professional, independent tax advice before making any investment decision.