Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 543

China is primed for a comeback

Our investment philosophy is to buy champion businesses of the future when valuations are depressed. Typically, reasons for the negativity are obvious. Our job as long-term investors is to look past short-term disruptions, and determine if the businesses possess strong economic moat which enable them to become champion companies in the future.

From this perspective, Chinese equities are exciting for us. After a three-year bear market, Chinese equites are well-and-truly out of favour. While the Chinese economy is facing multiple headwinds, quality businesses will continue to grow and become champion businesses in coming years. Right now is an opportunity to invest and take advantage of the attractive valuations.

The challenges

The economic headwinds for China are well-understood. The economy is reducing its reliance on the property sector for growth. It also has to cope with heightened geopolitical pressure and has spent the last few years purposefully reforming the economy.

All these negative factors are reversing to a certain extent for the better. However, it will take time for these measures to take hold and for the various sectors of the economy to heal. We believe that a muddling-through outlook is unfolding, with a generally stable and improving growth environment.

In the meantime, we are focussed on strong businesses with solid positions within the country that are still enjoying long term growth. Businesses like Tencent, Tencent Music or Kuaishou, all of which have an abundance of levers to pull by virtue of their dominance in the internet to maintain decent growth rates even in a slower economy.

Let’s go through a few of the issues that has worried investors.

1. The property sector

The much talked about property downturn is in fact quite advanced. Sales volumes of new residential properties are down 35-40% from peak sales a few years ago. With loosening of property policies, sales volumes are stabilising. Going forward, given the current backdrop, further decline in volumes is going to have smaller incremental impact on economic activities. According to Morgan Stanley Research, given the significant decline in activities, property investment in China as a percentage of GDP is already lower than that of Korea, Germany and Japan.
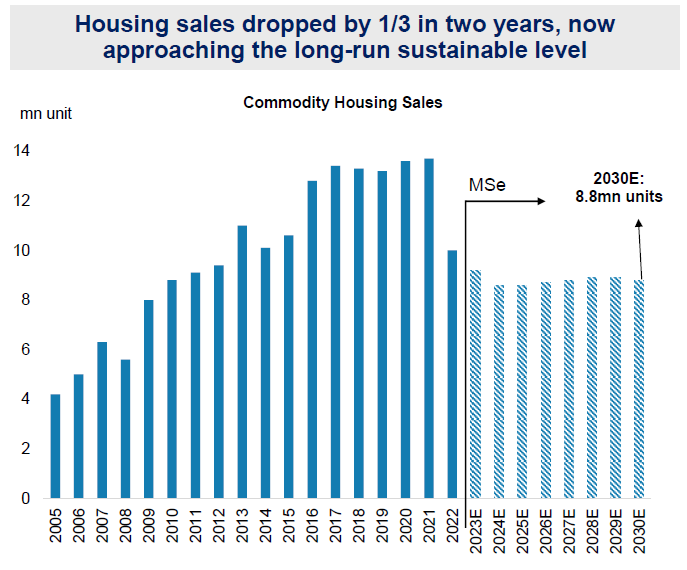

Source: NBS, Morgan Stanley Estimates
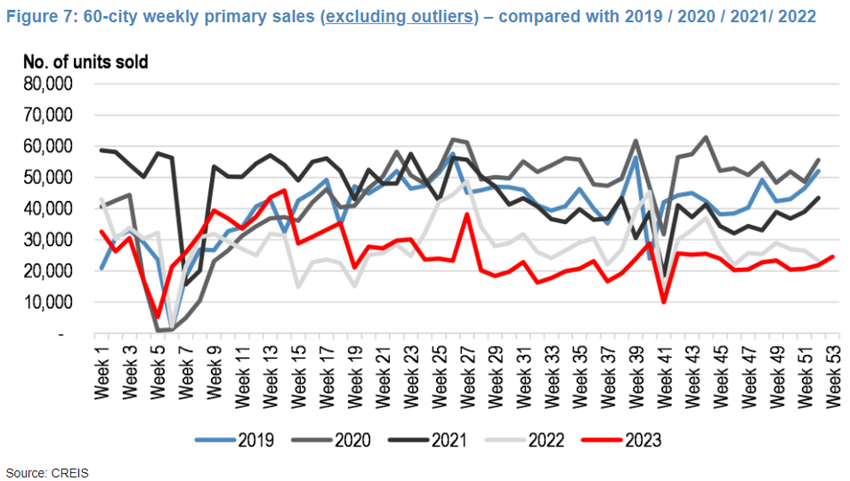

Source: NBS, Morgan Stanley estimates.

2. Hidden local Government debt

Another risk to the economy is the 'hidden debt' of the local Governments (also known as local government funding vehicles). Estimates have it totalling US$7 trillion (around 50% of China’s economy). While not a small sum, it is manageable, and the magnitude is well-understood by investors and regulators. The regulators are pursuing a combination of austerity, debt restructuring, assumption of debt by the central government and potentially money printing to tackle the problem. These initiatives should gradually work down the problem over time.

3. Government crackdowns on certain private sectors

Well-known examples of crackdown were on the after-school tuition sector and the internet sector. Firm rules were implemented to curb some of the activities that were deemed dysfunctional by the authorities.

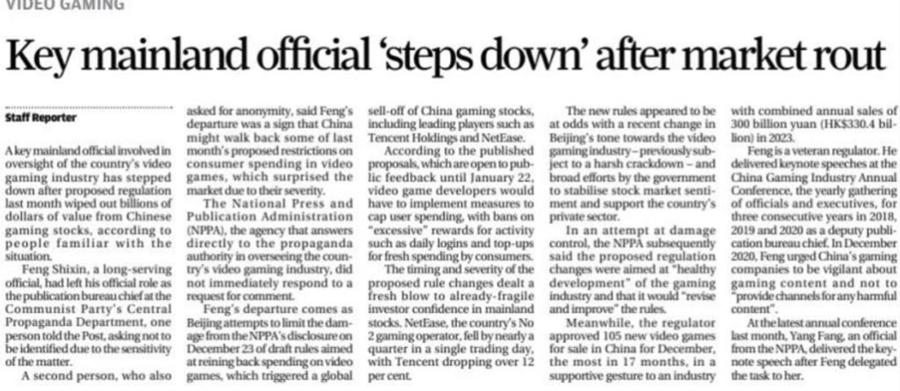
The vibrant private sector has to shoulder the burden of economic growth under guardrails, and the Central Government has little appetite to introduce more tightening measures. The most recent episode involved a Government department official having to step down after releasing a consultation paper on additional tightening measures for the video gaming industry.


Source: SCMP

4. Money printing?

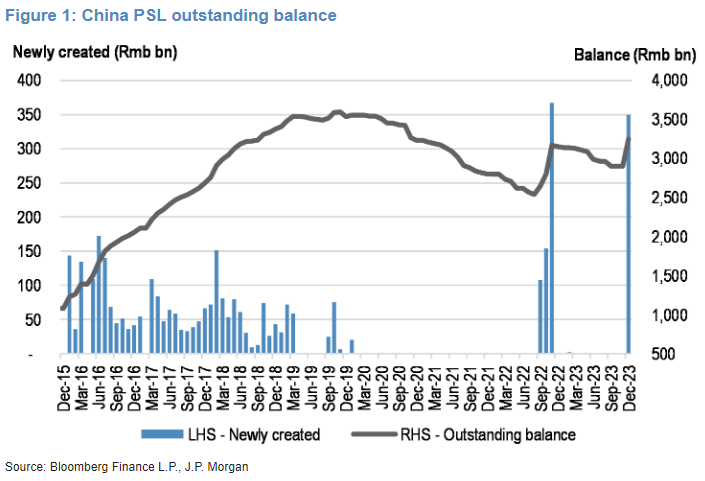
China’s version of “money printing” is called pledged supplementary lending (PSL). If the magnitude is eventually bigger than investors’ expectations, this will be a meaningful impetus for economic growth and cleaning up of the banking system.

5. Geopolitical Tension

Geopolitics tension is thawing. The meeting between President Biden and Xi shows the intention from both sides to restore bilateral relations and reducing near-term risk of escalatory confrontation. With the economy a top priority, China is adopting a pragmatic approach to dealing with geopolitical questions.

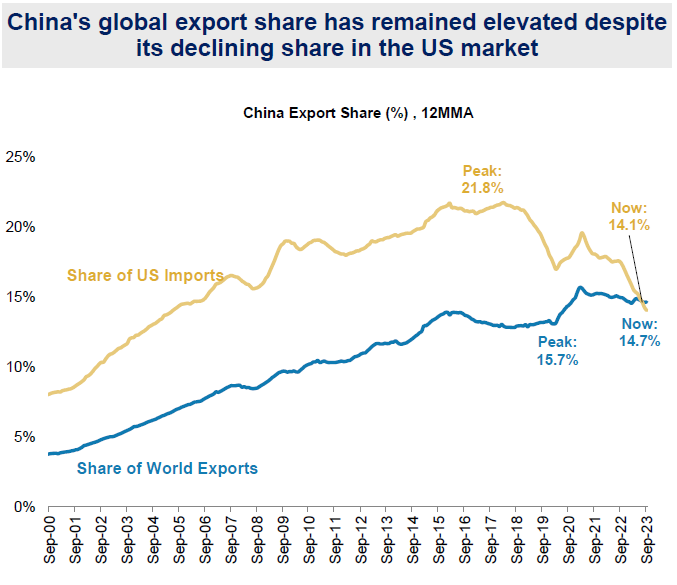
It is likely that continued technological competition will remain. Nevertheless, its manufacturing base remains second-to-none and cost-competitive, China will remain a key part of the global supply chain. New industries such as electric vehicles, renewable energy and automobile have become new drivers for export. China is diversifying exports towards the BRICS countries of the global south and remains the biggest exporter in the world.


Source: NBS, Morgan Stanley Estimates
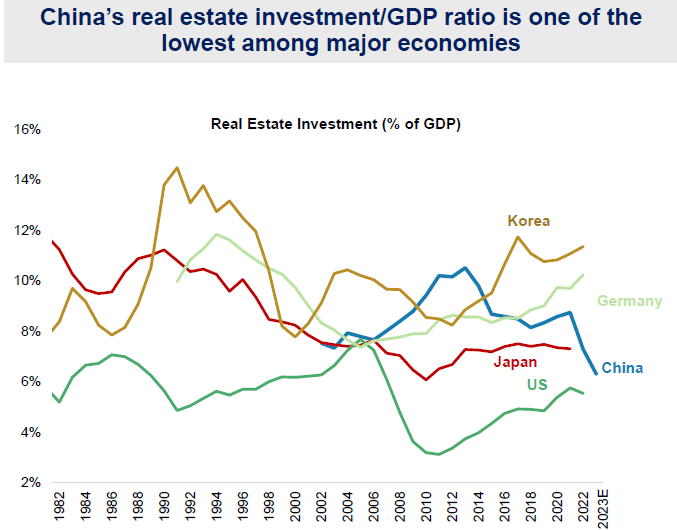

Source: NBS, Morgan Stanley Estimates
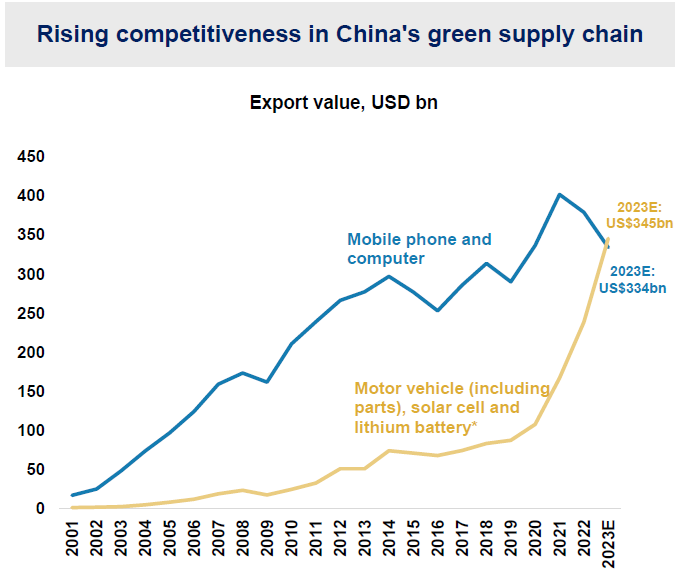
Negatives seem priced in

The problems facing the Chinese economy are manageable. The bright spots are the huge domestic market that continues to grow. Indeed, real income for the consumers is growing, but with the weakness of consumer confidence, excess savings have built up. Improvement in confidence can quickly re-ignite consumer spending. Valuations have come down and are cheap on a historical and global basis. 
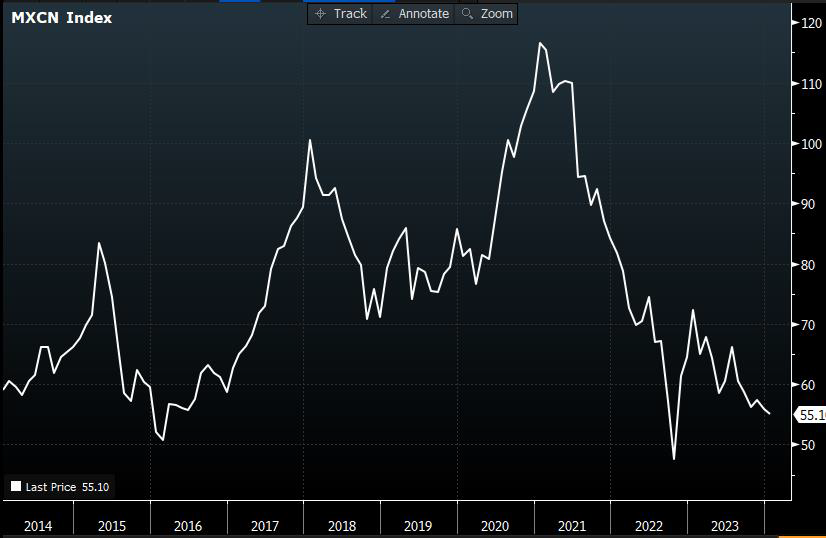

Source: Bloomberg


Dr Joseph Lai is Founder and Chief Investment Officer of Ox Capital Management (ABN 60 648 887 914, AFSL 533828).  This document does not relate to any financial or investment product or service and does not constitute or form part of any offer to sell, or any solicitation of any offer to subscribe for interests, and the information provided is intended to be general in nature only. It has been prepared without taking into account any person’s objectives, financial situation or needs.


  •   17 January 2024
  • 6
  •      
  •   
6 Comments
CC
January 18, 2024

It's impossible to know if Chinese companies are great or cheap when the CCP refuses to allow transparency in accounting and auditing, supposedly because of national security.

Peter
January 19, 2024

With China's autocratic government seeking strong control of the economy, anti-western sentiments, threatening war over Taiwan/South China Sea and accused of lacking transiency about it's economy, you would have to be a fool or very brave to invest there in my humble opinion..

Allan
January 19, 2024

Which country wistful of wonted worth doesn't seek strong control of its economy, Peter? Regarding 'lack of transparency', it may have benefitted Philip Lowe, and myriad others besides, had Philip not been so forthcoming with his: 'No interest rate rises until 2024'.

Peter
January 20, 2024

Don't invest in autocratic communist countries. Their values are different to the western democracies .One should consider what happened to foreign investments when Russia invaded Ukraine. Assets have been frozen, dividends not paid and investors/companies have incurred significant losses off capital. China is threatening to take Taiwan by force if necessary and this could happen soon. I would imagine a similar scenario for investors in China when that occurs. I think some investors significantly underestimate the dangers of investing autocratic communist countries.

Graeme
January 21, 2024

All replies I agree with, totally valid.

Kurt
January 22, 2024

G'day Peter, China could hardly be defined as a communist economy in my eyes.


Leave a Comment:

RELATED ARTICLES

How to find big winners in the energy transition

Which country will be the next China?

China’s new model is a plan for a hostile world

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.