Adyen is a Netherlands-based company founded in 2006 that offers an ecommerce platform that seeks to smooth payments and provide shopper-data insights for businesses. In 2017, Adyen, which employs fewer than 700 people in 15 offices around the world, processed more than €100 billion for the first time.
Commerzbank is a German bank founded 148 years ago that has about 1,000 branches that serve more than 18 million private and business clients. In 2017, Commerzbank’s 50,000 employees generated €9.1 billion in revenue, making it one of Germany’s biggest banks.
On 24 June 2018, the day after Adyen listed, the two companies had about the same market value. By 1 November, Adyen was worth 60% more than Commerzbank.
This example shows how investors assess the threat to traditional banking from ‘fintech’, loosely defined as any technological innovation tied to the internet that competes against the services offered by old-style banks. Fintechs are shaking up all areas of banking by offering internet banking, ‘crowdfunding’, running price-comparison websites, hosting peer-to-peer lending and extending ‘point-of-sale’ loans. Their app banking aims at the heart of savings banks, the transaction accounts. In time they could challenge the viability of the branch networks that provide savings banks with their core advantage, a large source of cheap funding and clients for life.
Big winners and big losers
Most fintechs are startups and few will be as successful as PayPal. Their lack of distribution networks leaves them more nibbling away at niche banking areas, often ones regarded as too risky by banks. The most likely fintechs to challenge savings banks are the tech giants, as shown below for Amazon. They come to the industry with distribution networks, much capital, hordes of big data on their customers and are IT savvy.
All the ways Amazon is unbundling the bank
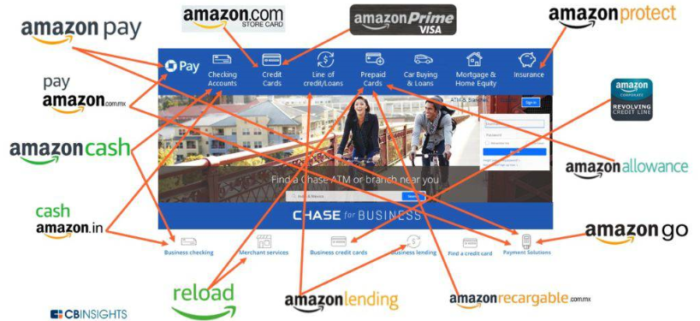
Click to enlarge. Source: CBI Insights. 2018
Whichever sort, fintechs hold advantages over savings banks, which are losing some of their edge in the age of the world wide web. The internet works against banks because it reduces the convenience advantage offered by their branch and ATM networks. It allows for easy interest-rate comparison, which promotes newcomers undercutting banks. The internet makes it simple to switch banks. Fintechs coming out to fight against banks are generally free of, or less burdened by, the systemic-based capital requirements and compliance controls that smother savings banks. They are risk-takers free of the hodgepodge systems hampering risk-averse banks. Mobile payments present them with an easy entry into finance. Their reputations are cleaner. Regulators are encouraging their rise to boost competition.
Fintechs, especially if big tech gets serious about finance, are likely to peck away over time at the oligopolistic industry structures protecting savings banks (without encroaching on the systemic role banks play in the financial system) because they have two key advantages. The first, stemming from their lower costs and the qualities of the internet, is that they can offer higher returns and lower lending rates than can savings banks. The other advantage is fintechs can easily target the fee (or off-balance-sheet) side of banking, which offers returns on equity of about 20% and where about 65% of banking profits are sourced.
The risk is that the traditional global banking industry might struggle to earn a return on equity that exceeds its cost of capital, usually taken as somewhere between 8% and 10%. The best ones will stay profitable, the average ones are likely to just earn their cost of capital. Regulators need to be on guard that some could fail.
Incumbents need to adapt, including regulators
To be sure, fintech market share is still small, much fintech growth is incremental rather than breathtaking, and many complement rather than disrupt banks. Some fintechs are floundering and most are yet to be tested by recessions. Governments everywhere will protect traditional banks in some form because they are vital to the financial system. Traditional banks are cutting costs and have the resources to reinvent themselves as tech-savvy – and possibly much better – banks or financial services. Banks have enough capital to buy, and co-opt, threatening fintechs. While people might resent traditional banks, they are ‘brands that have held their trust over time. Banks have a proven ability to assess credit risk, the core survival skill banks require. Banking virtues – prudent lending, sound risk management, integrity, etc. – will likely hold sway over technology in the long run.
And yet Big Fintechs, and startups to a lesser degree, are capable over time of snapping the traditional and profitable lifelong bank-customer relationship. They intend to go after the juiciest fee-income parts of traditional banking. They will lower margins on the balance-sheet-based lending that is the lifeblood of the economy. Traditional banks will have to adjust to this new competition. Being more like fintechs (perhaps, by partnering with them) is probably the best way for savings banks to do that.
Michael Collins is an Investment Specialist at Magellan Asset Management, a sponsor of Cuffelinks. This article is for general information purposes only, not investment advice. For the full version of this article go to: https://www.magellangroup.com.au/insights/fintechs-could-challenge-the-business-model-of-savings-banks/
For more articles and papers from Magellan, please click here.