Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 154

In investing, patience is more than a virtue

When was the last time you saw a headline that said something like, “Everything is fine. There is no need to change your portfolio”? This headline wouldn’t generate many site visits.

So, in our pay-per-click world, these articles aren’t published. Instead, depending upon when you opened the paper during the last year, either the next recession was imminent and cash was the only safe investment, or everything was fantastic and anything less than 100% shares was an underweight. In short, investors have been conditioned to expect extreme views. These opinions are not necessarily wrong, but they are perhaps a little inflammatory. Often, ‘doing something’ following a bout of market volatility can be a good way to reduce wealth. As has been attributed to Warren Buffett, “The stock market has a very efficient way of transferring wealth from the impatient to the patient.”

Let’s take a deep breath and ask whether the ‘turmoil’ of the last year has been out of the ordinary.

Is the recent experience normal?

Consider the daily returns for the Australian share market based on the All Ords Accumulation Index. As shown in Chart 1, starting with the current rolling 12-month return to early April 2016 (-9.8%, the orange bar), since 1980 the Australian share market has delivered annual returns between approximately -50% (November 2008, the most precipitous part of the GFC) and +100% (September 1987, the month prior to The Crash of ‘87). History shows that rolling 12-month returns have been worse than the last year just over 11% of the time since 1980. The recent past hasn’t been a great time for investors, but neither is it particularly rare.

Chart 1: Rolling 12-month returns since 1980 for All Ordinaries Accumulation Index
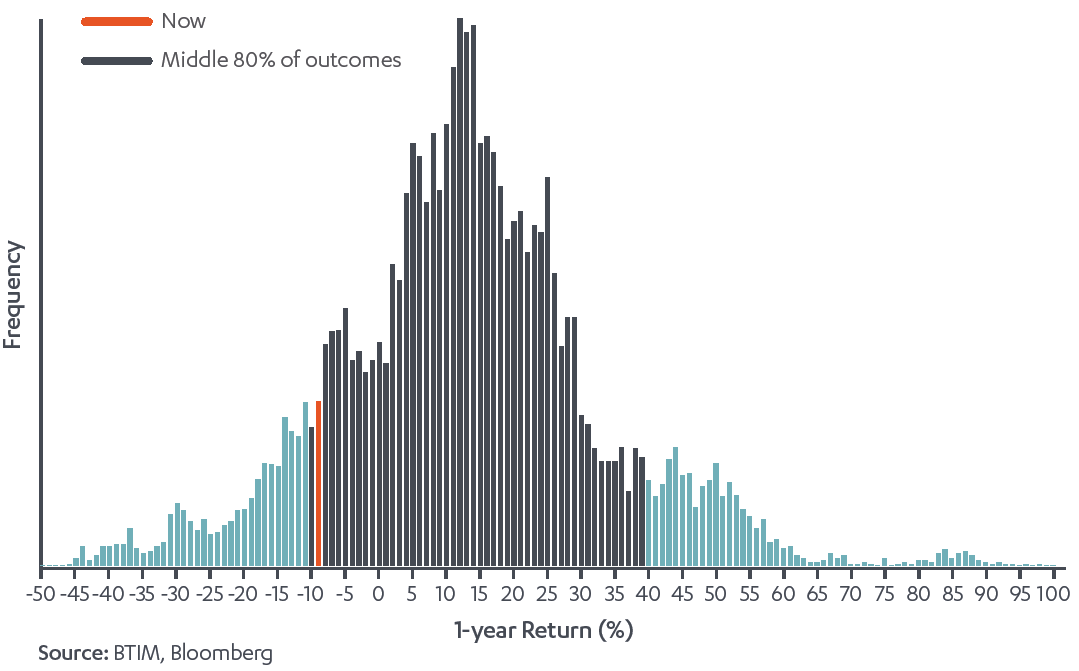

Note: Frequency numbers sum to 100%

Now let’s look at risk: the ‘risk’ (which we define as standard deviation of returns, or volatility) in the past year to early April 2016 was 17.5% p.a. Since 1980 the range has been between 6% and 36% and, similar to the return chart above, about 12% of observations have been worse than experienced in the past year. Again, this is towards the poor end of ‘normal’ outcomes, but not particularly unusual. Chart 2 suggests volatility occurs in two states: less than 20% (the typical situation) or more than 20% (the extreme situation), which can be seen from the relatively high frequency of high volatility outcomes on the right side of the chart.

Chart 2: Annualised standard deviation of returns since 1980 for All Ordinaries Accumulation Index
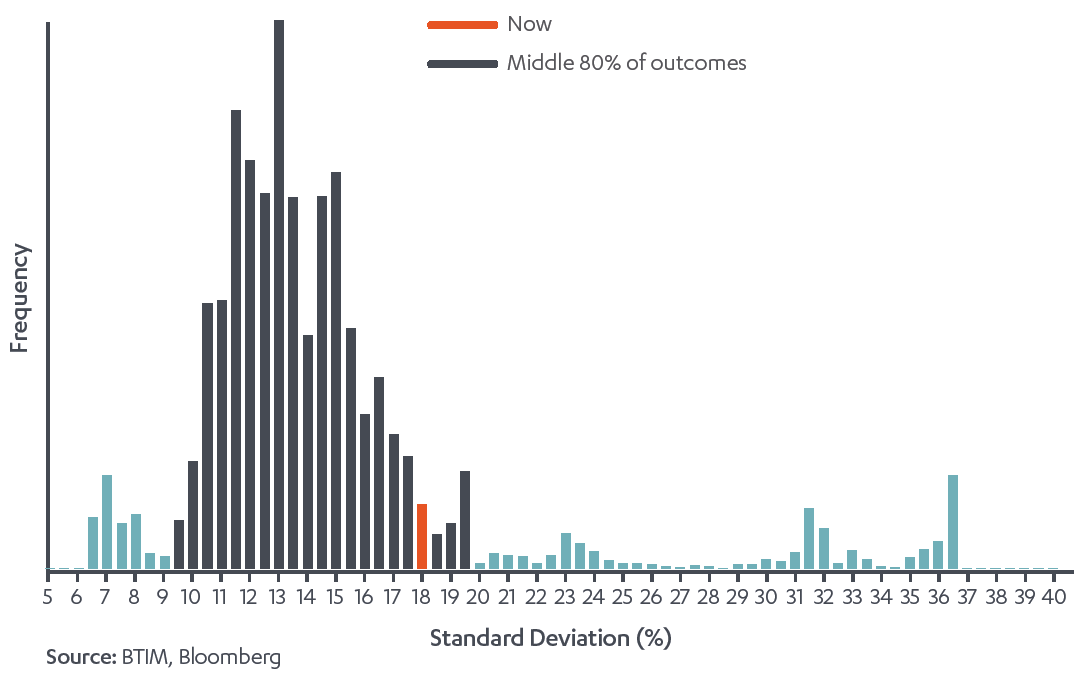

Frequency numbers sum to 100%

Can volatility predict return?

We can look at the relationship between historical volatility and future returns to determine whether we can use volatility to predict market direction. This table is a comparison of the realised volatility of any single year and the return in the following year (calculated for every day rather than at the end of the month or year).
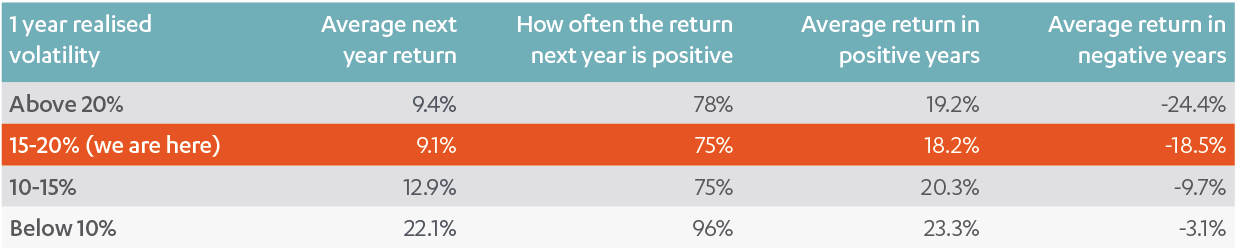
On this analysis, volatility has no reliable predictive power for future returns, but some general tendencies can be seen:

  • Regardless of the level of volatility (column 1), future returns were positive at least 75% of the time (column 3)
  • Positive years were best (column 4) when preceded by lower volatility
  • Negative years were worst (column 5) when preceded by higher volatility.

This tendency suggests more caution when recent volatility has been higher, but hardly screams that it’s time to throw in the towel. When realised volatility has been between 15% and 20%, returns in the following year still tend to be positive three times as often as they are negative. Pretty good odds! The point is that we just can’t reliably use risk to predict return.

But what about the very long term?

We will now switch to a much longer data series, nearly 150 years of S&P 500 Index returns courtesy of Professor Robert Shiller’s website. This data, in Chart 3, encompasses a huge range of economic environments. Looking at returns shows investing in shares can be a roller coaster ride. The range of rolling 12-month returns is between -67% and +165%, with 80% of these observations falling between -12% and +34%. Interestingly, the so-called Tech Bubble of the late 1990s doesn’t stand out as anything out of the ordinary when seen in such a long history.

Chart 3: S&P 500 Index rolling 12-month total returns since 1871
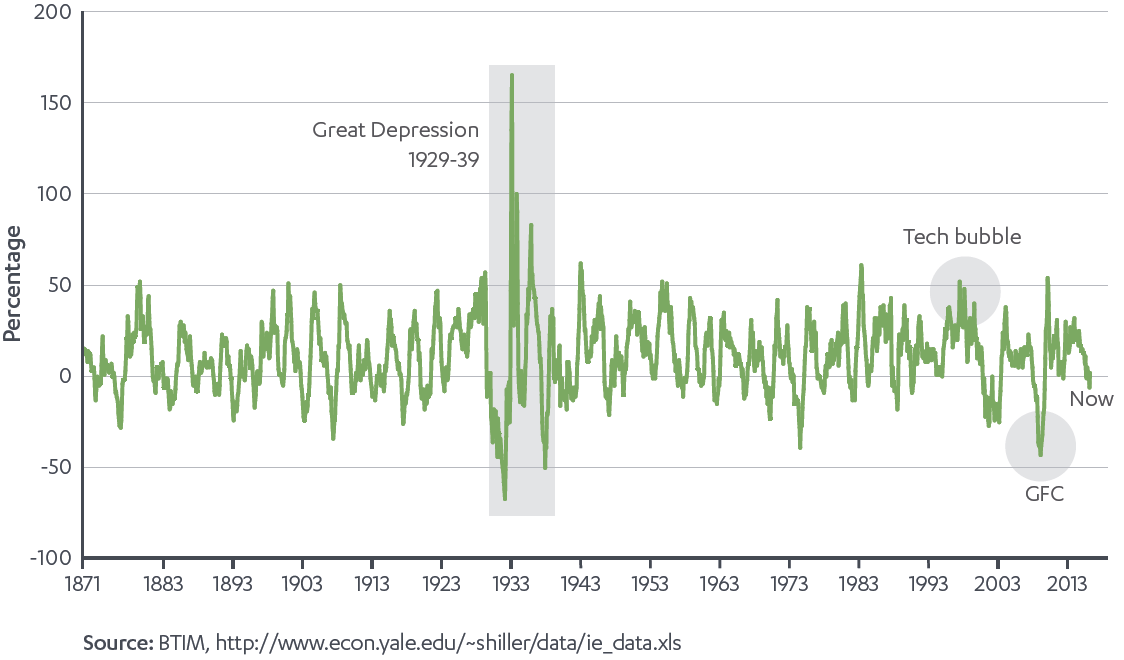
Now look at the 3, 5, 10 and 20-year rolling returns in Chart 4. It’s clear that the longer the investment horizon, the more predictable the outcome and therefore the greater the surety of achieving wealth creation objectives.

Chart 4: S&P 500 Index total returns since 1871 for different rolling periods
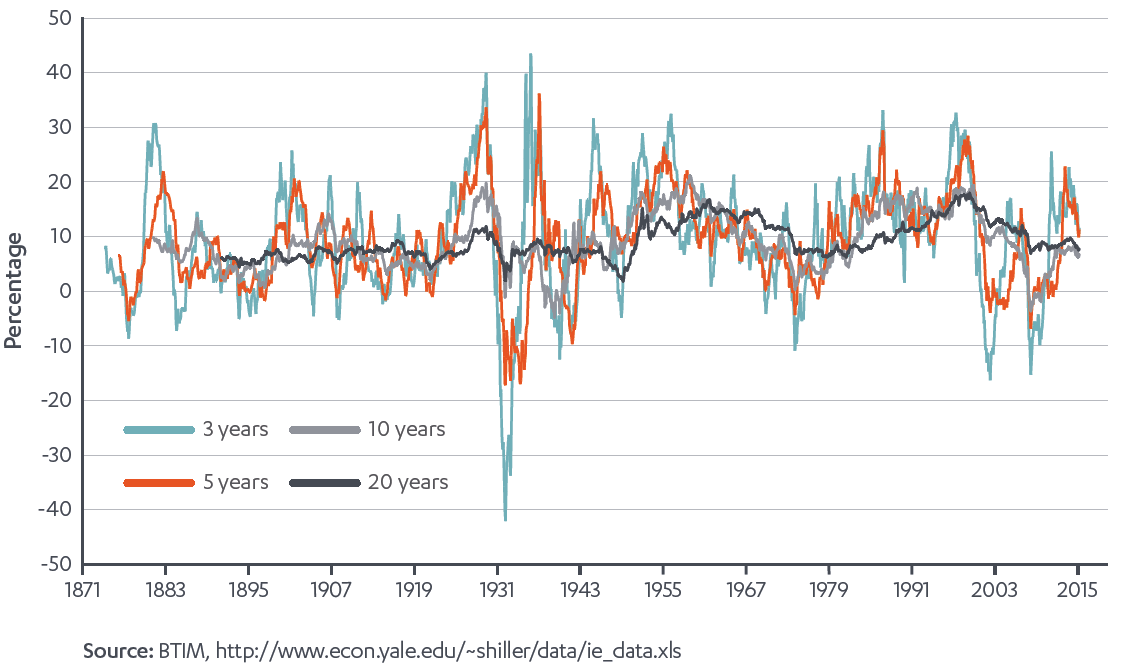
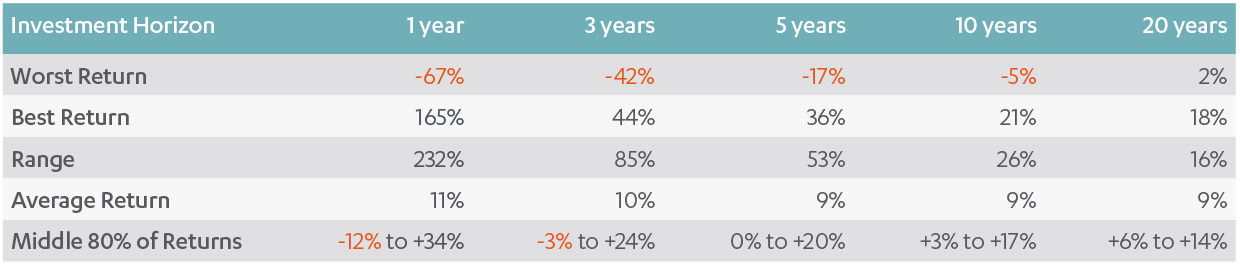
Three-year returns still have a wide range of outcomes but are materially better than 1-year, and 5-year returns are starting to become a little more palatable. By ‘better’, we mean more consistent. Aside from the Great Depression, the occasions where the S&P 500 Index delivered a negative 5-year return were few and brief. By the time we get out to a 20-year holding period, the S&P 500 Index has never had a negative total return. While this sounds like a really long time, it’s actually the investment horizon of an investor in their mid-forties.

Essentially, in the above two S&P 500 Index charts, the green line of 1-year returns is what you experience but the black line is what you could get. The key here is that asset classes need to be given long enough to let the short-term noise wash out and for the long-term risk premium to pay off. The longer an investor can stick to the plan, the better. What’s more, it’s easy to do!

Rules by which to invest

While it’s tempting within a diversified portfolio to sell down equities ‘if they look toppy’ or buy ‘if they are cheap’, that’s speculation, not investing. It’s our firm belief that the strategic asset allocation needs to be set with reference to, and maintained for, a period consistent with the investment horizon of the investor. Material changes should really only be made when there is a change in the circumstances of the investor and the temptation to ‘just do something’ should be resisted. A well-diversified, appropriately positioned portfolio is likely to do the job required of it as long as it is given enough time. Develop an appropriate investment plan and stick to it.

In particular, make use of two powerful tools available to investors:

  • Sometimes referred to as ‘the only free lunch in investing’, appropriate use of diversification improves the surety of investment outcomes.
  • You are saving for your retirement and the investment horizon should match. Recent market returns make for entertaining table talk, but it’s the long term average outcome that determines one’s quality of life in retirement. Asset allocations should be set for the long-run balance between risk and return rather than trying to predict what’s going to happen in the next few months.

One of the fundamental tenets of asset allocation should be: MORE TIME = MORE SURETY

Be the patient investor and let the market transfer money from the impatient to you.


Stuart Eliot is Portfolio Manager at BT Investment Management. See more details on BTIM’s Diversified Funds here. This information is for general information only and has been prepared without taking into account any recipient’s personal objectives, financial situation or needs.


  •   5 May 2016
  • 3
  •      
  •   
3 Comments
Fundie
May 05, 2016

In my opinion, the advice to be “patient” and just “buy & hold” needs a warning – eg Japanese invstors who ‘bought and held’ in any time in the 1980s are still patiently waiting – 30 years later. Likewise anybody who bought the US index in 1929 had to patiently wait until 1954 to get back to square one – etc. History has shown that return outcomes are more about TIMING. Patience (time in the market) is only good if you don’t mind having to wait up to 30-40 years to recover from losses – if you pick the wrong time to buy. Timing is everything.

Jerome Lander
May 05, 2016

Relying upon about the second most successful market ever (the US) to demonstrate your point is selection bias at its best.

There are many other markets where returns have been disastrous over long periods of time.

An understanding of the contemporary issues in investment markets would suggest that it is foolish to wholly rely and place your trust in untrustworthy markets and untrustworthy market participants to generate returns. While your average benchmark hugging or index manager might love an ignorant client base to do this so that they retain their assets without having to do much, unfortunately this is a one trick pony. The reality is things are much more complex than that.

Bruce Baker
May 05, 2016

The 2 comments above are precisely correct. To put it another way, in a secular bull market, any fool can make money - and buy-and-hold works well, In a secular bear market (as much of the West are non in), and in speculative bubbles (and you could argue that there at least a number of them around at this point in time), buy-and-hold tends to be disastrous. Yes, timing is difficult and error-prone, but there are times when buy-and-hold is a riskier strategy.
[As an aside, does any advisor training these days teach you anything about timing these days? If not it is lacking. I know when I did my Diploma of Financial Planning 20 years ago, they simply taught buy-and-hold .... and not a mention on timing .... except perhaps some discouragement to try. I not sure what proportion of Australian advisors have caught up with this, but at least a sizeable portion of American advisors have been grappling with these tougher timing-related issues because of the behaviour of the US share market from the dot com bubble.


Leave a Comment:

RELATED ARTICLES

Market entry – dip your toe or jump in all at once?

Four best-ever charts for every adviser and investor

The simplicity of this investing method hides its power

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.