Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 363

Is it time for a social impact credit system?

As the Covid-19 pandemic persists, the universal public health system continues to be stretched and the longevity of the subsequent global economic crisis remains uncertain. The consequential social impact is far reaching, exacerbating problems of poverty, mental health, social dislocation, domestic violence, and potentially crime, and the level of unemployment continues to rise.

The long-term social costs could be disastrous. As the economy continues to deteriorate, what happens to the low socio-economic segment of our community? Will economic resuscitation relegate social benefit programs? And what happens to climate change action? Will it continue to be the victim of political jostling or forgotten altogether?

It seems that all sectors of the economy are distressed. The government is fiscally exhausted, and the household sector is facing various challenges including increasing unemployment and already historically high levels of debt, which now stands around 120% of GDP. Furthermore, the small-to-medium-sized business sector is facing a decline in consumer sentiment, a raft of closures and a spike in potential bankruptcies.

Where do social and environmental causes turn to for support?

Is investment management our white knight?

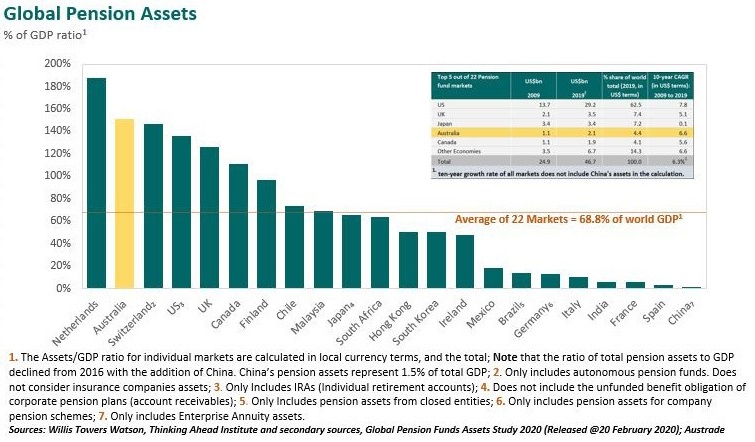
Two groups still have ammunition to spare: the corporate and institutional investment management sectors. The Australian Bureau of Statistics shows that the institutional investment management industry in Australia has funds under management of almost $4 trillion. According to the Willis Towers Watson Global Pensions Asset Study 2020, the superannuation sector is the largest within the industry and finished 2019 with the world’s fourth-largest superannuation market.

Before the onset of the Covid-19 pandemic, Australia also experienced one of the highest growth rates of superannuation fund assets in the world. Assets rose to 151% of GDP in 2019, representing an increase from 110% a decade ago, and a compound annual growth rate of 9.2% between 2009 and 2019. Fast, long-term growth rates have now created the second-highest superannuation asset to GDP ratio among the world’s 22 major superannuation (pension) markets.
How can our white knights rescue us?

An increase in asset allocation to Social Impact Investing (SII) is a possible solution. SII is defined as the type of investing that generates positive financial and social change. SII is differentiated from traditional investing by its intent and measurement so that both financial and social returns (impact) can be identified. Impact Investing Australia, an independent not for profit organisation, which serves as the operating entity of the Australian Advisory Board on Impact Investing (AAB), suggests that the market in Australia will reach $32 billion by 2022—although acknowledges that precise figures are difficult to determine. Nevertheless, this is dwarfed by the Australian ethical investment market, which has over $630 billion of assets under management.

An obvious application of SII is as a co-investment strategy between government and private sector organisations. Through a variety of agreed social investment activities, government could enhance social welfare outcomes and generate efficiencies. A co-investment strategy is a productive means for government to enhance economic outcomes through the multiplier effect. The alleviation of poverty and potential reduction in unemployment translates into higher consumption, taxation revenue and GDP growth.

Moreover, supplemental social benefits will accrue. One of the challenges in the growth of the SII market is the greater level of uncertainty of returns. So how can we incentivise SII? The answer can be found in the development of a universally accepted and applied social impact credit system.

Social impact credit system

The social impact credit system is one that is designed to attribute value to investments that generate a positive impact to society. It assigns a score for each SII, taking into account the nature and amount of the investment. Scores, otherwise known as credits, can be publicised by the investor thereby promoting their own corporate social responsibility (CSR) and perpetuating a ‘good corporate citizen’ perception.

It is a model that allows comparisons between organisations and incentivises social investing, volunteering and gifting in society. Ultimately, the concept of routinely incorporating CSR considerations into investment decisions could find its way into corporate mission statements, investment mandates and strategy and policy documents. This would engender a way of doing business that considers social as well as financial outcomes in investment decision-making frameworks.

Industry has struggled with the reporting of their social impact, whether through their annual reports or other media due to two major issues.

Firstly, there is the complexity and ambiguity relating to some measurement methodologies, many of which utilise subjective data.

Secondly, there is disagreement as to the preferred model. The absence of a simple universal measurement methodology accepted and used by all corporations, hinders comparisons between entities and discourages its application.

A unique social credit system has recently been established in China that suits its cultural and political system. The difference is that it is targeted at individuals instead of corporations. The Chinese system rewards individuals’ positive moral behaviour with credit points and applies negative points for anti-social behaviour. This system is unique to China and in no way reflects the proposed system for Australia. However, the common theme between the two systems is its intended influence over behaviour.

The measurement problem

Resistance to SII from the corporate sector has largely stemmed from the deficiencies and variability of various impact measurements. Effective impact measurement is essential in the corporate setting, where accountability and efficient allocation of resources is an institutional practice. A sound measurement model not only assists investors but is helpful for investees by aiding them to assess their own performance in meeting targeted social goals and use results to inform engagement in future projects.

According to a UK study in 2011, Gibbon and Dey favour a measure known as social return on investment (SROI) which accommodates key characteristics of simplicity and clarity. The ‘SROI ratio’, simply calculates a quantitative ‘return’ on a notional dollar of investment. The appeal of this measure is its bias towards quantitative factors that are well understood by industry. The model relies less on subjective factors, which use ‘financial proxies’ to quantify ‘soft outcomes’. It would seem logical for any research for a measurement methodology to consider a linkage to social development goals (SDGs) to satisfy the universal call to action to end poverty, protect the planet, and ensure that all people enjoy peace and prosperity by 2030.

A comprehensive study in 2017 by Rawhouser, Cummings, and Newbert in the Journal of Entrepreneurship, Theory and Practice found that standards for measuring an organisation’s social impact are fragmented and underdeveloped. Therefore, they obfuscate a clear understanding of trends and best practices regarding their conceptualisation and measurement. One important observation is the need to devote resources to the collection of new data sources in order for social impact research to progress quickly.

A call to arms

The progress of research in the development of a universal measurement model to advance the acceptance of a social impact credit system should be facilitated by a concerted effort between government, academia and the corporate institutional investment management sectors. An independently controlled administrator is recommended to gather and centralise data, monitor social impact credit measurement, and compile and publish scores.

Only with a consensual approach can a universal measurement model be accepted by the SII community. This is a call to arms for a champion to further this cause.


Dr. Paul Mazzola is a lecturer in banking and finance in the Faculty of Business at the University of Wollongong. The author wishes to thank Mr Greg Peel, Mindhive, for his insightful contributions to this article.


  •   24 June 2020
  • 10
  •      
  •   
10 Comments
Judy Henderson
June 24, 2020

Are you aware of the Global Reporting Initiative, setting global standards for non0financial reporting?

Paul
July 12, 2020

Hi Judy, thanks for your comment. In fact I am inspired by the GRI. However I’m attempting to promote a discussion around the benefits of a social impact credit model which is more concerned with scoring investments as to their impact. A measure can then be used to rank investments and organisations as to their impact. The GRI is doing great work around disclosure which is different from a scoring model. Although some models exist, there is no dominant or universally applied one as yet. Lots of work is still needed.

George Hamor
June 25, 2020

Really? From someone lecturing in a Department of Business? Cogitating about the “universal call to action to end poverty, protect the planet, and ensure that all people enjoy peace and prosperity by 2030”?
Utopia and Nirvana rolled into one!

Paul
July 12, 2020

Thanks for your comment George. Whatever we can do to help social and environmental causes is definitely worthwhile. If the investment community or even a Finance academic can expand the debate relating to the development of a universally accepted model which could incentivise SII, then it is adding value. Utopia would be when SII becomes mainstream whilst generating consistently acceptable returns. There are fund managers already doing this. We just need more.

Chris
June 26, 2020


I have a PhD in a hard science area and so, academic writing is nothing new to me, but using buzzwords and phrases like "social investment activities", "social welfare outcomes" "generate efficiencies", "social impact research" and "co-investment strategy" without explaining what they are or giving examples thereof only loses the reader and confuses them. 

If, as the literature states, social impact research is being measured and interpreted so badly, then why does the author say we should "devote resources to the collection of new data sources" ?

In short, my understanding is that they want our super funds to use our dollars to champion social and environmental causes, it would seem.

No thanks. I am apolitical and I invest my money to make more money - it's my money, not someone else's to waste without my say so, to "save the trees" or champion some misguided agenda that is the flavour of the month, least of all to give money to support any particular group, be they unions, an activist group, a religious group, a political party, business lobby or otherwise. If I want to do this, I'll donate to those causes myself or tick the 'socially responsible' option on my super fund and feel warm inside whilst I go for a poorer performing option.

And in any case, as soon as I hear words like "social" and "credit", wrapped up in feel good phrases like "end poverty" and "climate change" it reminds me too much of a communist society. Again, no thanks, I'm already getting enough of this right now with "social" distancing and "socially responsible" companies.

John
June 27, 2020

100% agree with Chris' comments ( that he posted on 26 June 2020)

Warren Graham
June 29, 2020

100% Agree with Chris

matthew smith
June 27, 2020

Dr Mazzola, this is too sloganistic.

AlanB
June 29, 2020

Isn't this just a form of ethical investing, which is already available? You can't manipulate our choices to implement your own agenda.

Paul
July 19, 2020

Alan, please read the article carefully. It is not about manipulating choices. It is a call for the development of universally accepted measurement model which can facilitate social impact investing. There are many asset allocation choices in the market. No one is trying to force your hand.


Leave a Comment:

RELATED ARTICLES

Sustainable investing focuses on the future

Investors expect ESG issues to drive returns

The rise of socially responsible investing

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.