Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 277

Sustainable investing focuses on the future

In the rapidly-evolving world of socially-conscious investing, sustainability has arrived. The integration of environmental, social and governance (ESG) factors into fund managers’ fundamental research processes has become mainstream in recent years. However, sustainable investing takes that approach one step further by also considering the impact a company has on society.

Sustainability is gaining traction with investors, but it is not without challenges. Typically, socially-conscious strategies have focused on negative filters, without taking into consideration the positive contribution a company might have on society. Investment returns can be compromised due to constraining the investment universe and data. Each companies’ ESG performance can be of variable quality, resulting in many arguable or 'grey' areas.

The rise of sustainable investing

Research conducted by Responsible Investment Association Australasia (RIAA) in 2017 shows that nine-in-10 Australians think that sustainable investing is important. Furthermore, 63% of Australians expect their advisers to incorporate their values and the societal or environmental implications of investments. Millennials are leading the charge. One key attribute of Millennials, now aged in their 20s and 30s, is their stated desire to live lives consistent with the values they espouse. About 84% of them say they want to invest in a socially-responsible way and their influence will grow as they become older and richer.

International organisations such as the United Nations and European Union are encouraging corporates to generate company profits in a positive and sustainable manner. Many of the world’s leading companies now consider sustainability in their corporate strategies, including Coca-Cola, Apple, BMW, Adidas, and H&M.

The United Nations has developed its Sustainable Development Goals Agenda (SDGs), a set of goals which, if achieved, would ‘end poverty, protect the planet and ensure prosperity for all’ by 2030. Broad and ambitious in scope, the SDG Agenda addresses the three dimensions of sustainable development: social, economic and environmental, as well as important aspects related to peace, justice and effective institutions. These goals are shown below.
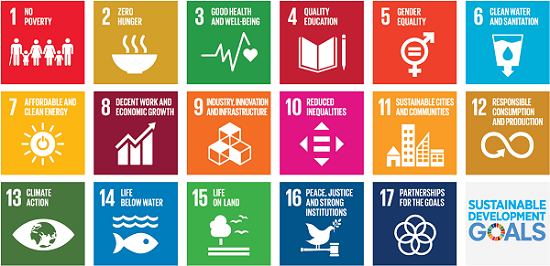
Assessing the extent to which a company’s operations and products support the SDG agenda is an appealing way to address broader sustainability.

The investment manager as advocate

The investment industry is also evolving and, in some areas, driving the change. Simply having a ‘clean hands’ approach is no longer good enough. Many existing socially-conscious funds purely screen and exclude whole industries on the basis that they have a negative impact on society. This approach strictly reinforces a company’s adherence to ESG principles but fails to consider whether a company is contributing positively to society.

We believe investment managers should also be playing an ‘advocacy’ role, by putting pressure on individual companies to improve their ESG performance. In turn this operational improvement can lead to improved financial outcomes, along with the broader positive impact to society.

The dilemma for investment managers has been their fiduciary responsibility: their primary goal is generally to maximise returns for a targeted level of risk. In the past it has usually been assumed that pursuing both social good and profits would damage investment outcomes, as screening out potential investments or pursuing goals other than profit maximisation might result in the missing of opportunities. These are legitimate concerns and have often resulted in an unwillingness to commit to socially conscious investing.

However, investing sustainably doesn’t necessarily mean sacrificing potential returns.

Investing for good and for returns

The most common objection to investing with a social conscience is that an investor needs to sacrifice returns to invest for the greater good. An increasing body of evidence is beginning to challenge this view, and the outcomes achieved by some such funds suggest it is possible to have both. Industry research summarised by Willis Towers Watson in their paper ‘Show me the evidence’ confirms better ESG scoring-companies tend to provide moderately better risk-adjusted returns over the long term. From the evidence collected to date, Governance (‘G’) and company engagement have proven to lead to a positive impact on returns.

A commonality across the research points to a heightened quality factor via a lower cost of capital which in turn leads better stock performance. Published University of Oxford research by Clark, Feiner and Viehs (2014) on over 190 sources showed 90% of the studies on the cost of capital demonstrate that sound sustainability standards lower the cost of capital for companies. 88% of that research showed solid ESG practices result in better operational performance of firms.

Alphinity agrees with Willis Towers Watson’s conclusion:

“Astute long-term investors understand that ESG factors are not necessarily non-financially related factors, as is often perceived, but rather an additional source of insight into the risk and return profile of that investment.”

Selecting better scoring ESG companies is likely to become another pillar of active management, along with conviction, skill and a disciplined consistent approach.


Stephane Andre and Bruce Smith are Principals and Portfolio Managers at Alphinity Investment Management, a boutique fund manager in alliance with Fidante Partners, a sponsor of Cuffelinks. This article is for general information only and does not consider the circumstances of any individual.

For more articles and papers from Fidante, please click here.


  •   23 October 2018
  • 2
  •      
  •   
2 Comments
Ashley
October 24, 2018

I want to see returns measured to the last basis point on specific investment decisions based on concrete ESG rules. That way investors can make informed decisions about the trade-offs. On the other hand If ESG actually improves returns – then you should shout from the rooftops – with specific details on each ESG decision so people can test.

Bruce Smith
October 25, 2018

Hi Ashley, thanks for your comment. Our message from this article is that people are increasingly looking for funds that consider more than just returns, but that you don't necessarily have to get lower returns when you do that.

In reality, no decisions are ever made purely on the basis of ESG, it is one of many things we look at when investing in a company. In the end portfolio returns are a function of the stocks in the portfolio and the weighting of those stocks. The fact that there are 12 ESG-focused equity funds in the latest Mercer table and the range of those funds' performance over the year to August is as low as 10.5% and as high as 24% (8% pa to 14%+ pa over three years) suggests to us that the robustness of a manager's investment process and its skill in selecting stocks is going to be a more important determinant of returns than ESG considerations alone. We've found that a "bad" company is not necessarily a bad investment, and a "good" company necessarily a good investment. But we have also found that taking ESG into account can alert you to risks and, in some cases, help you to identify opportunities.

ESG is one of the positive screens we employ, the other is the extent to which a company addresses Sustainable Development. But the final decision to invest requires the company itself to be a good investment according to our investment process, undervalued companies in an earnings upgrade cycle, which has delivered good alpha over the almost 15 years we've been applying it.


Leave a Comment:

RELATED ARTICLES

Why ESG can still play a crucial role in investor portfolios

Beyond the acronym, navigating important ESG choices

Mike Murray on watching for the changing narrative

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.