Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 401

Let's be clear: sustainability isn’t free

There’s a school of thought in parts of the investment community that the increasing focus on corporate sustainability is the ultimate win-win. This group contends that if employers pay their people more, it will result in higher sales and productivity and will ultimately reduce costs. They reason that cutting emissions will not only help the planet, but also bolster companies’ bottom lines.

Unfortunately, the reality couldn’t be further from the truth. Sustainability isn’t free, and in our view, efforts to become more sustainable will challenge many companies and perhaps even bankrupt some of them.

Accelerating trends

The pandemic accelerated many well-documented secular trends such as digital media, cloud computing and work-from-home. But it also hastened less obvious ones, such as loneliness, wealth inequality and interestingly, investor demand for changes in corporate behaviour.

While we can point to numerous data points to illustrate mounting investor interest in ESG (Environment, Social and Governance) through fund flows, to us, what’s more noteworthy is the growing recognition by management teams of the need for more sustainable business practices.

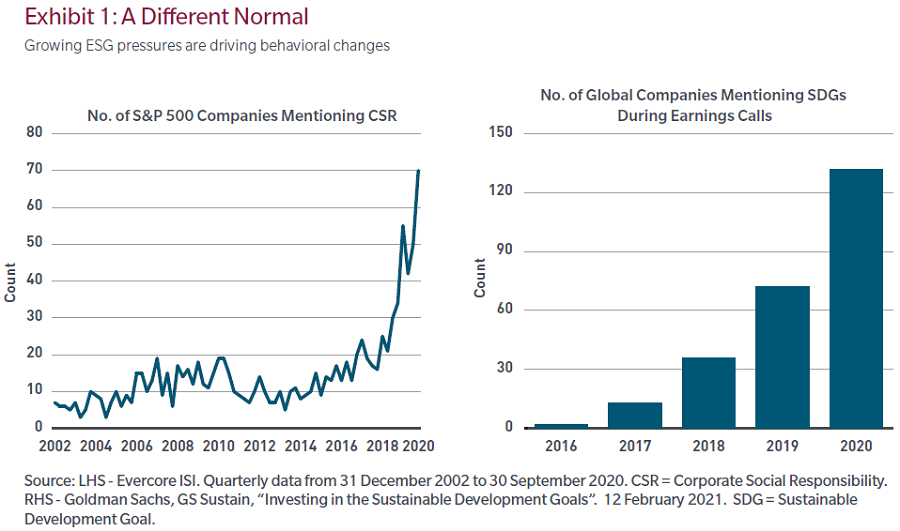
For instance, as shown on the left-hand side of Exhibit 1, there was a jump in the number of S&P 500 companies that referenced corporate social responsibility (CSR) in quarterly earnings calls during 2020. The right-hand side of the exhibit looks at the number of global companies that referenced, during earnings calls, any of the 17 Sustainable Development Goals (SDGs), a set of global objectives agreed to by the UN General Assembly in 2015 to improve the quality of life worldwide. It shows a similarly large year-on-year increase.
Why sustainability matters

There is a long list of reasons why civil society, governments and special interest groups are concerned with ESG issues. The most notable one, of course, is that addressing them is critical to the long-term success of our global community. The ramifications, for example, of issues such as runaway climate change or rising income inequality, if left unresolved, are likely to be profoundly negative.

Our point of emphasis, however, is the changing reaction function of companies. Now that investors are focusing on sustainable business practices, management teams have begun to pay attention. And that matters. A lot.

Materiality is key

Sustainability will drive new business opportunities for some while exacerbating risks for others, leading to substantial divergences in the long-term enterprise value of many companies. But what is largely lost in the current ESG narrative is financial materiality. Which of course affects financial asset prices.

A sharp rise in the US minimum wage, for instance, would no doubt challenge a number of business models. Certain retailers would face particular challenges. If companies in this sector are going out of business at an alarming rate while paying the US federal minimum wage of $7.25 an hour, how can they possibly hope to survive if the wage increases to $15?

Some retailers will be able to adapt due to their competitive positioning or other strengths, and in fact some already have, with bonuses and salary increases since the pandemic began, but many will find that sustainability concerns pose major challenges to their profitability.

Producers of fossil fuels and companies reliant on their use will also face high hurdles. Many in the oil industry are banking on a growing middle class in emerging markets to underpin demand and help maintain the status quo. However, over two-thirds of oil demand is tied to automobiles powered by internal combustion engines, and we believe that mode of propulsion will become antique in the not-too-distant future. Cumbersome organisations that are slow to recognise and adapt to this change are unlikely to survive.

Many incumbents will struggle

Looking back over the past 100 years, one thing is clear: Industry incumbents don’t fare well in the face of disruptive technologies. And the move toward sustainability is a disruptive force akin to the industrial revolution or the advent of the internet. It will define society and the investment landscape for decades.

But it won’t be free. There will be winners and some very big losers. This new paradigm is unfolding during a period in which risk premia are at all-time lows, underlining the importance of allocating capital responsibly.


Robert Wilson is a Research Analyst, and Robert M. Almeida is a Global Investment Strategist and Portfolio Manager at MFS Investment Management. This article is for general informational purposes only and should not be considered investment advice or a recommendation to invest in any security or to adopt any investment strategy. Comments, opinions and analysis are rendered as of the date given and may change without notice due to market conditions and other factors. This article is issued in Australia by MFS International Australia Pty Ltd (ABN 68 607 579 537, AFSL 485343), a sponsor of Firstlinks.

For more articles and papers from MFS, please click here.

Unless otherwise indicated, logos and product and service names are trademarks of MFS® and its affiliates and may be registered in certain countries.


  •   31 March 2021
  • 5
  •      
  •   
5 Comments
George
March 31, 2021

Finally, a reality check on all the ESG stuff, that some companies will be losers and it's not one jolly joy ride for everyone.

Warren Bird
March 31, 2021

This is a strange article. Ever since ESG first came onto the radar with the United Nations Principles for Responsible Investment being launched and fund managers signing up to the PRI around 15 years ago, the emphasis has been on how ESG factors create investment risk that needs to be managed.
Investment risks, as in things like the potential for stranded assets as the world moved away from fossil fuels.
Investment risks, as in the the potential for companies that failed to take social responsibility seriously being abandoned by their customers.
Investment risks, as in the potential for a company that had a governance failure to see share price damage from the loss of reputation that went with that.

I'm not aware of anyone who has taken ESG seriously EVER talking about there being no 'losers' as a result of responsible investment becoming the way that capital was deployed in the market.

I'm not aware of anyone saying that adapting to a world in which ESG factors are taken seriously was going to be, to use George's words in his comment, 'one jolly ride for everyone'.

It was always - and still remains - a transition that the world must make and will make to a sustainable future, with the transition resulting in certain activities that are currently making money becoming loss making.

And certainly, as we've seen with the Rio situation last year, there will be losers among corporate executives who don't take it seriously!

So, as I said a strange article, a bit of a strawman argument I'd have thought. What it says is true enough - ESG investment principles becoming mainstream are a massive disruptive force. But it's not providing a much-needed reality check, it's just stating what the industry has known all along, I'd have thought. ESG risks are real and need to be taken into account if you don't want your investment portfolio to erode or blow up.

Michael Walsh
April 03, 2021

Hear hear Warren!

Carlo
March 31, 2021

A sort of aside comment if I may? When ESG became a serious factor for firms of any size or all is to my mind not seriously material. The real issue is it's positioning as the new corporate fad kid on the block (whenever it started) aimed at being seen to be interested in such responsibility areas either to earn a tick on surveys and/or to be measured as a socially responsible organisation. As such ESG has become somewhat generic now for most! It has to appear in credos, mission statements and objectives - BUT none of that ensures it's a living dynamic across a company. On the contrary I suggest - too many organisations's approach to ESG has become yet another symbolism to match internal and external expectations. So not sure whether measuring ESG is any guide to a company's performance.
Dealings with or analyses of any ESG company would quickly show that like so many other symbolic gestures eg CX, Quality, etc most organisations fall far short of genuine benchmarks - their own and external. As with Mission Statements or any other publicly claimed socially responsible benchmark - ESG has to become the living "soul" throughout all operations including customers, suppliers and so forth. Proclaiming an ESG culture seldom achieves that as many employees and outsiders recognise. Carlo

Warren Bird
April 05, 2021

I agree with you Carlo. As the CEO of a business that's been investing according to responsible principles for 40 years, while I believe that there's a lot of very genuine improvement in company behaviour in relation to ESG, there's a long way to go. The failure of ethics at Rio last year is a case in point - all the 'talk' from Rio in presentations to investors during the last few years had been about them taking a more responsible approach, but when it came to the 'walk' it all blew up in their face.
I think that among the investment management industry, there's been a lot more definite movement in the direction of serious, genuine ESG adoption. At the Uniting Church we think we're actually well ahead of most, having evolved how we implement our principles into our decision-making more and more deeply over the years. Our current focus is the alignment of our ethical principles with the Sustainable Development Goals, an alignment that was signed off externally for our pioneering Sustainable Bond issue 18 months ago, but we definitely feel the competition breathing down our necks.
Part of what we do is to engage (directly and through our external managers) companies on key issues to encourage genuine adoption of responsible practices. EG we're encouraging companies that are below the legislated threshold in respect of Modern Slavery to voluntarily comply and report.
The phrase I use is that ESG, or ethics, or responsible investing, needs to be in a company's or an investment manager's DNA - similar to your 'living soul' idea. We're quite a way from that, but things are moving.


Leave a Comment:

RELATED ARTICLES

10 lessons from Larry Fink's 2022 Outlook

Why ESG assessment must now consider active ownership

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Will you run out of money in retirement?

Fear of running out has become a defining retirement anxiety. Why do some retirees die with substantial wealth while others deplete their nest egg? Evidence suggests the answer is more complicated than we think. 

The investment that sidesteps the new tax traps

Tax rules have changed, but many investors are still using yesterday’s strategies. Insurance bonds may offer advantages for those seeking greater control, tax efficiency and certainty about their wealth.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Latest Updates

Planning

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Investment strategies

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Economy

Population growth masks Australia’s productivity problem

For years, investors have benefited from a seemingly reliable growth story. But recent national accounts raise uncomfortable questions about what has really been driving Australia’s economy and whether that can continue unchecked.

Investment strategies

Why tomorrow’s winners may not be today’s index leaders

The stocks that built retirement balances over the past decade now dominate many portfolios. The new challenge is whether these companies can continue meeting the increasingly high expectations embedded in today's share prices.

Investing

What earnings surprises reveal about future returns

Sometimes the most important information in an earnings result isn't the number itself. It's the possibility that the market's assumptions have been fundamentally wrong and future earnings may look very different.

SMSF strategies

Individual SMSF Trusteeship directly liable for ATO fines

A rarely discussed detail buried in SMSF structures could dramatically change who wears the cost when something goes wrong. With penalties rising, a decision many dismissed as administrative may deserve a second look.

Investment strategies

The currency bet you didn’t know you made

Buying global shares means making two bets: on the companies and on the Australian dollar. Most investors consciously choose only the first. Last financial year, the second bet cost 8.5% in returns for many investors.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.